

Back in early May, I published a Deep Dive into Abbott Laboratories, a dividend king and one of the most diversified and durable healthcare giants in the world.
For perspective, Abbott is one of the true giants of healthcare, a 130+ year-old compounder with a diversified portfolio spanning medical devices, diagnostics, nutrition, and established pharmaceuticals, pulling in over $44 billion in annual revenue across 160+ countries. The crown jewel in its portfolio is FreeStyle Libre, Abbott’s continuous glucose monitor, which alone generates nearly $8 billion a year and anchors a broader medical devices segment that also includes a formidable cardiovascular lineup spanning rhythm management, electrophysiology, and structural heart, where Abbott holds genuine leadership positions rather than just participating.
On top of that, Abbott Diagnostics runs a sticky razor-and-blades model off its installed base of lab instruments, the nutrition portfolio brings consumer-staples-like stability (if not much excitement) through Ensure and Similac, and the established pharmaceuticals operation quietly grinds out solid margins in emerging markets on drugs Abbott didn’t even develop, creating a highly diversified revenue stream. Moreover, roughly 35-45% of revenue is genuinely recurring, the products it sells are largely non-discretionary, the company is in good financial health, reinvestment metrics are solid, and it has rewarded shareholders with 50+ consecutive years of dividend growth while compounding revenue and EPS at an 8% CAGR over the last decade.
And Abbott’s outlook looks pretty good too. As established and broken down in my May deep dive, underpinned by the strong growth expectations for its medical devices segment, especially glucose care, a fair base-case assumption is that Abbott will grow group revenue in the 7-9% range through 2030, likely easing to the 5-7% range from 2030-2035, largely driven by structural, reliable trends. That is excellent for a reliable, non-cyclical giant.
You can check out my deep dive, linked to below, for a full breakdown of the business and its growth prospects.

Anyway, following my deep dive and with Abbott shares trading at decade-low multiples following a string of disappointing quarters, a $21 billion acquisition that has added debt and near-term dilution, a product recall, and a brutal sector-wide rotation, I actually initiated a starter position in Abbott in May, as I believed the combination of significant room for multiple expansion under normalized conditions and the prospect of reliable high-single digit revenue growth and low-double digit EPS growth could translate in excellent long-term returns.
Now, following the second quarter results released by Abbott earlier this month and a 20%+ share price run-up since my previous coverage, I believe it’s time to update my view of the stock by breaking down the Q2 results and recent developments before updating my financial framework and thesis.
This is my Abbott Laboratories Q2 2026 update. Without further ado, let’s delve in!
This is a paid-exclusive analysis. Want full access? Consider upgrading to InvestInsights PRO for $9.50 a month or $95 a year! This gets you:
6–8 Research Reports per month, 2x more than free subs do, including 3-4 Deep Dives and 2 mid-week analyses (that comes down to just $1 per analysis)
Full visibility into my personal portfolio, including allocations, transactions, and conviction levels
An overview of target prices and ratings, updated weekly
InvestInsights Premium is designed to help you find best-in-class compounders, identify deep-value opportunities, avoid costly mistakes, and stay focused on fundamentals when markets get noisy, with full transparency into how I make decisions over time.
Financial & Performance Review
Abbott released its second quarter 2026 results on July 16 and impressed investors, with shares gaining 11% in the following trading session, driven by the company surpassing consensus estimates, delivering accelerating revenue growth, healthy margins, and raising FY26 guidance amid improved business momentum.
Starting at the top, Abbott reported total Q2 revenue of $12.6 billion, which beat the consensus by $70 million and reflects a YoY growth of 13%, although that includes a mild currency tailwind as well as the contribution from Exact Sciences, which Abbott acquired late in Q1, so this was the first full quarter.
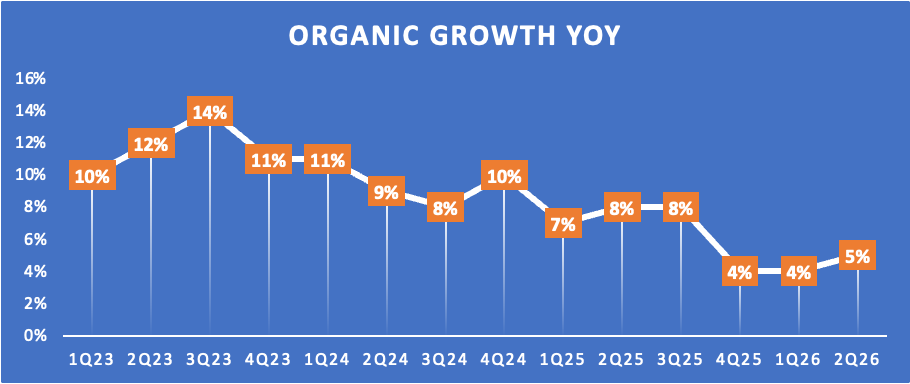
Much more importantly, Abbott reported organic sales growth of 4.8%, showing a promising acceleration from the prior two quarters. Moreover, management disclosed that growth accelerated each month during the quarter, so we are seeing a clear improvement in momentum.
For reference, Abbott delivered weak growth numbers in the prior two quarters due to coinciding headwinds, primarily recent pricing actions in Nutrition, a weak respiratory virus testing season for Diagnostics, and an underperformance in FreeStyle Libre sales due to an international tender renewal delay and tough comparisons from shelf-restocking.
Therefore, the improvement in growth in Q2 is great news, a really positive indication, and this is likely to improve further in the coming quarters.
Breaking down organic sales by region, the U.S. was up 3.5% YoY compared to 2.5% in Q1, mainly driven by a slight improvement in Nutrition sales and an uptick in Diagnostics. International sales were up 5.8% YoY, an improvement from 5% in Q1, mainly due to Nutrition growth turning positive.
Delving into each operating segment, let’s start with Medical Devices, which delivered comparable sales growth of 8.4% YoY to $5.85 billion, or 46% of group revenue, which was roughly in line with Q1.
Within this, cardiovascular revenue was up 8.5% YoY, driven by low-teens growth in Electrophysiology and high single-digit growth in Rhythm Management and Heart Failure.
Electrophysiology is the most exciting piece here, with growth accelerating nicely, driven by the launch of the next-generation Volt PFA catheter in the U.S. in May and the strong adoption of Volt and TactiFlex Duo in international markets, driving 20% Electrophysiology growth in Europe. With the rollout of the next-generation Volt PFA catheter internationally happening in Q3, we will likely see growth accelerate further in the remainder of the year, with Abbott guiding for market outperformance and strong market share gains in a market already projected to grow double digits through 2030.
Meanwhile, Rhythm Management sales grew 9.5% in Q2, driven by the expanding use of AVEIR across both the single- and dual-chamber segments of the pacemaker market and broader adoption of the technology internationally. Finally, Heart Failure sales were up 9% YoY, led by double-digit growth in the U.S., with Abbott fully benefiting from its market-leading position in heart assist devices and strong demand.
Moving to diabetes care, the larger portion of the Medical Devices segment, Abbott delivered 9.5% growth in Q2 to just over $2 billion, an improvement from 7.5% growth in Q1 but still trending below the double-digit growth Abbott has been able to deliver historically.
The market potential remains clearly there, with a CGM addressable of 75-80 million people globally, but only 15 million addressed so far, with the primary limitation being a lack of reimbursement, and this is what is holding back growth today, according to management. Simply put, we are currently in a period where there is a lack of major reimbursement expansion, which is plateauing growth in the 8-9% range – still far from bad, but not quite what investors are aiming for.
Positively, management indicates there are active discussions around reimbursement in over 12 countries to either introduce or expand this. Once any of these markets introduce or expand reimbursement, this should drastically accelerate growth in Abbott’s glucose care business, but the timing is uncertain. According to management, it is not a matter of “if” but “when”.
Take type 2 diabetes in the U.S. The potential expansion in the U.S. for type 2 diabetes is huge, unlocking around 10 million Medicare beneficiaries and translating into a multi-billion dollar opportunity for Abbott. So, long story short, diabetes growth is capped by a lack of new reimbursements, but the pipeline is there, and the unpenetrated market is still huge. Nonetheless, I think 9.5% growth in Q2 is nothing to complain about.
On another note, Abbott secured the CE Mark for Libre Duo, the world’s first dual glucose-ketone wearable sensor. Abbott plans to start shipping these internationally in the fall and seeks U.S. approval in the near future.
Let’s then move to the diagnostics segment, where Abbott delivered organic growth just shy of 3% to $3.1 billion. This was driven by 7.5% growth in Core Laboratory in the U.S., offset by an 8% YoY decline in Rapid and Molecular Diagnostics sales, driven by the anticipated decrease in respiratory virus testing as a result of a weaker-than-normal season, the same factor impacting Q1.
However, the real Diagnostics standout was Cancer Diagnostics (acquired through Exact Sciences), up 13% YoY, driven by mid-teens growth of Cologuard.
For reference, Cologuard is a non-invasive, at-home colorectal cancer screening test that analyzes a stool sample for altered DNA and hidden blood. Patients collect the sample themselves and mail it to a lab rather than undergoing a colonoscopy, which makes it a popular option for average-risk adults 45 and older who want a less invasive first-line screening choice. In May, the American Cancer Society updated its colorectal cancer screening guidelines, reaffirming Cologuard and Cologuard Plus as preferred screening options, which is a strong proof point for Abbott, now the global leader in non-invasive cancer screening.
Management expects Cancer Diagnostics growth to accelerate in H2, supported by increasing volumes from care gap programs, recently launched tests, and continued international adoption.
Next up is the Nutrition segment, which has been a pain point for Abbott in recent quarters, or really, years. In 2022, Abbott faced a huge recall due to concerns over Abbott’s cow milk-based preterm infant formulas causing necrotizing enterocolitis (NEC) in premature babies, doing serious reputational damage to the Similac brand. On top of that, Abbott had been raising Nutrition prices quite aggressively in 2023 and 2024 to recover pandemic-era cost inflation, but that suppressed volumes. Therefore, in Q4 2025, management implemented strategic price reductions to reignite volume growth, but this created an immediate revenue headwind, as ASPs fell before volumes recovered.
As a result, Nutrition revenue was down 8% YoY in Q1, significantly dragging on Abbott’s overall performance. Positively, Q2 numbers show progress ahead of expectations, with sales increasing sequentially and growth improving. International sales already returned to positive growth, driven by a 6.5% YoY improvement in Pediatric Nutrition. Moreover, Adult Nutrition saw positive volume trends, with retail consumption of Ensure increasing double digits in the U.S., delivering the highest YoY consumption growth in the past 1.5 years.
Nonetheless, overall Nutrition sales were still down 3.6% YoY on a comparable basis, but clearly showing improvement ahead of expectations. Management expects both Adult and Pediatric Nutrition sales to get back to positive growth in the second half of the year.
Additionally, the U.S. Justice Department closed a criminal probe into Abbott in late June related to the baby formula recall, opting instead for civil penalties, which is great news and further removes this overhang.
Finally, there is the Established Pharma segment, which continued to be a strong, consistent performer. Comparable sales were up 8.7% YoY, reflecting broad-based growth across large markets, including India, Latin America, and Southeast Asia. This segment continues to deliver solid growth amid rising demand for health care in emerging markets, driven by expanding access, aging populations, and a growing need to treat both acute and chronic conditions. These structural drivers should allow this segment to continue consistently delivering high-single-digit growth.
Overall, I am pretty pleased with this top-line performance. Abbott is showing strong results across the board and improved momentum in challenged segments ahead of expectations, exactly what I was looking for. Really, this quarter reflects strong execution, reaffirming my confidence.
