

Those of you who have been following my work for longer should know how much I adore American Express. This company is a true one of a kind and one of the best plays for the decade or two ahead in the payment processing sector.
Unlike most peers, this company operates as a closed-loop payments network, issuing its own cards and processing transactions directly. This allows it to capture a far larger share of each transaction’s fees and gives it much closer customer relationships and control. Yes, it also assumes the credit risk, but due to its focus on high-income individuals, this risk is minimal.
Furthermore, AmEx isn’t just a payments processor, as it generates revenue not just through its payments network but also through card fees and lending products. As I explained last time out:
“Through this entire control over the payment flow and the direct relationship with the customer, AmEx is able to offer more generous card benefits and rewards programs, such as Membership Rewards points, travel credits, and luxury perks. This is why most AmEx cards come with a fee for the consumer, somewhat similar to a subscription, creating recurring and highly reliable cash flows, while the model drives high spending and loyalty.”
I believe this is one of the best models and business structures in the industry. It’s built for durability - sustainable, increasingly reliable, and designed to foster deep customer relationships and retention. With its unique ability to monetize both sides of the transaction and to continuously innovate its offerings, I believe AmEx is well-positioned for the coming decades and is likely to extend its lead.
As a result, this company is a must-own for long-term investors, combining solid growth, a mega moat, and outstanding durability.
AmEx’s Q3 results once more confirmed my bullish thesis.
After reporting results one week ago, shares gained 7% in the following trading session on Friday, and I can tell you this price jump isn’t hard to justify. American Express continues to perform at a very high level, proving the quality and potential of its unique business model, and surpassing consensus estimates, as Wall Street just continues to underestimate this incredible compounder for decades to come.
For reference, with its Q3 results, American Express blows past consensus estimates, raises guidance, maintains a pristine credit portfolio that is in a class of its own, and delivers accelerating growth in an environment perceived as mildly challenging.
Honestly, investors couldn’t have asked for much more – I was impressed, and I already had high expectations.
Let me walk you through the results, putting these into perspective and reviewing the performance, before moving to update my medium-term estimates and target price.
Let’s delve right in!
Welcome to InvestInsights — an independent equity research publication rooted in long-term, buy-and-hold investing, publishing actionable stock/equity research reports weekly!
📈 You’re reading my latest exclusive stock analysis. If you like this analysis, make sure to like & subscribe to receive much more like this!
If you’d like full access to this post and all my exclusive analysis & portfolio access (14% CAGR since 2022), consider becoming a paid subscriber!
A Q3 Review
Let’s dive straight into the sublime numbers reported by American Express for its third quarter, released on October 17.
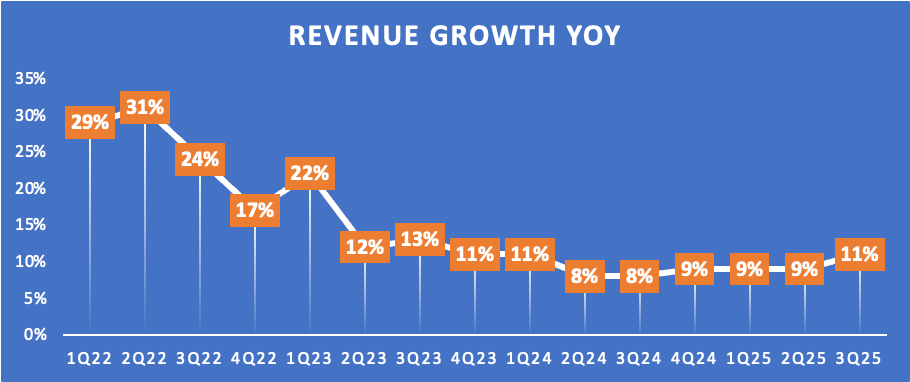
The company delivered revenue growth of 11% YoY to a record-high $18.4 billion, beating consensus estimates by an excellent $380 million. More importantly, this represents a mild acceleration in growth compared to prior quarters, driven by all revenue lines. In fact, this was the strongest YoY growth in over 1.5 years, coming in well ahead of expectations, especially impressive given the slightly challenging market conditions.
Driving this acceleration in growth were primarily strong card member spending or processed volumes. Platform spending growth accelerated to 9% YoY (8% FX-neutral), up from 7% in Q2 and marking the best volume growth in over two years!
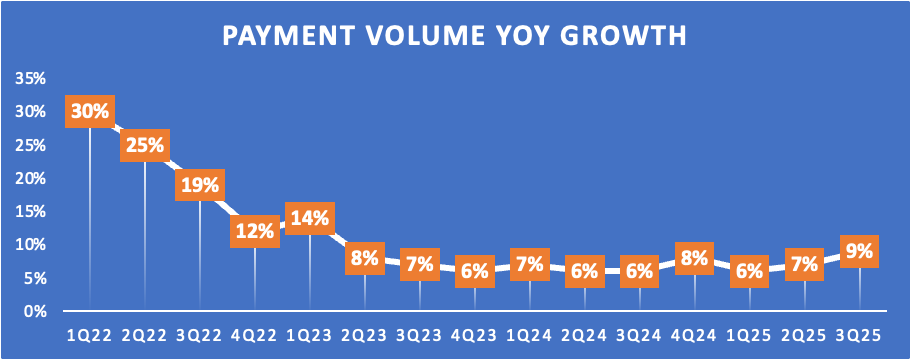
The almost 2 percentage points step up in growth compared to Q2 was driven by strong retail spending (up 12%) and a bounce back in travel (up 8%) spending. Additionally, AmEx continued to see strong momentum in spending by Millennials and Gen Z, which now account for 36% of total spend.
This volume growth was also broad-based across geographies, with 3 of its top 5 markets growing by 18% or more in Q3. Its largest region by volumes – the U.S. – saw volume growth by 9% YoY, up from 7% in the prior two quarters, which is once again impressive. Meanwhile, international volumes grew by 13% YoY, up from 12% in Q2.
So, really, we can see excellent momentum across the board.
Strong card issuance and growing engagement, reflected by strong transaction growth, continue to drive this. In Q3, transactions were up 10% YoY, also accelerating from 9% in Q2. Most notable here is that AmEx continues to see especially strong momentum among its younger customer cohorts, with the average number of transactions for millennial and Gen Z card members about 25% higher than for older cohorts.
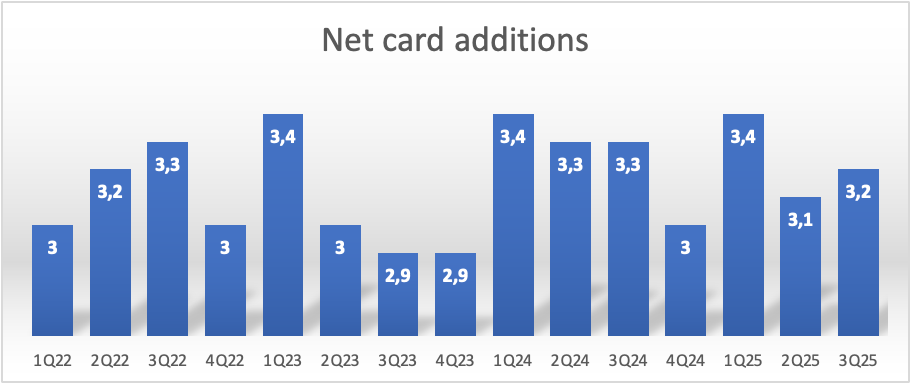
This same customer cohort continues to drive member growth. In Q3, AmEX acquired 3.2 million new cards, which is similar to the quarterly additions over the last 1-2 years. Notably, millennials and Gen Z accounted for 64% of new cards, and over 70% of new cards were acquired on fee-paying products.
This shows that AmEx’s customer base is increasingly shifting toward its fee-based cards, which is a very positive development, as this drives growth in card fees revenue, which is stable and recurring.
As a result, card fees were up 17% YoY in Q3. They are now approaching an annual run rate of $10 billion, having grown by double digits for 29(!) consecutive quarters and growing at a 17% CAGR since 2019. This reflects both the expanding adoption of these premium, fee-based cards and the company’s continued investment in richer rewards, travel perks, and lifestyle benefits, which is attracting more consumers.
Now, as visible below, momentum in fee revenue growth is easing a bit, but this is as anticipated and is expected to moderate further in the coming quarters, before we should see an inflection in 2026 to reflect the product refresh.
You see, in Q3, AmEx refreshed its U.S. Consumer and Business Platinum cards, which was its biggest refresh to date.
So, what exactly does this mean?
Essentially, the company has rolled out a significantly enhanced value proposition for its flagship product, raising the annual fee from $695 to $895 while adding over $1,000 in new lifestyle and travel benefits, including a $400 dining credit and a $600 hotel credit. Existing Platinum members are being given several months to experience the new benefits before the higher annual fee takes effect, which will then be applied gradually as cards renew over the next 12 months. Since card fees are recognized over a 12-month amortization period, it takes roughly 2 years for the full impact of this refresh to flow through to reported card fee revenue, with the largest contribution peaking about 1 year after the new fee becomes effective.
In other words, while growth in card fees is expected to moderate in the near term, it should reaccelerate meaningfully in 2026 as the pricing uplift and broader adoption of refreshed products begin to fully materialize. Early signs are very encouraging: initial demand and engagement have exceeded expectations, with new Platinum acquisitions running at 2x pre-refresh levels and retention remaining strong. AmEx has also seen record travel bookings following the refresh and the launch of its new all-in-one travel app, which is a clear indication that customers are engaging more deeply with the ecosystem.
More broadly, this refresh underscores AmEx’s core advantage: a global base of premium, high-spending customers who value rewards, experiences, and lifestyle benefits over basic transactional functionality. By continually enhancing its products and deepening relationships with both card members and merchants, AmEx reinforces a powerful virtuous cycle - higher engagement drives more spend, which in turn attracts more premium merchants and fuels reinvestment into better benefits. The result is a highly recurring, resilient, and compounding revenue stream that should remain one of the company’s most attractive long-term growth drivers.
Finally, let’s move to AmEx’s credit performance, which is sublime. Both U.S. consumer and small-business delinquency rates remain below 2019 levels.
Loan and card member receivables were up 7% YoY, roughly following the growth in its billing business, and credit performance was largely stable. Q3 delinquency and write-off rates remained very low. 30+ days past due is still remarkably low and stable at 1.3%, which is almost 3x lower than the peer average. Net write-off rates fell to 1.9%, down from 2.1% in Q1 and 2% in Q2, which is remarkable. Despite some macro concerns, AmEx clearly shows no weakness, similar to last quarter.
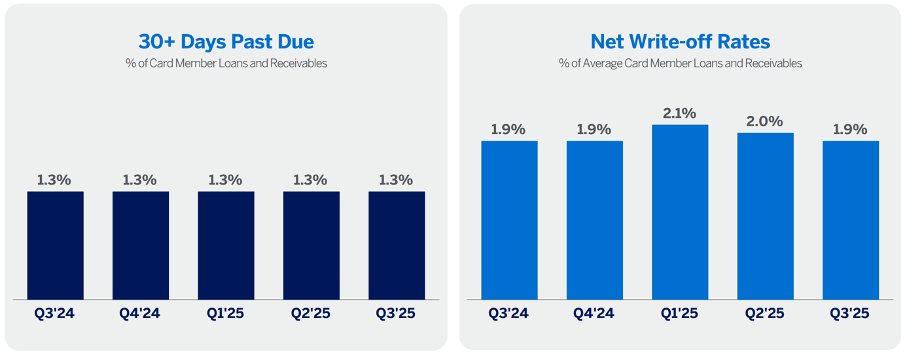
This remarkable credit performance can be entirely attributed to AmEx’s increasing focus on premium products, which tend to attract high-income, highly creditworthy customers.
This also allowed AmEx to keep provisions for credit losses low at $1.29 billion, which compared favorably to a consensus of $1.41 billion.
AmEx really maintains a best-in-class credit portfolio.
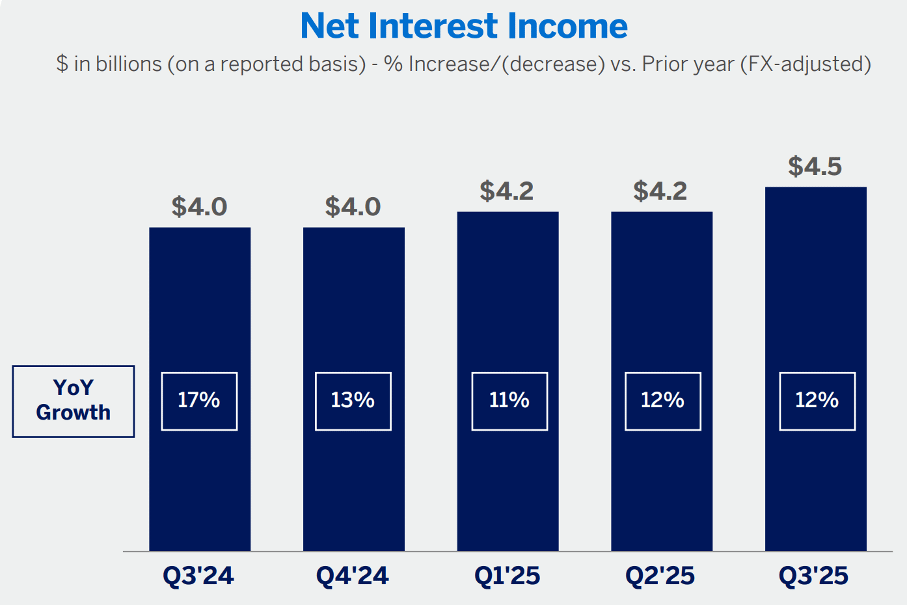
Ultimately, NII (net interest income) was up 12% YoY in Q3, driven by AmEx expanding margins on balances. Q3 NII was $4.49 billion, ahead of a $4.35 billion consensus.
On that note, let’s move to the bottom line, where AmEx is facing some near-term operational headwinds, yet it delivered excellent margins and cash flows, nonetheless. Despite heavy investments in premium value propositions, marketing, and technology, AmEx still managed to drive operating leverage, thereby strengthening margins.
Starting with variable expenses, VCE was up 14% in Q3, outpacing revenue and accounting for 42% of revenue. Driving this growth in VCE was a 25% YoY increase in card member services expenses, which was driven by strong early engagement with the refreshed U.S. Platinum benefits. Crucially, whereas the actual price increase will only be reflected in revenue in about 2 years, the costs of these added benefits are visible immediately, creating a near-term rise in variable costs as a percentage of revenue. We should continue to see this in the quarters ahead.
However, due to a combination of strong growth and operating leverage, management does still expect to deliver expanding margins in the years ahead. It continues to hold onto its medium-term targets.
As for remaining expenses, Q3 marketing and operating expenses grew by only 9% and 5%, respectively. As a result, total expenses were up 10% YoY, growing more slowly than revenue, resulting in mild margin expansion.
Down the line, this resulted in a net income margin of 20.6%, up 100 bps YoY, and an EPS of $4.14, up 19% YoY and beating consensus estimates by $0.16. Also, TTM ROE was a brilliant 36%.
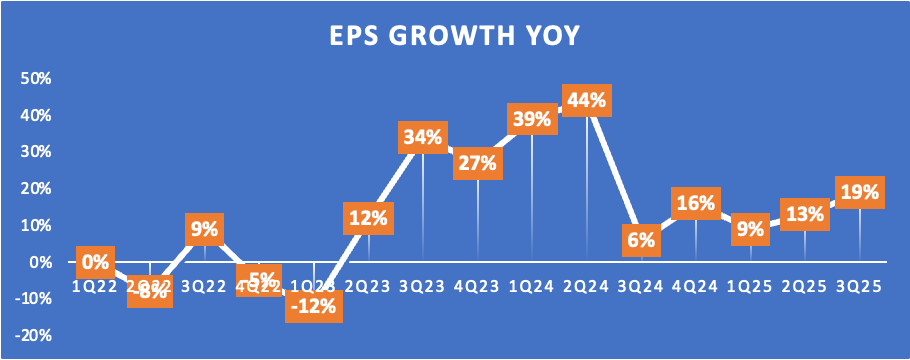
Overall, Q3 once again showcased the strength and consistency of AmEx’s model. Growth was broad-based, credit quality remains pristine, and the shift toward fee-based products continues to enhance revenue quality and recurrence. The Platinum refresh sets the stage for another leg of durable growth, deepening engagement among premium and younger customers. With strong execution, expanding margins, and clear visibility into accelerating fee income ahead, AmEx remains one of the most dependable long-term compounders in financial services.
On that note, let’s move to the outlook.
Want more out of your subscription? Even more content like this weekly?
Consider InvestInsights PRO - $7.50/month ($70/annually)
This gets you:
A guaranteed 6+ stock analyses every month (roughly 2-4 paid-exclusive).
Full insight into my own portfolio (14% return CAGR since 2022).
Instant transaction alerts anytime I make a move (Fully transparent).
A complete overview of all my target prices and ratings (online available).
Want to keep reading? You will get full access to this $AXP analysis!
