

Yesterday, April 15, Dutch semiconductor giant ASML released its second-quarter results, and it delivered what I would argue is one of its best reports in years, driven by booming demand.
Simply put, ASML is riding the strongest demand wave in its history, and it’s not hard to understand why. The insatiable appetite for advanced nodes — in both memory and logic — driven by AI and record infrastructure investments, is forcing ASML’s customers – like TSMC, Intel, Micron, SK Hynix, and Samsung – to pour capital into new capacity at a pace that would have seemed unthinkable just a couple of years ago. And here’s the beautiful part: large chunks of these CapEx dollars directly flow through ASML because there simply is no alternative supplier for the EUV lithography machines needed to produce the world’s most advanced chips.
And as nodes shrink and the industry pushes further down the Moore’s Law curve, machine intensity per wafer increases, meaning every dollar of advanced-node capacity requires more ASML tooling than the previous generation. That’s a structurally favorable backdrop most companies could only dream of, and it’s precisely the inflection now showing up in ASML’s numbers and management’s commentary.
ASML’s Q2 results blew past its own guidance and Wall Street’s forecast, allowing management to significantly raise 2026 guidance and provide hugely positive commentary for 2027 and 2028, confirming that I was far too cautious with my estimates before – Q2 confirmed ASML is still one of the highest-quality businesses globally, one of the most reliable ways to play the AI revolution and the compute infrastructure boom, and the best is yet to come.
So, let’s break down the numbers and developments before updating my financial model and thesis
This is a paid-exclusive analysis. Want full access? Consider upgrading to InvestInsights PRO for $9.50 a month or $95 a year! This gets you:
6–8 Research Reports per month, 2x more than free subs do, including 3-4 Deep Dives and 2 mid-week analyses (that comes down to just $1 per analysis)
Full visibility into my personal portfolio, including allocations, transactions, and conviction levels
An overview of target prices and ratings, updated weekly
InvestInsights Premium is designed to help you find best-in-class compounders, identify deep-value opportunities, avoid costly mistakes, and stay focused on fundamentals when markets get noisy, with full transparency into how I make decisions over time.
Q2 Financial & Performance Review
Let’s just jump straight into the numbers!
ASML reported total Q2 revenue of €9.3 billion, exceeding guidance by a good margin (€8.4-€9 billion) and comfortably clearing the €8.8 billion consensus. Moreover, this reflects 21% YoY growth, a continued acceleration from recent quarters, driven by sustained, better-than-expected momentum in its upgrade business and systems revenue accelerating.
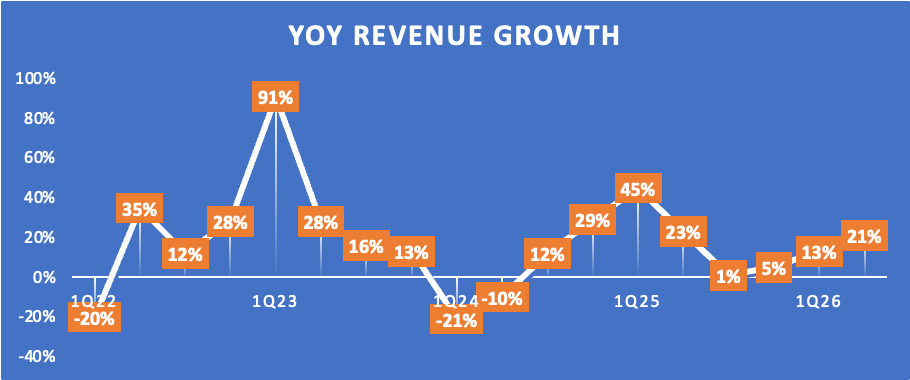
Breaking it down, the number of new systems shipped in the quarter was up 28% YoY, driving systems revenue up 17% YoY to €6.6 billion (71% of revenue), including €3.8 billion from EUV and €2.8 billion in non-EUV revenue.
Notably, systems revenue was almost evenly split between Logic at 51% and Memory at 49%, a big shift from last year, when Memory was just 31% of system sales in the same quarter, reflecting a huge improvement in demand from memory customers. Given the huge DRAM and HBM shortage right now, Micron, SK Hynix, and Samsung are investing rapidly, and these growing CapEx budgets flow directly to ASML – take the nearly €8 billion EUV order from SK Hynix, disclosed in its IPO papers – hence the big jump in Memory.
Now, systems revenue growth might still seem moderate compared to peers and considering the sheer demand out there, but it is worth understanding that ASML’s current growth is held back not only by its production capacity but more so by a lack of cleanroom space at its customers. You see, these machines don’t just get plugged in anywhere; they need highly specialized, ultra-clean, vibration-controlled cleanroom facilities to operate, and building that kind of space takes years and billions of dollars. Right now, TSMC, Samsung, Intel, and the memory players are all racing to expand fabs at once, which means cleanroom capacity itself has become the scarce resource.
In practice, that means ASML could have machines ready to ship, but customers may not have anywhere to install them until their own construction catches up, so ASML can’t realize any of this business. Hence, growth is ramping up, but gradually. This is also why ASML will see better growth in 2027-2029, with much more cleanroom capacity coming online, allowing it to ship significantly more EUV and DUV equipment.
The positive is that shipments are currently ramping in line with expectations.
Meanwhile, ASML also shipped another High NA system in Q2, its most advanced, most expensive system, and confirmed that Intel is using this newest technology on the Intel 18A process node to produce its Intel® Core™ Ultra Series 3 processors.
This is especially important, as TSMC is reportedly holding off on buying ASML’s High NA systems due to the high price tag and may instead find more value in triple patterning with Low NA tools at a lower cost, which led to some concern. However, I would argue this “fear” is well overblown. As with every generation, it takes time for the technology to reach maturity and become cost-accretive, and management is upfront that High NA isn’t there yet for high-volume manufacturing.
This is why Intel’s active use and adoption are huge, showing a willingness to integrate the technology and accelerate the path to maturity. Ultimately, High NA EUV increases resolution enough to pattern the finest features in a single exposure, where today’s Low NA machines often need multi-patterning or several exposure and etch steps just to draw one layer. Fewer steps mean less cycle time, less tool usage per wafer, and higher yield. So even though a High NA machine itself costs more upfront, it should lower the effective cost per patterned layer by collapsing what used to take multiple expensive steps into one.
In other words, TSMC holding off right now isn’t a huge surprise; it means nothing for the long-term viability of the system or the justification of the price tag. Customers are simply looking for the best balance between time to integrate and price, meaning High NA adoption will likely take a little longer. But it is the future, nonetheless.
Looking at the regional split of systems revenue, China accounted for 14% of Q2 revenue, down from 19% in Q1 and 27% in the same quarter last year, which is a big improvement from a risk perspective, with less of ASML’s revenue at risk from potential new export restrictions imposed by the U.S.
For the year, ASML still expects China to make up roughly 20% of total sales, significantly down from recent years.
Besides system sales, ASML generated roughly €2.8 billion in installed base revenue (29% of revenue), which was nearly €300 million above guidance and up 32% YoY, driven by better-than-expected traction in the upgrade business.
As I explained last quarter, the key is that customers can’t simply order an EUV system today and have it delivered tomorrow. ASML has a backlog exceeding €40 billion and a roughly 2-year waitlist, and there is also the lack of cleanroom space, which is even more important today. So, while customers desperately want to add capacity today to meet exploding demand, a new system will take several years to be delivered on location and become operational.
The solution is the much faster and cheaper option of upgrading old systems, as ASML continues to develop these and offers upgrade packages. With that, customers can expand capacity in the short term by using existing equipment while they wait for next-gen machines to arrive. For example, it has increased the throughput of its NXE:3800E from 220 to 230 wafers per hour and its NXE:3800F from 250 to 260 wafers per hour, which are small but very valuable upgrades for customers desperately seeking capacity.
This is where ASML is seeing sensational demand right now, far better than expected, and as long as demand remains this strong and shortages persist, we can expect the upgrade business to keep firing on all cylinders.
This combination of sustained impressive momentum in the upgrade business and accelerating growth in system sales is what drove a very strong Q1 top-line result for ASML, coming in far better than expected.
On that note, let’s move to the bottom line, where ASML delivered a similarly strong performance.
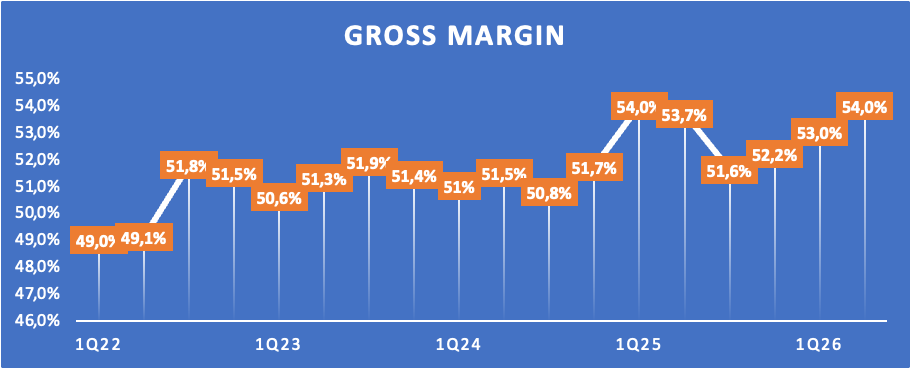
The Q2 gross margin came in at 54%, up 30 bps YoY, driven by a positive revenue mix, with EUV systems and installed base revenue carrying higher margins. This drove the gross profit up 22% YoY to €5 billion.
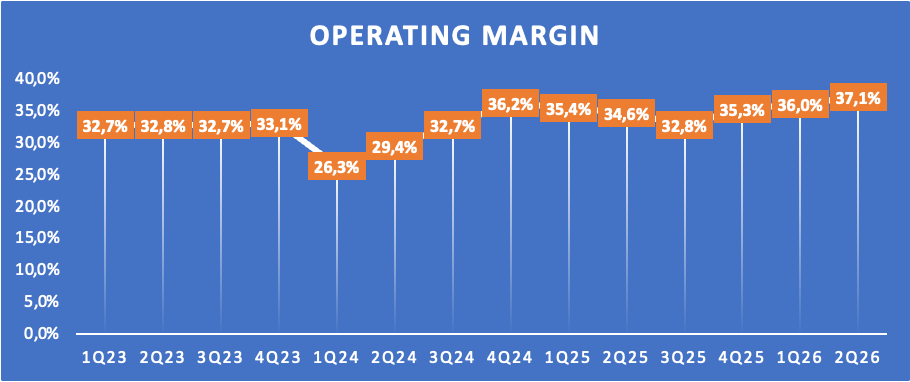
Moving further down the line, ASML delivered very strong operating leverage, despite OpEx ahead of guidance. Nonetheless, OpEx was up just 6% YoY, with R&D up 9% and G&A up 1%, growing significantly more slowly than revenue.
As a result, the operating margin hit a new high of 37.1%, up 250 bps YoY. And management indicated this momentum will likely persist. The company invested a lot in recent years, strongly growing its headcount. Those investments now position it well to grow within current capacity, allowing for continued low OpEx growth and, with the top line likely accelerating, I expect ASML to keep delivering very strong operating leverage in the coming years.
The strong Q2 operating leverage led to a similarly strong net profit of €2.9 billion, reflecting a 31.3% net income margin, up 250 bps YoY. This translates to an EPS of €7.59, up 29% YoY, also reflecting a lower share count.
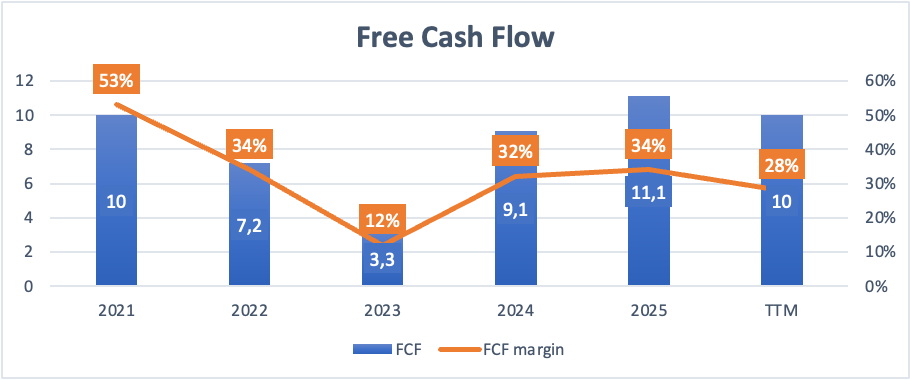
Finally, Q2 FCF was €1.3 billion, a significant improvement from €300 million last year. However, it is worth noting that the timing of FCF realization fluctuates significantly for ASML, generally leaning toward Q4, making TTM numbers more representative. Positively, ASML’s TTM FCF now totals €10 billion, reflecting a 28% FCF margin. That is down slightly from 2024 and 2025 due to a higher Q1 outflow, but I expect this to be more than offset in Q3 and Q4, with 2026 FCF likely to exceed €12 billion and reach a 35% FCF margin, which is excellent.
After returning cash to shareholders through a dividend and €1.1 billion in buybacks in Q2, ASML ended the quarter with a healthy balance sheet, holding €7.6 billion in cash and just €2 billion in debt, down from €4.7 billion at the start of the year, leaving ASML with a very neat €5.6 billion in net cash. Especially considering its cash flows, ASML is in pristine financial health, with loads of firepower.
On a final note, ASML’s reinvestment metrics remain sublime. Its TTM ROIC sits at 52% and ROE at 54%.
Overall, I will once again say that ASML delivered a brilliant Q2 result, delivering numbers well ahead of expectations. I honestly don’t think it could have done much better.
Then, on to the section that matters most to investors – the outlook.
Summer Discount - 25% OFF
Not a paid subscriber yet? This is your chance to upgrade. The InvestInsights Summer Sale runs through early tomorrow — only 20 hours left — a rare chance to get your first year for 25% less.
That means you pay just $72 for your first year if you sign up today — that's less than $0.70 per analysis. And you get immediate access to the remainder of this ASML analysis. So, what are you waiting for?
Outlook & Valuation
Following the excellent first half of the year and the demand trajectory management is seeing in both its systems and installed base business, management significantly raised its 2026 guidance.
