

ASML released its third-quarter results earlier today (October 15) and managed to please investors, beating the earnings consensus, reporting a healthy order intake, issuing decent Q4 guidance, and setting a floor for 2026, ruling out negative growth (improved from some prior uncertainty). At the same time, revenue matched guidance but fell short of consensus estimates, and management remained extremely cautious on 2026 amid rapidly declining Chinese demand.
Nevertheless, investors were optimistic about the results, with the ASML share price rising roughly 3% when European markets opened, despite shares already having re-priced since early September, gaining almost 40% based on a pre-earnings share price, pricing in a lot of optimism for the years ahead.
Meanwhile, I must admit I was somewhat disappointed by the results (revenue was light, and orders fell short of my expectations) and the management commentary, which was nowhere near as optimistic as I had hoped, with management remaining extremely cautious.
You see, the underlying conditions for ASML have improved meaningfully in recent months. This has been the main driver behind the stock’s sharp rally over the past six weeks, and with it, rising investor expectations.
Several factors contributed to this optimism:
Massive cloud and AI infrastructure deals: Companies such as OpenAI, AMD, Oracle, Microsoft, Google, and Broadcom have announced large-scale partnerships. These deals underscore one thing clearly: there’s no slowdown in AI momentum. As a result, the demand for advanced semiconductors is proving both strong and durable, likely extending well into the next decade if these investments materialize as planned.
As a result, chip manufacturers such as Samsung, Intel, and TSMC will need to continue expanding capacity to meet this demand. For ASML, that translates into higher CapEx budgets from its largest customers and a stronger long-term demand outlook. With its unique EUV lithography monopoly, ASML remains an essential enabler of advanced semiconductor production. Simply put, it’s hard to see how ASML doesn’t benefit from this sustained, broad-based demand wave, both in the near term and over the long run. These assumptions already existed, but recent deals confirm momentum is real.
Resilient U.S. economy: Earlier fears of a global slowdown, driven by potential weakness in the U.S., have eased. The U.S. has held up far better than expected, improving visibility and confidence in ASML’s 2026 outlook and removing a potential drag.
Intel’s renewed support: Intel, one of ASML’s key customers, is receiving significant backing from the U.S. government, SoftBank, and Nvidia to expand its semiconductor manufacturing capacity. This support bodes well for ASML, as it ensures continued investment in leading-edge lithography equipment.
Yet, management’s commentary didn’t entirely reflect these improving conditions, which I found disappointing. The tone came across as overly cautious, especially given how much the broader environment around AI, semiconductor CapEx, and economic resilience has strengthened in recent months.
Still, I’ve been bullish on ASML for a long time, and this quarter hasn’t changed that. If anything, the recent developments in AI infrastructure spending and continued support for leading chipmakers reinforce the foundation of my long-term thesis.
ASML remains the most important company in the semiconductor supply chain. Its EUV and High-NA EUV systems are not just cutting-edge tools; they’re gatekeepers to technological progress. No other company can produce them, and every leading chip manufacturer depends on ASML to advance their most sophisticated nodes. This gives ASML both unmatched pricing power and long-term visibility that very few other businesses enjoy.
While near-term volatility and cautious guidance may frustrate investors, the long-term picture remains exceptionally strong. The structural demand for computing power, driven by AI, data centers, and advanced logic chips, continues to expand. Over the next decade, that demand should translate into sustained growth for ASML, both in system sales and the increasingly profitable service and upgrade business.
So despite management’s conservative tone this quarter, my conviction in ASML’s long-term outlook remains firmly intact.
On that note, let’s go over all the quarterly numbers and management’s commentary in greater detail to put things into perspective and make up the balance with updated financial estimates and an updated target price!
Welcome to InvestInsights — an independent equity research publication rooted in long-term, buy-and-hold investing, publishing actionable stock/equity research reports weekly!
📈 You’re reading my latest [FREE] stock analysis. If you like this analysis, make sure to like & subscribe to receive much more like this!
If you’d like full portfolio access (14% CAGR since 2022) & additional exclusive reports, consider becoming a paid subscriber!
ASML Q3 sales fall short
Expectations for ASML’s Q3 quarter weren’t low, after plenty of analysts lifted their expectations in recent weeks amid growing optimism around its strong operating environment. As a result of this and ASML’s history of guiding conservatively, consensus estimates aimed for Q3 revenue at the high end of management’s guided range, but this is where ASML fell short.
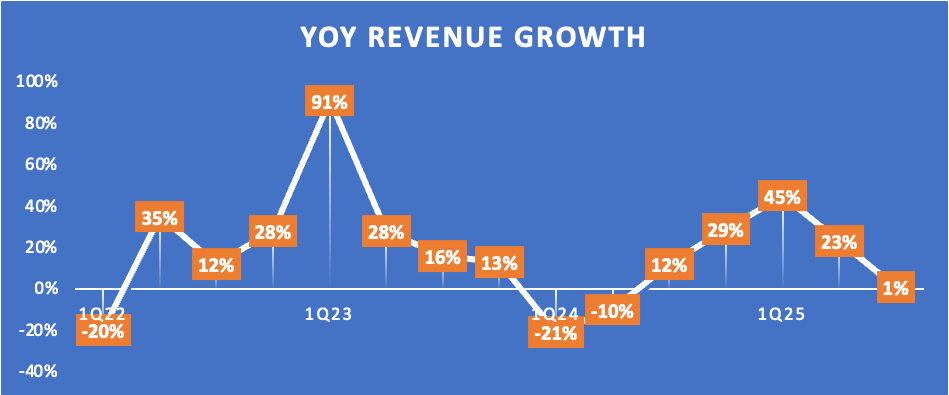
The company reported Q3 revenue of €7.5 billion, which fell at the lower end of its guided range (€7.4 billion to €7.9 billion) and below the Wall Street consensus of €7.8 billion. Furthermore, this reflects YoY growth of just 1%, driven by far fewer system sales compared to last year (new systems shipped were down 38% YoY), offset by a higher average selling price.
Positively strong growth in installed base (service) revenue was robust in Q3, similar to what we have seen in H1, rising 27% YoY to €2 billion. Management didn’t provide any further commentary on this, but I expect growth here to continue to be primarily driven by upgrade revenues, similar to H1.
To give you some background, this segment is strategically vital for ASML. The installed base business provides high-margin, recurring revenue that helps stabilize results during periods of weaker system demand. Over time, as ASML’s global footprint of EUV and DUV tools continues to grow, so too will the share of these predictable service revenues in the company’s overall mix.
We should note that the upgrade revenues currently fueling this growth are not recurring but tend to follow specific upgrade cycles. As those cycles mature, I expect installed base revenue growth to normalize toward a more sustainable low- to mid-teens rate. That will be driven primarily by the expanding number of systems in the field, each requiring ongoing service, maintenance, and performance optimization.
In essence, while the current growth pace may cool somewhat, the long-term trajectory remains highly attractive. The installed base business deepens ASML’s relationships with leading chipmakers, strengthens switching costs, and reinforces the company’s dominant position in the semiconductor value chain.
Moving back to the Q3 results, let’s take a look at the regional split. What really stands out immediately is the outsized exposure to China in Q3 at 42%, which is up considerably from Q2 (27%). The reason for this is likely some pulled-forward demand, ASML working through Chinese DUV orders to avoid any impact from potential additional export bans, and Q3 historically being more China-heavy.
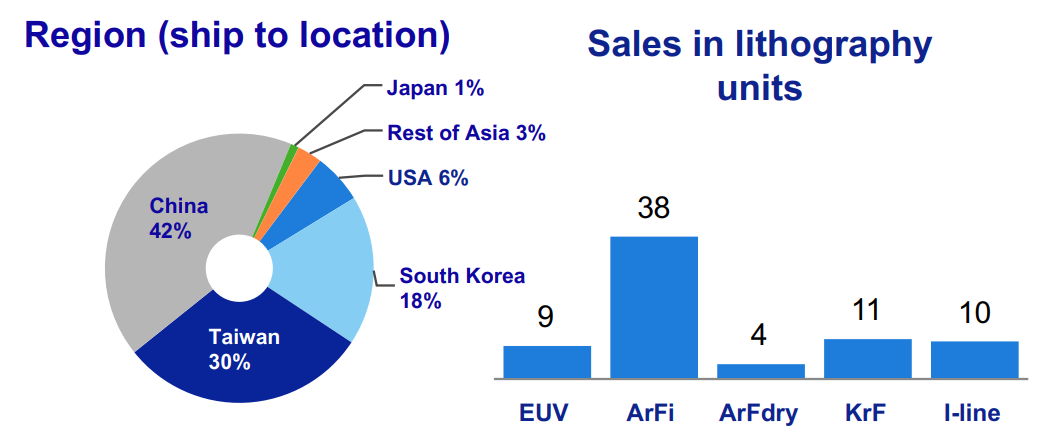
At the same time, Chinese exposure was still down from 47% in the same quarter last year, reflecting a decline in China exposure. We should expect this decline to continue in the coming quarters, with exposure to China likely normalizing in 2026 after some elevated years, and falling below 20% on a full-year basis. Moreover, I expect exposure to China to decline in the years ahead due to additional export bans on semiconductor equipment and China’s efforts to develop domestic alternatives. By the end of the decade, I would be surprised if this still accounted for more than 10% of total annual sales.
While likely a drag on growth in 2026 and 2027, this falling exposure will be a long-term positive, reducing geopolitical risk.
Apart from China, South Korea (18%) and Taiwan (30%) remain ASML’s largest regions in terms of sales as of Q3, driven by continued investments from large customers such as TSMC, SK Hynix, and Samsung.
The Q3 order intake was healthy.
Moving to order intake, this is often the key metric investors focus on to gauge quarterly performance. Ultimately, orders act as a leading indicator of future revenue and demand visibility. Because ASML’s systems have long production lead times, order trends reveal how confident chipmakers like TSMC, Intel, and Samsung are in expanding capacity.
Strong order intake signals ongoing investment and healthy end-demand, while weaker bookings can suggest caution or delays in semiconductor CapEx. That’s why this figure often drives investor sentiment more than reported revenue, as it tells us where ASML’s growth is heading next.
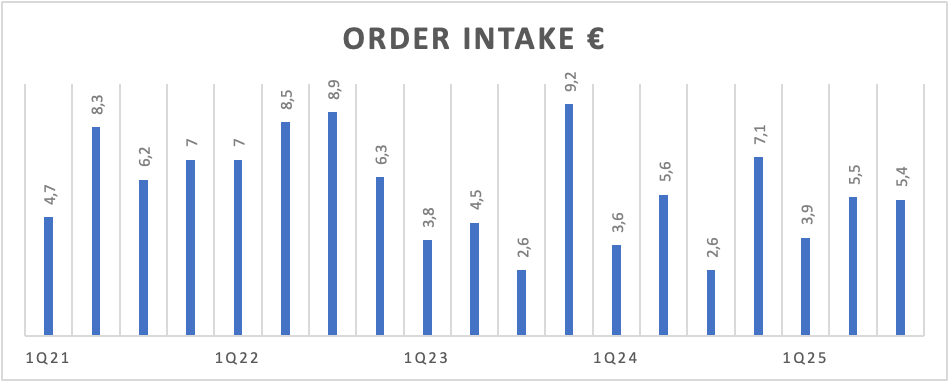
Positively, ASML performed well in Q3. The company reported total order intake of €5.4 billion, which is excellent, well ahead of last year’s €2.6 billion, and in line with last quarter’s €5.4 billion. Also, this was ahead of the €5.1 billion consensus.
When we break down this order intake a bit further, it shows a clear and promising trend that signals confidence from ASML’s most important customers. You see, in Q3, EUV orders totaled €3.6 billion or 67% of the order backlog. For reference, EUV sales in the same quarter last year were €1.4 billion (54% of orders) and €2.3 billion in Q2 (42%).
So, we are seeing a considerably bigger contribution from EUV than we have seen over the last few years, reflecting that Chinese orders (consisting of just DUV due to export bans) are down and that high-end EUV orders, which are required in the manufacturing of advanced nodes and bought only by ASML’s biggest and most important customers (due to price), are seeing improved demand, confirming the growing push toward advanced node manufacturing expansion, offset by weakening demand from China.
Most importantly, this suggests growing investments by the likes of Micron, TSMC, Samsung, and Intel, which is a promising indicator. I expect both of these trends to ramp in the coming quarters, leading to healthy net order growth.
Additionally, Q3 orders were now almost evenly split between logic and memory, showing a big bounce-back in investments from memory clients, reflecting significant investments in new technologies and capacity expansion by Micron, Samsung, and others.
Ultimately, I quite liked the quality of this order intake, even if the actual number fell short of my expectations.
The bottom-line results impressed
On the bottom line, ASML performed quite well, with improved operating leverage.
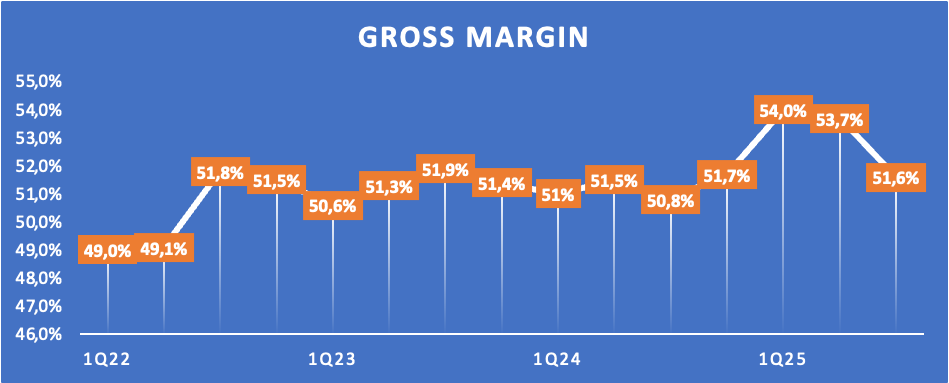
The company reported a gross margin of 51.6%, which sat at the higher end of the guided range (50% to 52%) and above a 51.4% consensus. This was up 80 bps YoY, despite some tariff headwinds and the negative impact of the ramp in High-NA EUV.
Further down the line, ASML reported an operating margin of 32.8%, up 10 bps YoY. This was supported by growth in R&D expenses of only 5% and SG&A costs roughly flat. As a percentage of sales, R&D sat at 15% (up 90 bps YoY) and SG&A at only 4% (flat YoY).
Furthermore, net income was up 2% YoY to €2.1, driven by a 50 bps increase in the net income margin to 28.3%. As a result, EPS was €5.49, up 4% YoY. The difference between net income and EPS growth was driven by a lower share count resulting from management repurchasing its own shares.
As of the end of Q3, ASML has repurchased €5.9 billion worth of shares in 2025 under its €12 billion repurchase program, which ASML doesn’t expect to complete in 2025 alone. However, ASML remains committed to returning cash to shareholders, with €6.1 billion remaining under its current program and plans to announce a new program in January 2026.
In terms of capital return, ASML shares also still pay a 0.8% dividend, based on a 15% payout ratio. Additionally, ASML has increased this dividend at a 5-year CAGR of 22% and has raised it for nine consecutive years. Long story short, ASML is still a compelling dividend growth pick, with management remaining committed to rewarding shareholders with its excess cash.
In terms of financial health, ASML also still looks excellent, holding €5.1 billion in available cash on the balance sheet and just €3.9 billion in debt. Its cash balance declined further in Q3, reflecting the timing of expenses and revenue recognition, but these are normal fluctuations. You see, ASML’s FCF tends to be lumpy from quarter to quarter, with the far majority realized in Q4 due to the timing of revenue realization and expenses. As a result, its cash balance should bounce back in Q4.
The Mistral AI stake
Before we get to the outlook, a quick note on its stake in Mistral AI. In early September, ASML disclosed that it had taken a €1.3 billion stake in French AI company Mistral, making it its largest shareholder. For reference, Mistral is one of Europe’s most notable and valuable AI names, valued at roughly €10 billion.
Management emphasized that Mistral is recognized for both its business-to-business focus and the high quality of its large language models, particularly in software coding and development.
You see, this is not a simple investment to put cash to work; this is strategic first.
While ASML is best known for its hardware, this partnership highlights the company’s growing reliance on advanced software to enhance precision, speed, and performance across its lithography, metrology, and inspection systems. At the extreme levels of accuracy ASML operates, software integration and AI-driven optimization are becoming just as critical as the hardware itself. The collaboration with Mistral aims to accelerate both product innovation and development speed, improving time-to-market for next-generation tools.
In other words, ASML isn’t investing in AI for hype or headlines; it’s doing so to strengthen its technological moat. Partnering with Mistral allows ASML to embed cutting-edge AI directly into its tools and development processes, reinforcing its lead in precision manufacturing and ensuring it stays ahead of both technological and competitive curves.
For ASML, this is quite an aggressive move, and I like it. It’s a compelling strategic move. The only negative I see is that Mistral is quite far below its U.S. peers in general AI and LLM quality. However, it is reportedly competitive in domains such as code, reasoning, and constrained inference, making it a good strategic fit, nonetheless.
On that note, let’s discuss the outlook!
Want more out of your subscription? Even more content like this weekly?
Consider InvestInsights PRO - $7.50/month ($70/annually)
This gets you:
A guaranteed 6+ stock analyses every month (roughly 2-4 paid-exclusive).
Full insight into my own portfolio (14% return CAGR since 2022).
Instant transaction alerts anytime I make a move (Fully transparent).
A complete overview of all my target prices and ratings (online available).
You will get immediate access to these recent analyses of Netflix, American Express, PayPal, Uber, and Meta!
Outlook & Valuation
When asked about their view of the operating environment, management was generally positive, indicating that recent developments have reduced some uncertainties. Management continues to see healthy demand dynamics, with substantial investments in both logic and DRAM, and AI momentum holding up. At the same time, ASML sees Chinese demand weaken considerably, as already highlighted by new orders, leading to expectations of significantly lower Chinese sales in 2026 compared to the elevated demand in 2024 and 2025.
In part, driven by the latter headwind, ASML management remained extremely cautious in its guidance commentary in the prepared remarks, especially regarding 2026. Yes, management in some way raised its guidance and optimism, now ruling out a sales decline in 2026, whereas it was still uncertain previously. Still, management isn’t guiding for real growth either, seemingly lacking some confidence, which I think is rooted chiefly in extreme caution amid somewhat poor visibility and a lot of global uncertainties, geopolitical and macroeconomic.
Ultimately, there is no going around the fact that this is disappointing, at least to me. Especially amid the recent run-up in shares and the improving operating dynamics, I had expected more optimistic commentary.
At the same time, I remain confident that management is downplaying 2026. Dynamics are strong. I expect positive CapEx commentary from TSMC tomorrow, with peers following suit. With AI demand holding up well, I see no way TSMC and peers won’t further raise CapEx in 2026 and heavily invest in global manufacturing capacity, which should benefit ASML.
I will add that 2026 could very much see “weaker” growth, with this ramping up more aggressively in 2027 and 2028, based on the current expansion and technology roadmaps of TSMC, Samsung, Micron, and Intel. So, combining this with a significant decline in China sales, I see where management’s caution comes from; it’s just well overdone.
Moving to short-term guidance, management now expects Q4 revenue between €9.2 billion and €9.8 billion, suggesting YoY growth of 2% YoY at the midpoint. Furthermore, management expects the gross margin to be roughly flat YoY, between 51% and 53%, which is still very strong given the headwinds.
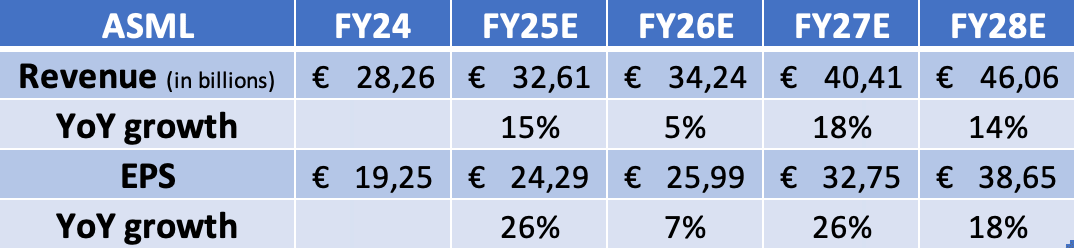
For FY25, this should translate into total revenue of €32.5 billion, up 15% YoY, and a gross margin of around 52%.
Long-term, management remains optimistic. AI demand should remain very strong through 2030, and as the focus increasingly shifts to advanced nodes, lithography intensity should grow strongly as well, benefiting ASML. As a result, the outlook for ASML remains strong, and management maintains its 2030 guidance of revenue between €44 billion and €60 billion and a gross margin of 56% to 60%.
Supporting this is also the strong adoption of ASML’s latest High-NA EUV technology, which is off to a good start, and ASML's move into advanced packaging, with the first equipment released in Q3. 3D integration is becoming increasingly essential to support Moore’s law, and ASML is playing right into this shift, entering the market with its XT:260 advanced packaging machine. Considering ASML’s strong history of innovation and its strong relationship with customers, we could see a strong ramp-up in advanced packaging revenues over time, adding to an already excellent outlook.
So, for my own projections, I am now assuming the midpoint of management’s guided range for Q4 and, subsequently, 2025. This means I am slightly trimming my FY25 revenue estimate. At the same time, I expect margins to hold up well, with improved operating leverage driving faster EPS growth to 26%, up slightly from before.
As for 2026, I expect strong ex-China demand to offset the drop in Chinese demand, as CapEx budgets should grow strongly. Therefore, I now project revenue growth of 5% YoY, down slightly from a prior estimate, and translating into 2026 revenue of €34.24 billion. This slower growth, in combination with continued cost headwinds, should limit margin expansion, leading to minimal EPS growth of 7%, in my projections.
Looking even further ahead, I remain very optimistic. As China-related headwinds ease in 2027 and 2028, and more fabs come online globally due to recent investments, I expect ASML to deliver robust revenue growth in the mid-to-high teens. Meanwhile, this stronger revenue growth should allow margins to expand further, driving much better EPS growth.
All my assumptions are reflected in the outlook below.
When it comes to valuation, the rapid run-up in ASML’s share price since early September, combined with an outlook that has actually been trimmed slightly, means ASML shares haven’t gotten any cheaper. Based on the current share price of €887, we are looking at the following multiples:
36x this year’s earnings and 34x next year’s earnings.
A growth-adjusted PEG of 2.1x
Considering we were looking at 26 times earnings and a PEG of 1.3 times back in July, it is safe to say ASML shares have become much more expensive. Shares have fully repriced in recent weeks, and arguably rightfully so. ASML is still one of the highest-quality businesses globally, with an undisputed moat and an extremely promising outlook, serving as a critical enabler of next-gen technologies, including AI. Additionally, the company is in excellent financial health and should experience substantial improvements in operating leverage in the coming years.
This is a one-of-a-kind business and rightfully one of my largest positions.
Furthermore, its operating backdrop is improving, as noted in today’s post’s introduction, so a repricing was inevitable. However, this means ASML is no longer a no-brainer. In fact, it might be a good time to lock in some profits.
You see, ASML still has a massively promising outlook that should stretch well into the next decade, at the very least, but with 2026 likely to be a year of lesser growth due to a loss of Chinese revenues and the realization of current investments from ASML clients taking some time to be reflected in ASML results (apart from orders, which will ramp earlier), its next 15 months will be far less impressive.
Having to then pay 36x earnings is demanding, which will limit investor upside over the next 12 months at current prices, even in a more optimistic scenario.
For reference, even if we assume a 34x 2027 exit multiple, which is about the most I would be willing to pay, I calculate an end-of-2027 target price of €1,113. From a current share price of €887, this translates into potential annualized returns of just over 11% (including dividends).
Personally, I don’t quite like that risk-reward. While there is definitely upside to my current estimates, which could justify the current price, there is too much uncertainty and too little visibility. In a base case scenario, there isn’t enough downside protection.
Therefore, I am on the sidelines. I even took some profits in recent weeks at around current levels.
However, I would be happy to buy again at more compelling prices. Given current estimates and conditions, I am looking for a share price below €800 to pick up some shares again, down about 10% from current levels.
Rating: Hold - Accumulate below €800
FY27 Target Price: €1,113
Implied CAGR from the current price: ~11%
Please leave a like if you enjoyed this post and found it valuable!

Good analysis! Fully agree with the your overall sentiment.
With regards to management being cautious. I honestly cannot remember ASML being ''incautious''. They have always had a tendency to under promise, and usually, overdeliver.
It does also make sense to be cautious, cause investor and analyst take things out of context very quickly. Since their bookings are so lumpy, it's super hard to make concrete projections, and therefore they refrain completely from it.
Also, I think very important, why they don't follow the AI/Datacenter capex spend hype, yet: it might take months/years for this capex spend to reach ASML. Extremely hard to predict. I understand a more cautious stance there.