

Booking Holdings continues to stand out as one of the most impressive — and arguably most underappreciated — businesses in global markets today.
The travel accommodation powerhouse behind Booking.com, Priceline, Agoda, Kayak, and OpenTable (among others) is still viewed by many as a cyclical travel stock. Yet, it has quietly evolved into a structurally advantaged, high-margin compounding machine, a true powerhouse in the travel industry with an underappreciated but increasingly deep and entrenched moat, built on scale, network effects, and brand power. Today, it has a global marketplace with unmatched supply depth, direct user loyalty, and data-driven efficiency that competitors simply can’t replicate.
As a result, despite its massive scale, Booking continues to outgrow its peers, such as Airbnb and Expedia, steadily expanding its moat, improving profitability, and gaining market share in every major region thanks to a structurally advantaged platform and competitive position.
No, Booking is not getting disrupted by Airbnb in the slightest. Instead, it continues to gain market share.
And that is not all, as it also comes with brilliant financials. Booking continues to grow its revenue at a low-to-mid-teens rate, has improved its EBITDA margin sequentially in every single quarter over the last three years, and it now generates over $8 billion in FCF annually at a 38% FCF margin.
Even more impressive, nearly all of this cash is returned to shareholders. Over the last two years alone, Booking has retired an astonishing 21% of its outstanding shares and introduced a dividend, adding to its appeal.
Ultimately, it’s a dominant, highly profitable compounder that continues to strengthen its lead and remains brilliantly positioned for sustained growth in the decade ahead – the latest quarter once again reinforces that story.
Booking released its Q3 results last week and once again impressed, blowing past consensus estimates and delivering financial results that exceeded the high end of guidance on every single metric, as business momentum remains sublime and the company continues to win share.
Additionally, Booking continues to report excellent progress on its strategic priorities, as confirmed by strong operational numbers, which strengthen my confidence in its long-term ability to sustain growth, expand its moat, and enhance its competitive position.
Today, I would like to provide an update on my Booking Holdings thesis by reviewing the Q3 results in detail, going over the reported numbers, performance, and underlying developments, before updating my financial projections and fair value estimate.
Let’s delve right in!
Welcome to InvestInsights — an independent equity research publication rooted in long-term, buy-and-hold investing, publishing actionable stock/equity research reports weekly!
📈 You’re reading my latest [FREE] stock analysis. If you like this analysis, make sure to like & subscribe to receive much more like this!
If you’d like full portfolio access (16% CAGR since 2022) & additional exclusive analyses, consider becoming a paid subscriber!
Booking delivers another brilliant quarter
On October 28, Booking released its third-quarter results, and it delivered.
The company reported another quarter of double-digit growth in gross bookings and revenue, reflecting robust demand across all regions. Meanwhile, it continues to expand margins, delivering leverage across its P&L, and generates heaps of operating cash flows.
Most impressive of all, the company continues to far outperform Wall Street estimates, surpassing the consensus on nearly every metric for almost three consecutive years now, quarter after quarter – Wall Street simply continues to underestimate its sheer dominance, which I have been hammering for years now (yes, I am a happy shareholder).
Anyway, let’s delve into the results, starting at the top!
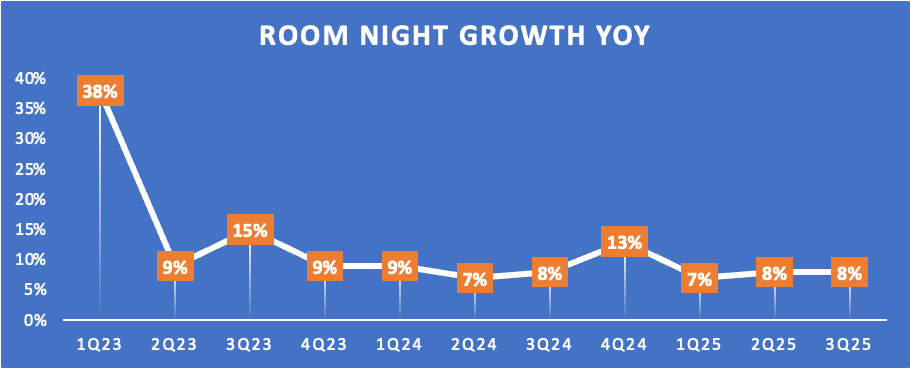
Booking reported Q3 room nights booked of 323 million, up 8% YoY and exceeding the high-end of guidance by a whopping 3 percentage points, driven by the expansion of its booking window compared to expectations, resulting in some nights pulled forward into the third quarter.
This growth is stable compared to most of the last two years, which is especially impressive considering its huge and growing base. Despite its massive size, Booking maintains growth momentum, driven by healthy demand across all major regions, with each exceeding expectations in Q3.
In part, the stability of this growth can be attributed to Booking’s brilliant geographical exposure. While peers Airbnb and Expedia heavily rely on the U.S., Booking has excellent global diversification, with a bigger presence in Europe and Asia. As a result, the company is much less reliant on one single economy and less impacted if any region faces headwinds.
For reference, last quarter, strong growth in Canada to Mexico and Europe to Asia offset weaker demand for inbound U.S. travel.
Looking at Q3 regional performance, Asia and RoW each delivered low double-digit growth, while Europe and the U.S. were up high single digits.
Especially the U.S. performance was notable, as Booking saw growth accelerate at a healthy pace, supported by stronger outbound travel and momentum in B2B demand. Furthermore, management believes it outperformed the broader U.S. market “in a meaningful way,” suggesting some market share gains in one of its less prominent and more competitive markets, which is a promising signal. At the same time, Booking did point to some continued caution from the U.S. consumers, as reflected in lower ADRs and a shorter length of stay YoY.
Globally, both of these indicators were stable YoY.
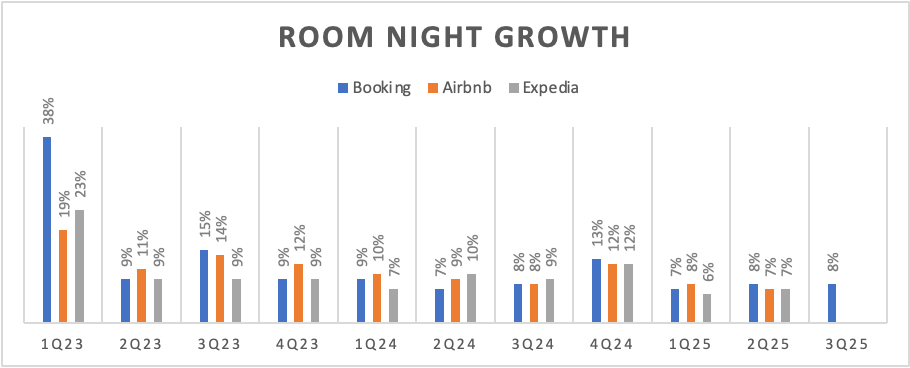
When considering room nights, it is also interesting to monitor how Booking compares to its closest peers, as room nights are the best indicator of performance. Although these peers haven’t reported their Q3 numbers yet, the results over the last three years tell an essential story: Booking isn’t losing any market share; it continues to gain.
As shown in the graph below, since Q1 2023, Booking’s growth has been competitive compared to its peers.
Airbnb has outgrown Booking in only 5 out of 10 quarters.
Booking has outperformed Expedia in 8 out of 10 quarters.
And yes, especially compared to Airbnb, it might not look that impressive; in most quarters, growth rates sit close together. However, let’s not overlook that Booking is more than twice the size of Airbnb and three times the size of Expedia in terms of night volume. In other words, Booking delivers similar growth from a much larger base, meaning that in actual nights booked, Booking is growing much faster and still gaining market share, which is truly impressive.
Moving then to the financial results, it is worth pointing out that Booking continues to benefit from FX headwinds, which have contributed to growth by 400 to 500 basis points (FX doesn’t affect room nights, but it does impact financial results).
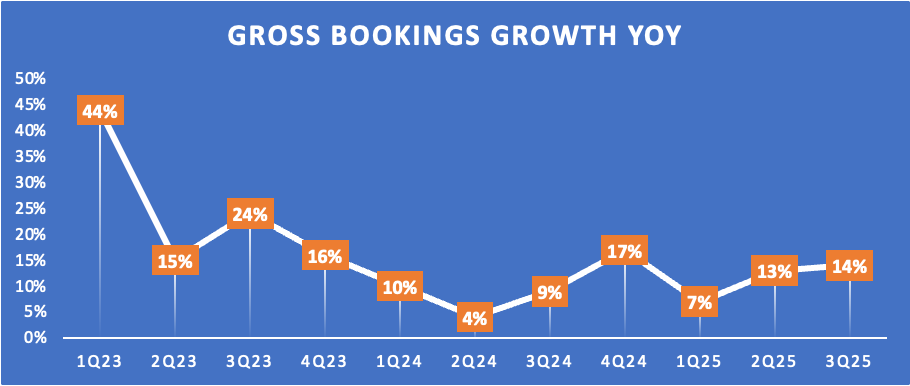
Getting to the results, Booking reported robust gross bookings growth in Q3 of 14% YoY to $50 billion (10% FX-neutral), exceeding the high-end of guidance by 4 percentage points, driven by better-than-expected room nights. The 2 percentage point faster growth compared to room nights was the result of faster growth in flight bookings and higher accommodation prices.
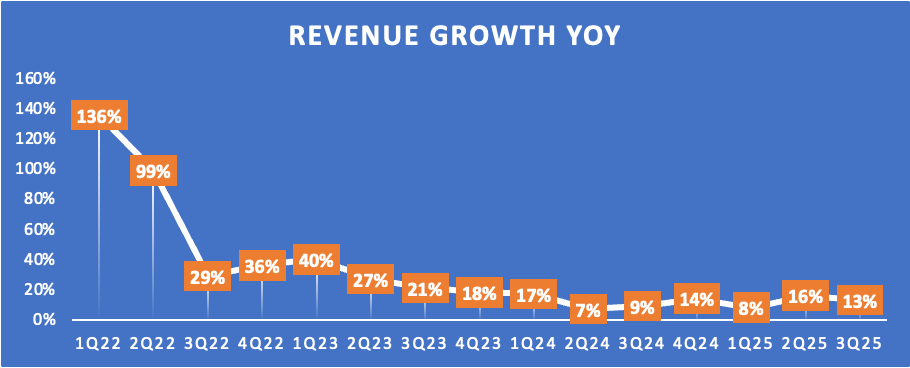
Revenue growth was similarly strong and impressive, with revenue growing 13% YoY to $9 billion (8% FX-neutral), exceeding consensus estimates by $270 million and the high-end of guidance by roughly 400 bps, which is exceptional!
The revenue take rate did drop 30 bps YoY to 18.1%, which explains why revenue growth came in slightly below gross bookings. This decline was driven by an increase in flight bookings, which carry lower margins.
Most importantly, the result was strong, nonetheless. Booking continues to maintain an excellent revenue growth rate in the low-teens, which remains remarkable. It continues to outpace the underlying market by a good margin.
In addition to strong financial results, Booking continues to execute its strategic priorities effectively, which reinforces my confidence in Booking’s ability to further strengthen its competitive position, outgrow the market, and maintain its status as the undisputed leader in travel.
You see, the company has several strategic priorities that should drive long-term growth and strengthen its moat, including its connected trip vision, loyalty program, alternative accommodations, Asian expansion, and the integration of AI.
Management is bang on with these strategic priorities, focusing on precisely the right areas. All of these priorities practically concentrate on improving the user booking experience and making its platforms more complete to lock in its users by allowing them to book their entire trip through its own platforms.
Last quarter, Booking once again made tangible progress across each of these initiatives.. Here is a quick quote from management:
“We’re advancing our Connected Trip vision, strengthening our loyalty programs and building AI capabilities that create more value for both travelers and suppliers. Asia and alternative accommodations continue to remain growth drivers. Together, these efforts are reshaping how people plan, book, and experience travel, and how we are unlocking greater value for our partners.”
Let me highlight the two most important ones, starting with the most important of all – its connected trips vision.
Booking continues to make substantial progress toward building a truly seamless, end-to-end travel ecosystem. The idea behind the Connected Trip is simple yet powerful: to enable travelers to plan, book, and manage every aspect of their journey, from flights and accommodations to rental cars, rides, and attractions, all within one integrated platform. By doing so, Booking aims to remove friction from the travel experience while deepening user engagement and capturing more value per customer.
In Q3, this vision advanced meaningfully. Travelers can already book accommodations, flights, rental cars, pre-booked rides, and attractions directly through Booking.com, and the company continues to expand these verticals and improve the user experience. The redesigned home screen now adapts dynamically to each traveler’s most recent search, making it easier to move seamlessly between planning and booking. Meanwhile, flight supply was strengthened further through new partnerships with Ryanair in Europe and Southwest in the U.S., expanding choice and convenience for travelers.
These efforts are paying off. Connected Trip transactions (trips that include more than one travel vertical) grew in the mid-20% range year-over-year in Q3 and now represent a low double-digit percentage of total transactions on Booking.com.
Multiple verticals are growing rapidly, with flight tickets up 32% year-over-year and attraction bookings up nearly 90%, albeit from a smaller base. Importantly, customers who book multi-vertical trips tend to return to the platform more often, reinforcing loyalty and improving long-term monetization.
Ultimately, the Connected Trip is more than just a product initiative; it’s a structural growth driver. By turning Booking.com into a one-stop travel hub, the company not only enhances the traveler experience but also strengthens its competitive moat through higher user retention, cross-selling potential, and data-driven personalization.
Next up is Booking’s Genius loyalty program, which is designed to reward loyal customers with meaningful perks, such as tiered discounts, free breakfasts, or room upgrades, in exchange for greater engagement and repeat business, thereby powering Booking’s moat and keeping users tied to its platform.
For reference, “Genius members book more often, convert at higher rates, book further in advance, cancel less, and choose to come back more consistently than non-Genius customers,” to quote management. In Q3, Genius levels 2 and 3 accounted for 30% of its customer base, but these customers made up for a mid-50% of room nights booked, as these are more engaged, driving up value for Booking.
Additionally, we can also see that these efforts clearly translate into more direct customer relationships. On a TTM basis, a mid-60s percentage of customers now find Booking directly, without the need for promotions or marketing, and this is growing strongly, up from the low-60s one year ago. Similarly, a mid-50% of room nights are now booked through the mobile app, up from a low-50% one year ago. This signals a growing percentage of users find booking without the need for marketing, showing promising progress when it comes to customer loyalty and moat.
Ultimately, these are all promising developments strengthening Booking’s moat and competitive positioning. As I mentioned, these developments bolster my confidence in Booking’s ability to be the long-term winner in travel and in its growth outlook.
On that note, let’s move to the bottom line.
Starting with variable expenses, Booking reported a 9% growth in marketing expenses, leading to healthy leverage, with the largest P&L expense growing at a slower rate than revenue, driven by changes in traffic mix and lower brand marketing expenses, in part driven by the earlier-mentioned larger share of direct traffic. The subsequent decrease in the need for marketing investments leads to constant leverage improvements.
At the same time, sales and other expenses mildly grew as a percentage of revenue, driven by “an increasing merchant mix resulting in higher payment expenses, partially offset by increased efficiencies in customer service.”
Meanwhile, fixed expenses grew 10% YoY, driven mainly by higher cloud costs, but offset by operating efficiencies from cost optimization initiatives. As a result, this still grew slower than revenue, leading to additional leverage.
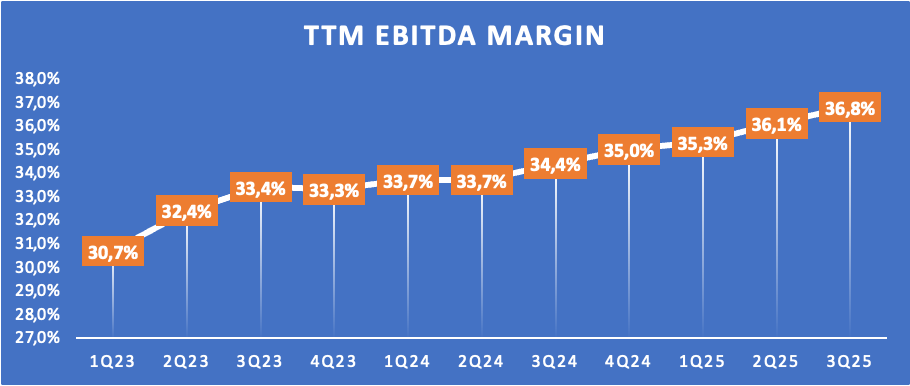
As a result, Booking reported an adjusted EBITDA of $4.2 billion, up 15% YoY, growing 6 percentage points ahead of the high-end of guidance. Moreover, this brings the TTM EBITDA margin to 36.8%. As visible below, Booking has consistently expanded its EBITDA margin at a strong pace and is showing no signs of slowing down, as it continues to improve its P&L and benefits from rapid top-line growth.
Driven by these expanding margins, Booking continues to deliver rapid profit growth. Q3 EPS was up 19% YoY to $99.50, which beat consensus estimates by $3.58 and outgrew EBITDA by four percentage points thanks to a lower share count as a result of share buybacks.
Finally, Booking reported an FCF of $1.4 billion, which entirely covered capital returns, including $700 million in repurchases and $300 million in dividends.
Nevertheless, Booking’s total available cash declined by roughly $1 billion to $17.2 billion, driven by $1.5 billion debt repayment that was originally due in 2030. As a result, Booking ended the quarter with $17 billion in debt, leaving it in a healthy financial position, with plenty of liquidity and practically zero net debt.
All in all, Booking delivered another excellent quarter, achieving strong, accelerating growth across the board, market share gains, and expanding margins due to operating leverage.
On that note, let’s get to the outlook.
Want more out of your subscription? Even more content like this weekly?
Consider InvestInsights PRO - $7.50/month ($70/annually)
This gets you:
A guaranteed 6+ stock analyses every month (of which at least 2-4 are paid-exclusive).
Full insight into my own portfolio, including allocation, transactions, watchlist, performance, and relevant thoughts (16% return CAGR since January 2022).
Instant transaction alerts anytime I buy or sell any shares (Fully transparent).
A complete overview of all my target prices and ratings (online available).
Access to the InvestInsights Hub, containing all of the above in a single online sheet, updated instantly!
Outlook & Valuation
Turning to Booking’s outlook, let’s start with guidance.
Management indicates that global leisure travel demand trends remain stable, despite some global macro uncertainty and geopolitical concerns. Therefore, it now guides for room night growth of between 4% and 6%, which signals moderation driven by a smaller booking window; however, I expect this to also reflect considerable caution from management.
Meanwhile, gross bookings are expected to grow between 11% and 13%, including about 2 percentage points of positive impact from higher flight ticket growth. This is likely to result in revenue growth of between 10% and 12%. Finally, Booking guides for EBITDA margins to expand further, driven by leverage on adjusted fixed operating expenses, which should result in 14% EBITDA growth to between $2 billion and $2.1 billion.
Following the Q3 beat and upbeat Q4 guidance, management also raised its FY25 guidance, and now guides for FY25 room nights to be up 7% YoY, gross bookings to grow between 11% and 12%, revenue to be up about 12%, and EBITDA to grow by 17-18% thanks to a 180 bps higher EBITDA margin, as both variable and fixed expenses should continue to fall as a percentage of revenue. Ultimately, this should lead to EPS growth exceeding 20%.
In my opinion, that is still sublime guidance, signaling Booking continues to outgrow the market. Moreover, management’s updated 2025 guidance surpasses my projections from February (8% revenue growth & 14% EPS growth). Therefore, I have revised my forecasts for the current year meaningfully.
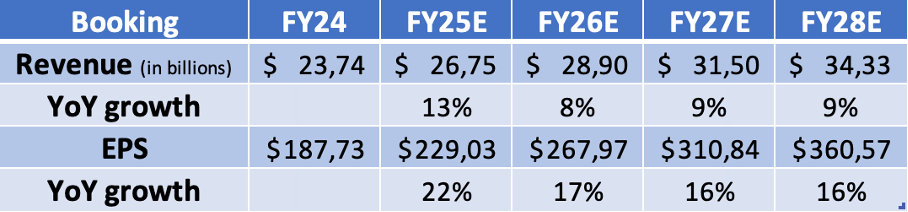
I now expect revenue to grow by 13.7%, reflecting resilient travel demand and management likely guiding cautiously for the fourth quarter. Meanwhile, I have raised my EPS growth forecast to 22%, reflecting healthy margin expansion.
Considering medium-term prospects, it is worth noting that management remains committed to its long-term targets of 8%+ revenue and gross bookings growth, as well as 15% growth in EPS, which I still deem realistic based on the current dynamics. Simply put, Booking continues to win market share and outgrow the underlying market, which should comfortably allow for high-single-digit revenue growth in the medium term.
Meanwhile, continued operating leverage, in addition to high single-digit revenue growth and continued buybacks, should fuel much faster EPS growth in the mid-teens, potentially into the high-teens if macroeconomic conditions improve in the years ahead.
Ultimately, these expectations are reflected in my updated projections below, which may prove too cautious once again, considering Booking’s current momentum, growing moat, and room for macro improvement.
That then brings us to valuation, and despite another brilliant quarter, Booking’s shares have shown some weakness recently, making the current setup particularly appealing. The stock is down roughly 8% over the past month and trades about 15% below its all-time high, despite the company continuing to execute flawlessly across every metric.
As a result, Booking shares now trade at just 21.5 times this year’s earnings and 18 times next year’s earnings, which I deem very appealing. For reference, close peer Airbnb trades at 28x this year’s earnings, despite a similar projected growth outlook. Besides, paying 21.5 times earnings for the undisputed king of travel and a business with a solid and growing moat, growing revenue by high single digits and EPS by at least mid-teens is anything but expensive.
Of course, some discount is warranted given the economic sensitivity of travel demand. Still, even accounting for that, a low-20s multiple remains compelling for such a dominant and capital-efficient compounder. Additionally, on a PEG basis, Booking trades at just 1.3x, representing a 26% discount to its five-year average and approximately a 20% discount to the sector median, clear evidence that the market is underpricing its growth potential.
I really like the value on offer here.
Even when we assume a cautious 21x 2027 exit multiple, which sufficiently prices in the risk of cyclicality against its current outlook, I calculate an end-of-2027 target price of $6,528. Based on its current share price, this implies potential annualized returns of 14% (including dividends).
In my opinion, this reflects a healthy risk-reward profile, particularly given Booking’s history of consistently surpassing projections. Therefore, as long as shares trade below $5,000 per share, I consider these a good buy, and I will continue to load up on weakness.
Rating: Buy - Accumulate below $5,000
FY27 Target Price: $6,528
Implied CAGR from the current price: ~14%
Please leave a like if you enjoyed this post and found it valuable!

Excellent article, thanks!
What is your take on AI travel agents as a potentional risk for Booking's moat?