

Datadog is just an absolutely sublime business, exceptionally well-positioned for the future of compute, as I laid out in my recent deep dive, found here!
Since its founding in 2010, Datadog has quietly evolved into one of the most essential platforms in the enterprise software industry. Today, it acts as the observability and security backbone for over 31,000 companies, offering deep, real-time visibility across infrastructure, applications, logs, user experience, CI/CD pipelines, and security posture, all from a single, integrated console.
Its value proposition is straightforward: as companies migrate to the cloud and their systems become more distributed, fragmented, and complex, the cost of not knowing what’s going on becomes enormous. Downtime leads to lost revenue. Performance issues hurt user engagement. Security blind spots pose significant financial and reputational risks. Datadog helps organizations stay ahead of it all, before problems impact customers or the bottom line.
In simple terms, Datadog helps organizations monitor, analyze, and optimize the performance of their cloud applications and infrastructure. It provides unified, real-time visibility into everything happening across servers, databases, applications, and user experiences.
The numbers tell the story. Since 2020, Datadog has grown revenue at a 41% CAGR and now operates at a $3 billion+ run rate. It boasts gross margins above 80%, free cash flow margins near 30%, and a net retention rate around 120%, placing it among the top tier of SaaS companies by capital efficiency and customer expansion.
Even more compelling: despite its scale, most customers still use only a subset of its 20+ product modules, suggesting a long growth runway within its existing base, especially as the digital and AI revolutions accelerate. As cloud adoption, software complexity, and AI workloads surge, the need for real-time observability is becoming existential. Datadog is not only riding this wave, it’s building the platform that makes it all manageable.
Furthermore, the company operates a usage-based, subscription-driven model, meaning revenue scales naturally as customers expand their infrastructure or adopt additional modules. This creates a powerful “land-and-expand” dynamic, driving predictable, compounding growth over time.
Like I said, this is a brilliant business that is uniquely well-positioned for the future of computing – you can imagine just how much of a tailwind the AI revolution is: with compute growing exponentially, demand for real-time observability is becoming increasingly essential. With Datadog’s relentless pace of innovation, deep technical integration, and neutral, multi-cloud positioning, it is poised to benefit.
On November 6, Datadog released its third-quarter results, which once again massively impressed. The company exceeded consensus estimates and raised its full-year guidance. And it didn’t just raise guidance; it raised the low end above the prior high-end, and this sits well ahead of the pre-earnings consensus and my previous estimates.
Simply put, Datadog’s business continues to fire on all cylinders, with growth accelerating across the board, margins and cash flows fairly resilient, and underlying operational numbers looking excellent, urging plenty of upward revisions in Wall Street’s and my own forecasts.
So, today, it is time to revisit this business by going over the Q3 results and management’s commentary in detail, before making up the balance, updating financial forecasts, and my fair value estimate.
Let’s delve right in!
Welcome to InvestInsights — an independent equity research publication rooted in long-term, buy-and-hold investing, publishing actionable stock/equity research reports weekly!
📈 You’re reading my latest exclusive stock analysis. If you like this analysis, make sure to like & subscribe to receive much more like this!
If you’d like full access to this post and all my other exclusive analysis & portfolio access (14% CAGR since 2022), consider becoming a paid subscriber!
Datadog Delivers Another Brilliant Quarter!
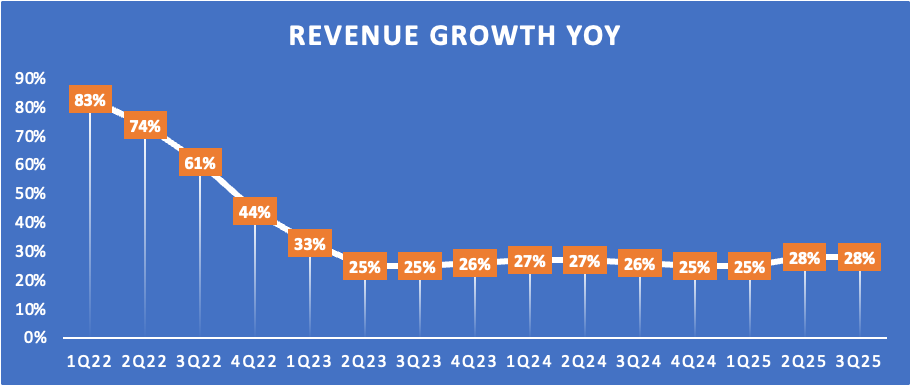
Jumping straight into the results, Datadog reported a Q3 revenue of $886 million, beating consensus estimates by $34 million, sitting above the high-end of management’s guidance, and up 28.4% YoY.
Most notably, this reflects another quarter of accelerating growth, with exceptional demand outweighing the impact of a larger revenue base. In fact, this was the best YoY growth in ten quarters or almost three years, which is exceptional.
In itself, Datadog’s growth quality, or rather its stability, continues to massively impress me. As growth slowed significantly in the post-COVID years, it has stabilized in the mid-twenties by 2023. It has remained there since, now even accelerating toward the high twenties again, which, considering its size, is incredibly impressive and a testament to the quality and growth potential of this business.
To highlight some more growth metrics, Datadog reported billings of $893 million, up 30% YoY, and RPO was $2.79 billion, up a whopping 53% YoY, which is an incredibly promising long-term indicator, suggesting that Datadog continues to sign large, long-term contracts all over.
These numbers above reflect the broad-based positive demand trends Datadog saw in Q3, driven by the ongoing strength in cloud migrations and digital transformation, partly fueled by the rapid adoption of AI technologies, which led to a surge in demand for Datadog’s services.
The result for Datadog was accelerating growth in both customer acquisitions and usage of existing customers, providing it with a double growth engine.
Usage growth, in particular, was a significant driver of its exceptional Q3 performance, far outpacing management’s expectations. It noticed this strength across “both enterprise and SMB, with customers across spending bands, big and small, and customers in a wide variety of industries,” as management put it.
In other words, Datadog saw improving strength across its entire business.
Unsurprisingly, AI continues to be a major driver of Datadog's growth. You see, AI workloads are inherently complex, dynamic, and resource-intensive. Training and deploying large models require massive, distributed infrastructure spanning GPUs, data pipelines, and microservices, which must be monitored in real time to ensure reliability and performance. This creates a huge demand for observability.
At the same time, Datadog has introduced AI-specific capabilities such as model monitoring, anomaly detection, and LLM observability, making it particularly valuable to organizations building and scaling AI applications. As a result, the rapid rise of AI has led to both more customers and greater usage per customer, turning the AI boom into a direct tailwind for Datadog’s growth.
This was no different in Q3. Excluding slower revenue growth from its largest client, Datadog saw AI-native customer usage growth accelerate further in Q3 and increase as a percentage of total revenue. For reference, the company now counts over 500 AI-native customers, accounting for 12% of total revenue, up from 6% last year. What this shows is that AI-native customers still account for a relatively small percentage of Datadog’s total business, but this cohort is rapidly growing in usage, driven by the rapid adoption of AI features and growing compute needs/complexity.
Regarding its largest customer, yes, the Q3 contribution was less; however, Datadog did renew the contract with this customer, which is believed to be OpenAI. You see, as Datadog renews and grows a contract with a customer, it offers better prices for higher usage commitments. However, while this lower pricing takes effect immediately, usage needs time to scale, which is why we observed this minor shortfall in Q3 – it yields better long-term economics for a slight drop in revenue over a short period. Yet, the long-term prospect remains one of higher usage and future revenue growth.
Crucially (and potentially even more impressively), the Q3 usage growth acceleration wasn’t driven solely by AI and cloud migration.
Q3 revenue growth, excluding the AI-native customer group, was 20% YoY, accelerating from 18% in Q2, so we are seeing much-improving trends that, so far, persist in October, according to management. In fact, this Q3 usage growth in its non-AI-native customer base was the best in 12 quarters, highlighting that Datadog is seeing improving demand across its entire business, not just relying on AI-native demand.
What is driving acceleration in non-AI-native revenue? Mainly, rapid module adoption and strong growth in usage amid continued cloud migration and digitalization across nearly every industry.
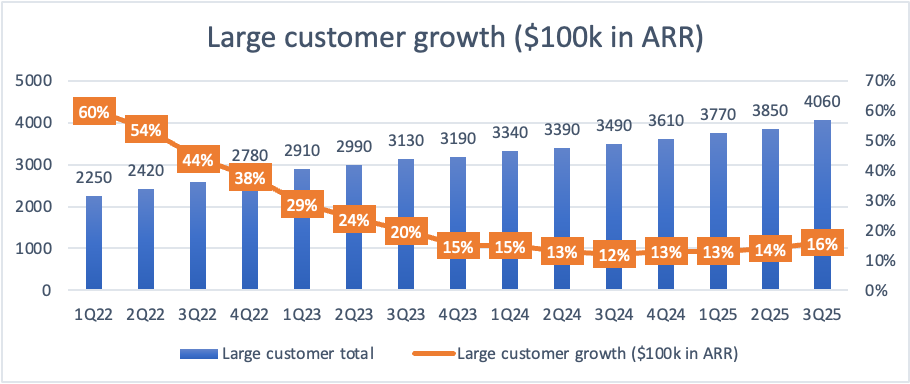
Datadog ended the quarter with 4,060 customers with an ARR of $100,000 or more, up 16% YoY. Once again, this represents the strongest growth in eight quarters, or approximately 2 years.
You see, as Datadog customers gradually increase their use of its tools, revenue per customer grows under its usage-based model, as shown in the graph below. This highlights that the number of “large” customers is growing strongly and accelerating, suggesting accelerating usage in its existing customer base, driven by both higher module adoption and growing usage amid continued cloud migration and digitalization.
This trend is incredibly promising, as it shows that Datadog is becoming increasingly important in its customers' IT stacks.
Regarding module adoption, the trends are clear. As of the end of Q3:
84% of Datadog customers now use two or more products, up from 83% one year ago.
54% of customers use four or more products, up from 49% one year ago.
31% of customers use six or more products, up from 26% one year ago.
16% of customers use eight or more products, up from 12% one year ago.
These numbers continue to trend upward as Datadog introduces new modules at a rapid rate and experiences impressive adoption, driven by customers’ growing appreciation for the platform and increasing demand. This steady rise in multi-module adoption highlights the strength of Datadog’s “land-and-expand” model and the stickiness of its platform.
Of course, it helps that Datadog continuously delivers high levels of innovation and has an impressive track record of successfully entering new markets. While it once started as just an observability tool, it is now much more.
Take Datadog’s digital experience products, including Real User Monitoring, to observe and improve application behavior in mobile and web apps and detect user-facing issues. Over the years, Datadog has developed its capabilities in this area and has been recognized by Gartner as the industry leader for the second consecutive year. Furthermore, digital experience products now deliver over $300 million in ARR and have seen adoption by over 1,000 customers.
Security is another area where Datadog is showing rapid growth and top-notch innovation. Security ARR grew in the mid-50s YoY in Q3, accelerating from the mid-40s in Q2, in large part driven by remarkable success and adoption of its Cloud SIEM and Cloud Security offering.
While Datadog wasn’t a cybersecurity business in its early stages, it has rapidly developed its capabilities in this area in recent years and is slowly becoming a serious player.
This ability to expand into adjacent categories so successfully is a direct result of Datadog’s mission-critical position within enterprise IT stacks. Once embedded across infrastructure, applications, and operations teams, Datadog becomes a central nervous system for digital operations, an indispensable platform that customers naturally want to build more around.
As organizations look to simplify tool sprawl and consolidate vendors, it’s far easier and more efficient to extend existing Datadog deployments into new areas, such as security or digital experience, than to integrate yet another standalone tool.
Datadog gave an interesting example of this during the earnings call: it signed a 7-figure deal with a European telco that previously used an expensive, inefficient IT stack. It then moved to Datadog and adopted 11 modules (mitigating the need for 10 prior suppliers) and is now expected to save over $1 million annually on tool costs alone, along with millions of dollars in reduced penetration costs and lower engineering time.
This dynamic explains why Datadog is seeing such strong multi-module adoption and rapid uptake of new products. Each new capability builds on the same unified data platform and existing workflows, making it both technically simple and operationally attractive for customers to expand.
Meanwhile, every new module adopted deepens Datadog’s footprint, strengthens its stickiness, and drives higher average revenue per customer, turning innovation into sustainable, compounding growth.
Brilliant!
Apart from accelerating usage growth, Datadog also reported accelerating growth in new customers, both in terms of numbers and dollar growth contribution. For reference, a new customer value added 25% to the group YoY revenue growth, up from 20% in Q2, so Datadog is clearly seeing improvement here as well.
The company ended Q3 with 32,000 customers, up 10% YoY. Additionally, the new logo annualized bookings doubled YoY and set a new record, thanks to a larger land size or a higher starting contract value. According to management, this acceleration on this front is driven by significantly improved sales capacity and new logos ramping up faster.
Again, impressive and, above all, promising results as Datadog continues to deliver exceptional traction across nearly every metric.
This is what a business firing on all cylinders and benefitting from secular trends looks like!
To round off this section, Datadog also reported that churn remains incredibly low, as evidenced by a gross revenue retention rate that remains stable in the mid- to high 90s, underscoring the mission-critical nature of the platform. This also enabled net revenue retention of 120%, reflecting strong module adoption and growing usage alongside very low churn.
Truly, these are best-in-class SaaS metrics.
Moving then to the bottom-line results, one could be more critical.
Datadog reported a gross profit of $719 million in Q3, reflecting a gross margin of 81.2%, up 10 bps YoY, with higher data center costs offset by cost-saving efforts by engineers.
Moving to operating expenses, these were up 32% YoY in Q3, outgrowing revenue and thereby pressuring margins. Datadog continues to heavily invest in its business to pursue long-term growth opportunities, which I don’t mind at all, to be honest. Datadog is still in its very early stages, capturing only a small piece of a massive TAM, so investing in growth to capture the opportunity at hand remains the best option.
For reference, Q3 R&D expenses were up 38% YoY, sales and marketing expenses were up 27% YoY, and G&A expenses were up 42% YoY, reflecting investments in headcount.
Down the line, this results in an operating income of $207 million, or a 23% operating margin, down 200 bps YoY due to faster expense growth.
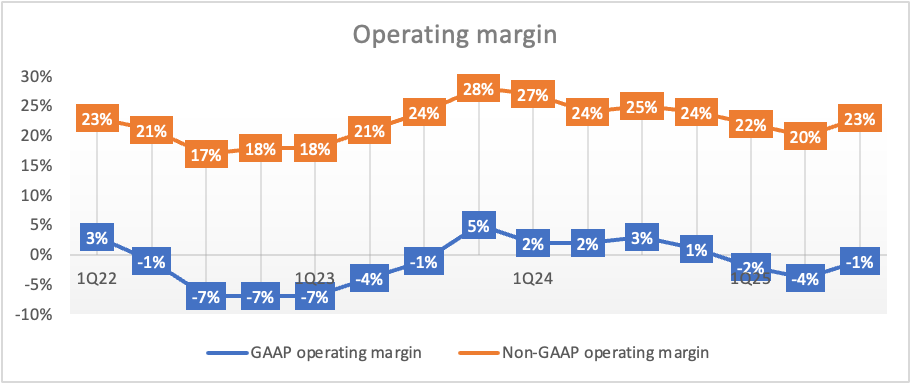
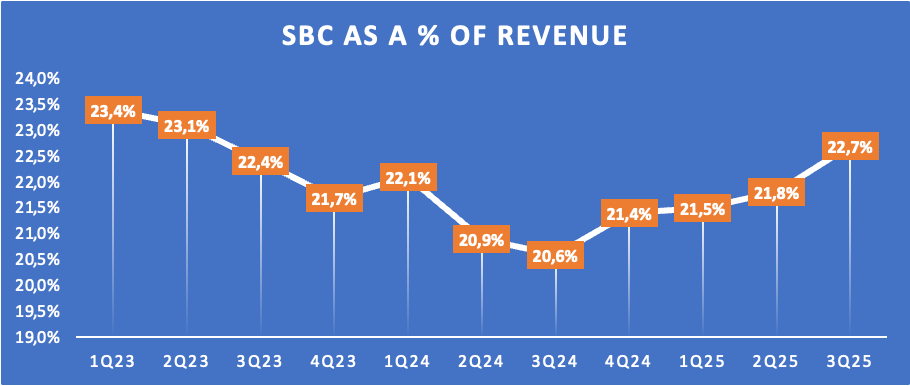
Meanwhile, the GAAP operating margin was -1%, down 400 basis points, with the difference from the non-GAAP operating margin mainly explained by high SBC spend. Also, the GAAP operating margin was down more YoY, driven by SBC growing as a percentage of revenue to its highest level since Q2 2023, reflecting investments in headcount.
This is the one part that I find somewhat more concerning. SBC as a percentage of revenue in Q3 increased 210 bps to 22.7%, which is too high for my taste, especially since the number has been trending upward for four consecutive quarters instead of trending downward.
I know this reflects management’s investment in growth, but I would like a bit more control over this number as we move forward.
Ultimately, this resulted in a non-GAAP EPS of $0.55, beating consensus estimates by $0.09.
Furthermore, Datadog reported a Q3 FCF of $214 million at a 24% FCF margin, indicating that Datadog maintains its Rule of 50 status, despite higher investments leading to a 600 bps drop in the FCF margin YoY. This still allowed the company to maintain a healthy balance sheet, with $4.1 billion in available cash and just $1.3 billion in debt, leaving Datadog in a very strong financial position.
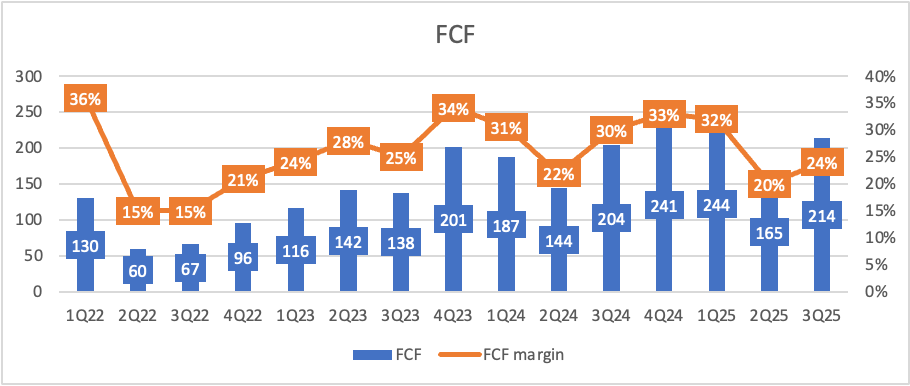
So, we can see some margin pressure and higher SBC spend that might raise some questions, but it doesn’t come as a huge surprise. These numbers should improve as growth accelerates and investments ease. Positively, Datadog’s strong balance sheet allows it to absorb some of these lower cash flows just fine.
Want more out of your subscription? Even more content like this weekly?
Consider InvestInsights PRO - $7.50/month ($70/annually)
This gets you:
A guaranteed 6+ stock analyses every month (of which at least 2-4 are paid-exclusive).
Full insight into my own portfolio, including allocation, transactions, watchlist, performance, and relevant thoughts (14% return CAGR since January 2022).
Instant transaction alerts anytime I buy or sell any shares (Fully transparent).
A complete overview of all my target prices and ratings (online available).
Access to the InvestInsights Hub, containing all of the above in a single online sheet, updated instantly!
Want to keep reading? You will get immediate access to the remainder of this DDOG 0.00%↑ analysis!
Outlook & Valuation
Moving to the outlook, let’s start with management’s guidance.
