

Dollar General is not the kind of company that usually sparks excitement. There’s no cutting-edge tech, no glossy brand halo, and no grand vision of “reinventing retail.” Instead, it sells toothpaste, paper towels, frozen pizza, and detergent, often in small towns that most investors rarely think about. And yet, quietly and consistently, Dollar General has built one of the most resilient and strategically interesting retail businesses in the United States.
At first glance, it looks boring. At second glance, it looks obvious. But at the third glance, the one that really matters for investors, it starts to look unusually compelling. A dense store network, a relentless focus on essentials, a customer base anchored in routine rather than discretion, and a business model designed to work where others simply can’t. Dollar General doesn’t win by being flashy or even by being the cheapest; it wins by being close, convenient, and indispensable. This has allowed it to quite consistently compound sales at an 8% CAGR over the last decade.
Today’s deep dive unpacks that model. I’ll break down the business model, why its growth is driven by traffic rather than price, how its model behaves through economic cycles, and where future growth and margin recovery can realistically come from. It’s a story about how a “boring” retailer became a defensive compounder, and why understanding that story is far more interesting than it first appears.
Welcome to InvestInsights — an independent equity research publication rooted in long-term, buy-and-hold investing, publishing actionable stock/equity research reports weekly!
📈 You’re reading my latest [FREE] stock analysis. If you like this analysis, make sure to like & subscribe to receive much more like this!
If you’d like full portfolio access (13% CAGR since 2022) & additional exclusive analyses, consider becoming a paid subscriber!
This is Dollar General!
Business breakdown
Founded in 1939 and headquartered in Goodlettsville, Tennessee, Dollar General is a discount retailer focused on providing everyday essentials at low prices, primarily serving value-conscious consumers in rural and suburban communities.
The company has a $30 billion market cap and is a relatively dominant force in the U.S. discount retail sector. It captures roughly 58% of sector foot traffic and, together with Dollar Tree, accounts for over 60% of category sales, giving it a fairly dominant position.
Enabling this success is a fundamentally advantaged competitive position and a surprisingly differentiated strategy. Yes, it is quite unique, combining three elements that are individually common but rarely combined.
First of all, Dollar General is a discount retailer, with a business model centered around small, low-cost stores, streamlined assortments, and a highly efficient supply chain.
In essence, a discount retailer competes on value rather than experience, prioritizing low prices, convenience, and efficiency over wide selection or premium service. It is a type of retail business that sells goods at prices lower than those typically charged by traditional supermarkets, department stores, or specialty retailers. The core idea is to offer customers everyday products at reduced prices by operating with a highly cost-efficient business model. Discount retailers usually focus on high sales volumes and frequent customer visits rather than maximizing profit per item.
As I said, to keep prices low, a highly cost-efficient business model is key, so the goal is to limit costs wherever possible. For Dollar General, this means much smaller, simpler store layouts, fewer employees per store, a narrower product assortment, basic merchandising, and minimal in-store services. With smaller store square footage, the upfront investment is low, and when combined with limited staffing, this results in fast payback periods and attractive returns on invested capital.
On top of in-store efficiency, Dollar General (DG) also operates a lean supply chain by designing its logistics network around scale, simplicity, and predictability, all of which are tightly aligned with its small-format, high-frequency retail model.
This includes a highly centralized distribution network. Dollar General operates a growing number of large regional distribution centers that serve hundreds of stores each. High store density within each distribution radius improves truck utilization and lowers cost per delivery, even in low-population areas.
And then there is product mix. DG’s product mix emphasizes everyday essentials, including food, beverages, household supplies, health and personal care items, and basic apparel. For reference, household consumables (cleaning products, paper goods), health & personal care, and other repeat-purchase basics account for around 82% of total net sales.
Why is this important? These drive high-frequency visits and stable demand. By emphasizing food, household goods, and health and personal care items, the company embeds itself in customers’ regular spending patterns rather than relying on discretionary purchases, thereby creating stability and helping keep costs low through lower turnover and larger-volume deals with suppliers.
In addition to these, Dollar General offers a rotating selection of seasonal items, home products, apparel, and discretionary general merchandise that supports margin expansion and basket size growth.
All these strategic decisions make it a highly competitive discount retailer, although DG doesn’t really compete on price as much as other ‘dollar stores.’ You see, in terms of pricing, DG is actually more positioned between the traditional dollar store and larger value retailers. Yes, it sells many items at low price points (including a section of products priced at $1 or less), but its overall assortment spans a wide range of prices above $1. As a result, its average price is often slightly higher than that of traditional dollar stores like Dollar Tree.
So, what enables it to lead to the discount retailer sector despite higher prices?
Well, that brings me to its second differentiating factor.
The company operates 20,901 Dollar General, DG Market, DGX, and pOpshelf stores across the United States, as well as Mi Súper Dollar General stores in Mexico, all of which are small-format stores, making it one of the most geographically extensive brick-and-mortar retailers in the country.
However, what really sets it apart is its focus on rural areas rather than urban centers, locations that larger retailers avoid due to challenging economics. For reference, approximately 80 % of its stores are located in communities with populations under 20,000. On top of that, the company operates a massively dense store network, with its nearly 21,000 stores located within 5 miles of 75% of the U.S. population. Indeed, 75% of Americans don’t have to travel any further than 5 miles to find a DG chain store.
This is key, since it allows the company to compete on both price and convenience, often functioning as the closest retail option for daily necessities in underserved areas – it doesn’t have to compete on pricing if competition is near 0.
In other words, while it is a discount retailer and offering daily necessities at attractive price points is critical in its strategy, its real differentiation is built around convenience-driven value rather than simply being the lowest-price retailer. While it clearly competes on price, its core advantage lies in making everyday essentials easily accessible to customers who are underserved by larger retail formats.
Dollar General’s small-format stores, limited assortments, and low build-out costs enable it to operate profitably in towns too small to support a Walmart, Costco, or a full-size grocery store. This creates a natural barrier to entry, as few national chains can earn attractive returns in these locations.
Meanwhile, this proximity reduces travel time and transportation costs for shoppers, making Dollar General a frequent “fill-in” or primary shopping destination for everyday needs. In many of these communities, Dollar General is the closest or most convenient retail option, which creates local pricing power and customer loyalty despite its low-price positioning.
This is further compounded by the fact that rural markets tend to have a higher concentration of price-sensitive consumers. Lower average incomes and limited local competition increase demand for affordable essentials, reducing the need for aggressive price wars. At the same time, operating costs such as rent, labor, and utilities are generally lower in rural areas, reinforcing the company’s cost advantage.
Finally, rural locations offer a long runway for incremental expansion. Because these markets are fragmented and less saturated than urban areas, Dollar General can continue to add stores without significantly cannibalizing existing locations. This supports steady, capital-efficient growth while maintaining strong store-level economics.
Honestly, it is a simple, straightforward, but brilliant business model, one that is extremely hard to compete with in these specific areas.
A new competitor would need to replicate not just one successful store, but thousands of locations spread across small, fragmented markets with limited population density. The economics that work for Dollar General at scale are far less compelling for a late entrant, particularly for big-box retailers whose models depend on larger trade areas and higher basket sizes.
In effect, Dollar General’s dense store network converts geography into a moat. Proximity drives convenience, convenience drives frequency, frequency supports scale economics, and scale reinforces low prices. Together, these elements enable Dollar General to serve as the closest and most reliable retail option for daily necessities in underserved areas, creating a durable strategic edge that goes beyond price alone.
Brilliant, right?
Overall, Dollar General combines scale, convenience, and a disciplined cost structure to create a resilient retail business with a clear value proposition. Its focus on essential products, rural market penetration, and capital-efficient expansion strategy has positioned the company as a long-term leader in the U.S. discount retail landscape.
Importantly, these three elements reinforce one another over time. Essential products drive traffic, traffic supports rural store economics, and low-cost stores make it viable to operate in fragmented, low-population areas. Scale then improves purchasing power and supply chain efficiency, further strengthening price competitiveness and reinforcing the value proposition.
As a result, Dollar General is not simply a beneficiary of short-term consumer trade-down cycles. It has built a structurally advantaged retail model that compounds over time through disciplined expansion, recurring demand, and geographic focus.
This is what positions the company as a long-term leader in the U.S. discount retail landscape, rather than just another low-price retailer competing on thin margins.
And, crucially, DG has a fairly strong moat in an industry where this is far from a given. This moat is rooted in high barriers to entry, behavioral stickiness, a low-cost model, and a dense rural store network, with geography and size as strong moats.
I think there is little risk of disruption from disruptive emerging competition here, making it quite an attractive prospect.
Strategy drives resilience
Notably, DG’s business has a countercyclical and defensive character. The reason lies in its product inventory, focus geography, and customer base.
First of all, through its discount-store and rural-focused format, the company primarily serves lower- and middle-income households that are sensitive to price fluctuations and economic conditions, which tends to make Dollar General’s business relatively defensive during economic downturns.
Additionally, DG focuses on non-discretionary items such as food, household supplies, and personal care products, exactly the type of products its customer base looks for at attractive prices. Crucially, demand for these categories tends to remain stable even as broader consumer spending weakens, helping protect Dollar General’s sales volumes during recessions. Customers may reduce discretionary purchases or basket sizes, but they still need to buy everyday essentials, anchoring baseline demand.
Furthermore, in downturns, unemployment, wage pressure, or reduced purchasing power make price sensitivity more acute. Dollar General positions itself as an affordable option for necessities, helping limit customer attrition and reduce the risk of abrupt traffic declines. Unlike retailers dependent on discretionary or big-ticket items, Dollar General does not rely on consumer confidence or credit availability to the same extent, making its revenue profile more resilient across the economic cycle.
In fact, the company tends to grow its market share during these challenging periods. As prices rise at traditional supermarkets and mass retailers, higher-income and middle-income consumers increasingly “trade down” to lower-cost channels for everyday goods. Dollar General benefits from this behavior by capturing incremental traffic from shoppers who might not otherwise frequent dollar stores. These add sales resilience, and as inflation persists, these behavioral shifts can become sticky, with some consumers permanently incorporating Dollar General into their regular shopping routines even after economic conditions normalize, as seen in previous cycles.
So, economic turmoil tends to be more of a tailwind to DG’s business than a headwind.
In essence, Dollar General’s focus on lower- and middle-income consumers makes the business structurally defensive, while its value positioning allows it to capture upside during inflation through trade-down behavior. The result is a retailer that may not be immune to economic stress, but is often relatively more resilient and, at times, countercyclical compared with broader discretionary retail, especially as inflationary pressures and trade-down behavior can increase traffic as consumers seek cheaper alternatives for everyday goods.
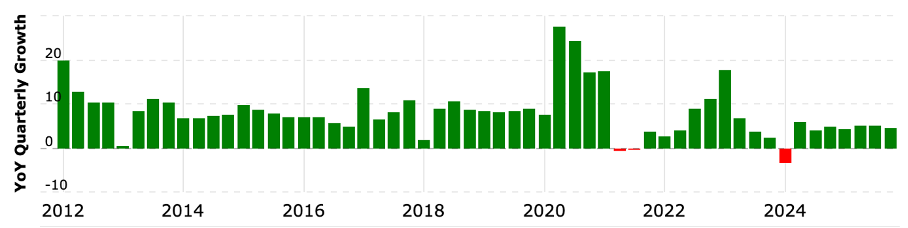
Highlighting this best is the graph below. Whether it was a strong economic upcycle, a COVID-19 pandemic, record-high inflation, or a shrinking economy, DG’s sales have continued to grow in nearly every single quarter since 2010. The company only posted negative sales growth in three quarters, and two of those weren’t even a 1% drop.
As an investor, I really like this countercyclical profile.
What will be driving growth in the future?
Dollar General’s growth over the coming years or decade is likely to come from a combination of steady unit expansion, incremental same-store sales improvements, and continued gains in relevance as a value-oriented, convenience-first retailer. While one shouldn’t expect rapid growth from this business, its secular drivers, coming from structurally higher prices, tighter budgets, geography, and growing consumer weakness, actually look rather good, giving me quite some confidence in the decade ahead.
Rather than relying on any single catalyst, the company’s growth model is designed to compound through multiple, relatively predictable, structural levers.
Let’s start more company-specific. Of course, continued store/unit expansion is one of the most obvious levers to drive sales growth, and DG’s room for expansion remains significant, despite an almost 21,000-store base.
Dollar General continues to see plenty of opportunity to add stores in underserved rural and semi-rural markets, as well as in select suburban infill locations. According to management, there is a runway for new store expansion, with approximately 11,000 opportunities for Dollar General stores in the U.S. without risk of saturation. This allows it to open almost 500 new stores per year from 2026 onward, notably more than its retail peers, and provides a strong lift to sales.
Allowing this is its unique model – small stores in low-cost areas, allowing it to earn good returns on investment. While physical retail is shrinking in urban areas, rural locations still require physical expansion, so the runway for DG remains notably larger.
In addition to new openings, remodels, and relocations can improve productivity, extend the economic life of the existing store base, and boost sales.
Dollar General’s “Renovate” and “Elevate” store actions are part of a broader, multi-year effort to improve store execution, customer experience, and long-term economics without changing the company’s core low-price, small-format model. Rather than a wholesale reinvention of the concept, these initiatives focus on fixing operational pain points, modernizing the fleet, and selectively boosting productivity per store.
And with excellent results. Renovate and Elevate projects are driving a low single-digit uplift in comp sales, an excellent result.
For reference, Renovate focuses on getting the basics right again: improving backroom organization, reducing inventory congestion, simplifying planograms, and ensuring shelves are stocked accurately and efficiently. It is, therefore, less about aesthetics and more about operational health, shrink reduction, and consistency across the store base.
Meanwhile, the “Elevate” actions build on that foundation by selectively upgrading stores that can support higher sales and returns. Elevate includes remodels, layout enhancements, and assortment upgrades designed to increase traffic, basket size, and category penetration. This often involves expanding cooler doors for refrigerated and frozen food, improving category adjacencies, and refining merchandising to better match local demand.
Take fresh produce. GD currently offers this in only 7,000 stores but is expected to gradually expand it, aiming to grow basket size through a more complete offering. Similarly, the company aims to grow its frozen food offerings. While these carry lower margins, they can grow basket sizes. Ultimately, the goal of Elevate is to lift productivity in higher-potential locations rather than applying a one-size-fits-all upgrade across the entire fleet.
Combined, these remodel and expansion efforts provide a decent growth opportunity for GD.
Meanwhile, structural demand shifts should allow DG to capture growing same-store traffic, lifting comp sales growth to a targeted 2-3% annually.
Take sustained pressure on household budgets. Real wage growth for lower- and middle-income consumers has lagged inflation over long periods, particularly for non-discretionary categories such as food, housing, and energy. This has structurally increased price sensitivity and reinforced demand for discount formats. Even outside recessionary periods, a larger share of consumers actively seeks lower-priced channels for everyday essentials, expanding the addressable market for discount retailers like Dollar General.
Additionally, data shows that consumer “trade-down” behavior has also become more persistent. What was once cyclical (shoppers moving to discount channels during downturns) has increasingly become structural. Consumers now routinely split their shopping across multiple formats, using discount stores for staples and fill-in trips while reserving supermarkets or big-box retailers for occasional stock-up purchases. This channel fragmentation benefits small-format discounters that specialize in convenience and low absolute price points.
And finally, convenience itself has become a growth category. Time scarcity, higher transportation costs, and lifestyle changes have increased consumers’ value of proximity and speed. This elevates small-format stores that enable quick, low-effort trips for essentials, even if per-unit pricing is not the lowest available.
All these factors point to structurally stronger, more persistent demand for value-oriented, convenience-led discount retail, especially for staples. As a result, I expect traffic trends over the coming years to favor DG, enabling healthy same-store sales growth. This should come pretty naturally, especially given its rural focus.
Of course, the macro environment can finally act as a growth tailwind. Economic stress, inflation, or wage pressure often push consumers toward value retailers, expanding Dollar General’s addressable customer base beyond its traditional core.
I see this as a potentially strong headwind in the near term.
Student debt and delinquencies are a real pressure point. Outstanding student loan debt was about $1.64T in Q2 2025, and the New York Fed noted that 10.2% of aggregate student debt was reported 90+ days delinquent in that quarter as delinquency reporting resumed.
Household debt loads remain high, with delinquencies elevated. Total household debt was $18.39T in Q2 2025, and 4.4% of outstanding debt was in some stage of delinquency.
Credit card balances are large and continue to grow. Credit card balances were about $1.21T in Q2 2025.
Savings buffers look thin. The U.S. personal saving rate was around 4.0% in Sep 2025 (low by pre-pandemic norms), suggesting less cushion against shocks.
Inflation remains troubling.
The U.S. consumer isn’t healthy and increasingly value-conscious. If the U.S. stays in a world of budget pressure, modestly elevated inflation, and higher debt service, that’s generally supportive of Dollar General’s relevance and traffic.
The company seems well positioned to benefit.
Ultimately, I think it is fair to assume DG will deliver 2-4% comp sales growth and 4-6% sales growth, on average, over the next decade, accounting for expansion. I think that is a pretty compelling outlook for the kind of business we’re looking at.
On that note, let’s take a closer look at DG’s recent performance and financials!
Recent results and financials
Dollar General released its latest financial results back in early December 2025 – its fiscal Q3 2025 results – and delivered a rather impressive report, showing very healthy underlying numbers that surpassed expectations. The company continues to deliver balanced sales growth through increased traffic, exceptional earnings through margin expansion, and market share gains.
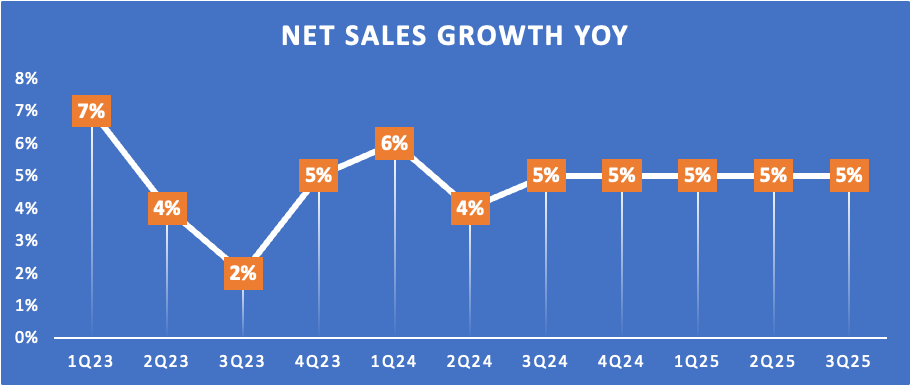
Jumping right into the numbers, DG reported Q3 net sales growth of 4.6% to $10.6 billion, beating consensus estimates by $50 million. This marks the fifth consecutive quarter in which revenue growth has exceeded 4.5% and is in the 5% range, demonstrating strong consistency despite macroeconomic turmoil and elevated uncertainty in the U.S. under the Trump presidency.
For DG, these are good results. Realistically, mid-single-digit growth is probably the best achievable, and it is delivering this quite consistently, driven by healthy comp sales growth and continued expansion.
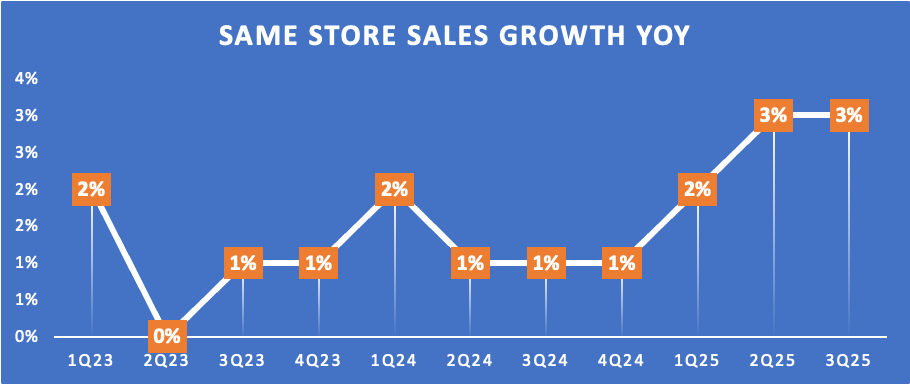
Q3 same-store or comparable sales grew 2.5%, entirely driven by growth in traffic, with the average basket size essentially flat, as a mild increase in average unit retail price per item was offset by fewer items on average.
This combination of driving comp sales makes strategic sense, given Dollar General’s highly price-sensitive customer base and value positioning, as the company prioritizes maintaining low absolute prices to protect affordability. This means price is rarely a driver of growth – when price inflation is driving growth in pricing, fewer purchases largely offset this impact. Therefore, incremental growth is more sustainably driven by higher shopping frequency and trade-down traffic rather than price-led basket expansion, a dynamic that is likely to persist.
This dynamic led to healthy comp growth in Q3. This has now settled in the 2-3% range in recent quarters, in line with management’s long-term financial framework.
Management indicated that current traffic and basket composition are consistent with what it has historically observed when its core customer feels more pressured to spend – a smaller basket size, a growing focus on daily consumables, and more visits. This partly explains the growth in traffic and smaller basket sizes.
Additionally, a growing customer base is another driver of traffic, with a recent boost primarily from higher-income households, which DG is confident it can retain through its combination of value and convenience, allowing it to keep gaining market share across all income brackets, especially as the U.S. consumer stays under pressure.
In part driven by this dynamic, DG grew its market share in Q3 in both dollars and units in highly consumable product sales – a tighter consumer means more look to buy daily goods as lower prices in discount formats – and in non-consumable product sales, indicating that customers are also increasingly going to DG for products apart from daily needs, which is a positive trend, which management attributes to improved execution, a compelling offering, and broadening appeal to a wide range of customers.
Regarding pricing, DG remains pleased with its position. While it isn’t the cheapest among peers, it remains within its targeted range of 3 to 4 percentage points below mass retailers on average, which is enough to attract a growing number of customers in rural areas, especially when combined with convenience. Besides, the company has more than 2,000 SKUs at or below the $1. Its Value Valley offering, which comprises more than 500 rotating SKUs at the $1 price point, was once again the strongest-performing set in the quarter, with same-store sales growth of 7.6%.
So, clearly, its value offering remains attractive, increasingly so.
On top of this ‘organic’ growth, DG also opened 196 new stores in Q3, primarily in its 8,500-square-foot store format in rural markets. It has also opened 7 new stores in Mexico YTD, bringing the total to 15. Additionally, remodel efforts have shown strong results, leading to a 6% sales lift in applicable stores.
Another interesting opportunity DG is executing on is delivery, through partnerships with DoorDash and Uber. While its proximity is already a strong advantage, delivery further accentuates the strength of its dense store network, bringing DG even closer to customers. Its DoorDash partnership already covers over 18,000 stores, and it recently entered a partnership with Uber, now covering 17,000 stores, offering even greater availability. Ultimately, DG believes this will accelerate growth and add to its market share.
I can clearly see the appeal: delivery effectively monetizes Dollar General’s dense store footprint by turning proximity into speed, expanding convenience for time-constrained and transportation-limited customers, and capturing incremental, needs-based trips that might not otherwise occur, all without requiring heavy capital investment or a shift away from its core low-price, small-basket model.
Additionally, DG already sees larger basket sizes for deliveries than the average in-store transaction and a very strong repeat visit rate from customers. Over time, this could become a decent growth accelerator as adoption grows.
On that note, let’s move to the P&L, which is rather interesting.
Starting at the top, DG reported a gross margin of 29.9% in Q3, up a strong 110 bps YoY. This YoY expansion was primarily driven by higher inventory markups and lower shrink, partly offset by increased LIFO provision (the accounting adjustment a company records to reflect the impact of using Last-In, First-Out (LIFO) inventory accounting on its cost of goods sold and earnings).
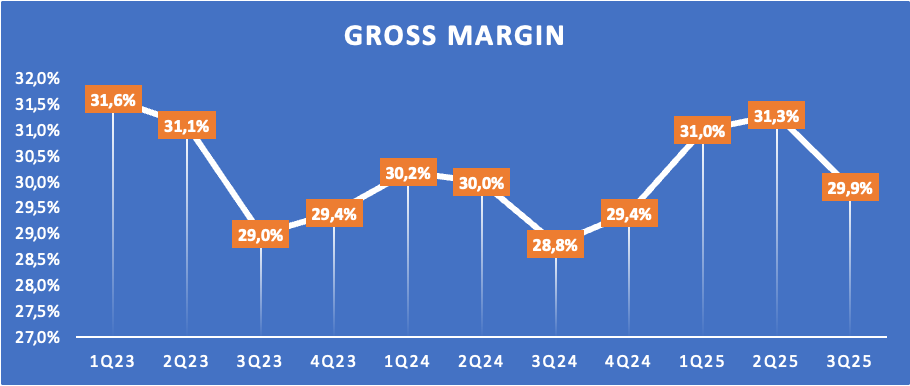
The most important development is the reduction in shrink. In Q3, shrink improved by 90 bps. For reference, this is the loss of inventory between the time it is purchased or produced and the time it is sold. In retail, it refers to merchandise that disappears or becomes unsellable, thereby reducing gross profit. In reality, this primarily reflects theft, damage, or spoilage.
In recent years, shrink became quite a hefty headwind to DG’s gross margin, but recent efforts have been really successful in bringing this down rapidly, ahead of expectations, and management sees room for continued improvement over time, which should remain a tailwind to margins, though likely to a lesser extent compared to recent quarters as further improvements are harder earned.
Nevertheless, management remains confident it will continue to deliver gross margin expansion in the coming years.
For example, private-label penetration remains notably low for DG at roughly 20% of sales. This has been growing over time, but remains below that of some other large mass-market retailers. This runway offers further operating leverage/gross margin upside, as these products carry higher margins. This is just one lever management can pull to expand margins.
Moving further down the line, DG reported SG&A at 25.9% of revenue, up 25 bps YoY.
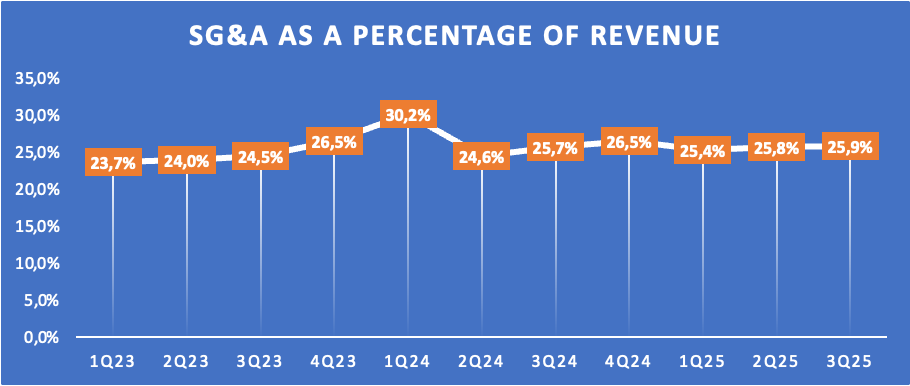
As shown above, SG&A as a percentage of revenue has been on the rise over the last three years, and has been so for much of the last decade, weighing on its operating margin.
Driving this growth is a combination of several overlapping structural and cyclical factors, many of which stem from operating a labor-intensive, price-sensitive retail model during an unusually volatile cost environment.
Labor has been the most persistent driver. Tight U.S. labor markets, rising minimum wages, and competition from other retailers and logistics employers have pushed hourly wage rates higher, particularly in rural and semi-rural areas. Because each store requires a minimum staffing level regardless of sales volume, wage inflation flows directly into SG&A rather than being easily offset by productivity gains. At the same time, higher turnover has increased recruiting, training, and overtime costs, further pressuring store-level expenses.
Another factor has been inflation across non-labor operating inputs. Utilities, maintenance, transportation-related store expenses, and occupancy costs have all increased. While Dollar General benefits from relatively low rents in rural markets, lease renewals and new store openings have still occurred at higher cost levels than in prior years. Because the company’s pricing power is constrained by its value proposition and customer sensitivity, these cost increases cannot always be fully passed through to consumers, at least not in the period itself.
The end result is SG&A growing as a percentage of revenue for most of the last decade, putting pressure on the operating margin, although recent efforts have moderated this growth somewhat.
This moderation allowed Q3 operating profit to grow by 32% to $426 million, reflecting an operating margin of 4%, up 80 bps YoY, as DG gradually improves its cost profile.
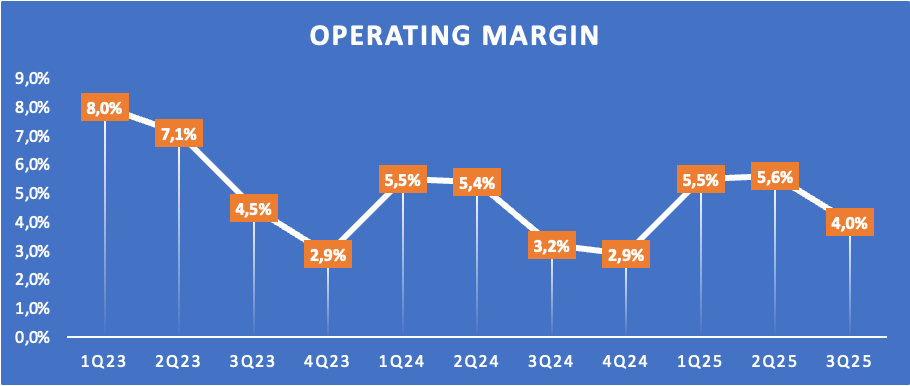
However, if we look at the operating margin over the last decade, today’s levels remain low. You see, in the early 2010s, Dollar General benefited from a uniquely favorable backdrop. Labor was abundant and inexpensive, shrink levels were low, and the company was scaling rapidly into largely uncontested rural markets. Store productivity was rising, SG&A leverage was strong, and consumables penetration, while growing, had not yet diluted margins to the same extent it does today. That combination allowed operating margins to expand to levels that, in hindsight, were closer to cyclical peaks than sustainable baselines.
So, margins fell not because the model broke, but because cost inflation, shrink, and execution drift overwhelmed a low-margin structure. It is a sort of normalization.
Focusing on today’s numbers, the operating margin appears to be stabilizing in the mid-single-digit range amid recent improvements in shrink and easing cost pressures.
But is there room for margins to recover? Well, I think there is some room for optimism, even though margins are unlikely to recover to that 10% mark ever again.
Management has explicitly reset priorities toward execution over expansion through its Renovate and Elevate initiatives, focusing on inventory discipline, labor productivity, and store standards. Early signs suggest improvements in in-stock rates, store conditions, and operational consistency, which are prerequisites for margin recovery.
There are also clear structural levers. Shrink reduction alone offers substantial upside given how far it has risen from historical norms. Private-label penetration remains well below its long-term potential, offering a margin-accretive growth path without sacrificing value perception. Supply chain investments made during the inflationary period should begin to deliver operating leverage as volumes normalize. Importantly, store growth remains capital-efficient, meaning incremental sales still carry attractive contribution margins once execution stabilizes.
Don’t forget, because Dollar General operates on thin margins, even small improvements across multiple levers can have a meaningful cumulative impact on operating profitability.
That said, expectations need to be realistic. The industry, labor market, and customer mix of 2026 are not those of 2012. A return to peak margins is unlikely and, if it requires sacrificing value leadership, arguably undesirable. The more credible long-term case is recovery toward a mid-single-digit operating margin that reflects a more mature, consumables-heavy, but still structurally advantaged business.
So, I’d say that the operating margin, all things considered, is likely to show steady improvement in the coming years. It is unlikely to consistently grow as fast as it did last quarter, but gradual improvement from current levels seems likely.
Moving further down the line, the improvement in operating margin and slightly lower net interest expense, offset by a slightly higher tax rate, resulted in an EPS of $1.28, up 44% YoY, exceeding the high end of management’s guidance and beating consensus estimates by $0.35.
Finally, DG continued to strengthen its financial position. Inventories continue to decline, falling another 6.5% YoY to $6.7 billion, which is well down from prior years. This is a clear positive for working capital efficiency and cash flow. Lower inventory levels reduce markdown risk and storage costs while freeing up cash that can be redeployed toward store remodels, price investments, or debt reduction. It also suggests DG is getting demand forecasting back under control after the post-pandemic inventory glut. And it sees room to reduce this further in the coming quarters.
Additionally, the company has delivered excellent cash flow from operations of $2.8 billion YTD, up 28% YoY. This allowed GD to redeem $600 million of senior notes in Q3, well ahead of their 2027 expiration, reducing future interest expense.
As a result, GD ended the quarter with $1.2 billion in cash and $16.5 billion in total debt, leaving the company quite leveraged, with $15.3 billion in net debt, or over 3x its adjusted debt-to-adjusted EBITDAR target.
Of course, this isn’t ideal, but I don’t view it as a deal breaker. The company has no upcoming maturities and is already paying down debt due in 2027, driven by improving cash flows. Additionally, FCF is improving rapidly, driven by a solid top line and improving margins.
While DG’s FCF margin peaked in 2020 thanks to COVID-related tailwinds, this plummeted in 2022 to just 1%, driven by input cost inflation and high investments. Positively, margins have been gradually improving since, with the FCF margin hitting 5.7% YTD.
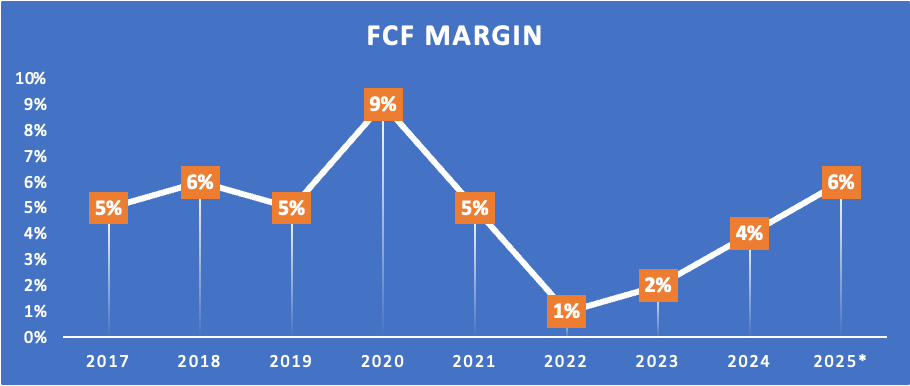
YTD, DG has generated $1.8 billion in FCF and is likely to exceed $2 billion in 2025, which is excellent. Considering this already considerable number and the prospect of further growth in the coming years, I am not at all worried about this level of debt, especially given management's active efforts to strengthen its balance sheet.
For what it’s worth, the company receives a stable BBB rating from both S&P and Moody’s.
These strong cash flows and solid balance sheet also allow DG to keep paying a very solid dividend. Shares now pay a healthy 1.6% yield based on a conservative 36% earnings payout ratio or closer to a 25% FCF payout at an annual commitment of $520 million. This is well below the peer average, which is typically over 50%.
So, we have a good yield and conservative payout, which is a good backdrop for future growth.
However, while DG has achieved a 10% CAGR in dividends over the last 5 years, its dividend growth hasn’t been consistent. It cut its dividend in 2015 and didn’t raise it in 2025, as the board prioritized financial flexibility to improve its financial profile.
Yet, I have to say I don’t mind this much. While consistency isn’t great, I do appreciate DG’s focus on financial health, which I fully agree with. Additionally, despite inconsistent dividend growth, its dividend growth track record is strong, with the payout almost tripling since 2015, and its low payout ratio means the risk of future cuts is minimal – it is well supported by cash flows.
Ultimately, it looks like a sound foundation to build on. The company is in good financial health.
On that note, time to delve into the outlook.
Want more out of your subscription? Even more content like this weekly? Consider InvestInsights PRO — $7.50/month ($70/annually)
PRO gets you:
A guaranteed minimum of 6-8 stock analyses every month (of which at least 3-4 are paid-exclusive).
Full insight into my own portfolio, including allocation, transactions, watchlist, and performance (13% annualized return since January 2022).
Instant transaction alerts anytime I buy or sell any shares (Fully transparent).
An overview of all my target prices and ratings (available online, updated weekly).
Access to the InvestInsights Hub, containing all of the above in a single online sheet, updated constantly!
Outlook & Valuation
Starting with management’s own near-term guidance, it claimed it was off to a good start in the fourth quarter and, combined with the strong (out)performance in Q3, management raised its FY25 outlook, even after accounting for continued uncertainty in consumer behavior.
It now guides FY25 sales growth of 4.7% to 4.9% (up from 4.3% to 4.8% previously), which sits comfortably ahead of the pre-earnings consensus of 4.6%. This will be driven by comp sales growth of 2.5% to 2.7%, which falls comfortably in management’s long-term 2-3% targeted range. Helped by margin expansion, management expects EPS to be in the range of $6.30 to $6.50 (up from $5.80 to $6.30 prior), up a strong 25% at the midpoint and sitting comfortably ahead of a $6.14 pre-earnings consensus.
With regard to margins, management expects continued gross margin expansion in Q4, though to a lesser extent than in Q3, as shrink will remain a tailwind but less so, as it starts to lap last year’s improvements. Additionally, management expects capital spending at the lower end of its stated range of $1.3 billion to $1.4 billion, despite 575 new store openings in the U.S., 2,000 Project Renovate remodels, 2,250 Project Elevate remodels, and 45 relocations.
These lower costs should be another tailwind to the operating margins and profits down the line. And these strong cash flows (FCF likely exceeding $2 billion) will allow DG to redeem another $550 million in 2027 senior notes, strengthening its financial position.
Overall, DG sees excellent momentum, and this should persist in the coming quarters, with the company delivering stronger results than Wall Street anticipated.
Looking at DG’s long-term financial framework, management is optimistic. It aims to consistently deliver 2-3% comp sales growth, which, combined with store expansion, should drive 4-6% sales growth through the cycles. As noted earlier, given the underlying drivers and strong execution in recent years, I think these are very realistic targets.
Furthermore, DG aims to deliver earnings growth closer to 10% in the coming years, and again, I think this isn’t overly optimistic from management. DG’s margins are at decade lows due to the earlier-discussed reasons, leaving ample room for improvement, which management has already been delivering in recent quarters. And as factors like labor costs, shrink, and recent input cost inflation ease due to operational and macro improvements, I see loads of room for DG to gradually grow margins.
No, I don’t see margins growing by 100 bps annually as we saw in recent quarters, but gradual, smaller gains in the coming years seem likely. Given DG’s low-margin business model, these small gains translate into significant incremental increases in profits and cash flows. Therefore, a minimal high single-digit earnings growth rate through 2030 is achievable, with room for further upside depending on execution.
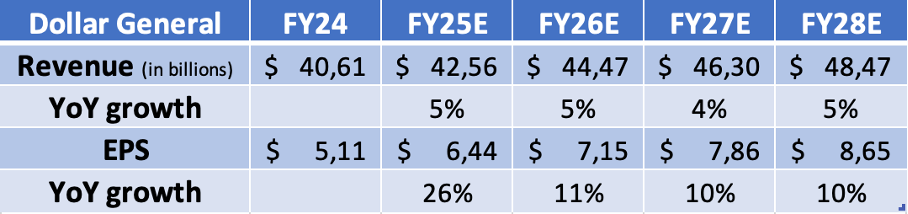
Jumping to my own forecasts, I now assume revenue and EPS toward the high end of management’s guidance, as I expect management to once again be slightly conservative given recent momentum and Q4 retail data.
Looking further ahead, as discussed, I see DG delivering mid-single-digit growth in the years ahead, likely quite steadily through the cycles. For now, taking into account some macro issues and uncertainty, I assume net sales growth to grow in the range of 4-5% through 2028, through a combination of stable comp sales in the 2-3% range, helped by remodels and positive trends toward discount retail, and continued store expansion efforts.
Meanwhile, gradual margin expansion should allow for EPS to grow notably faster, likely at a 10% rate, in line with management’s financial framework.
These assumptions are incorporated in greater detail in the forecast below!
That then brings us to valuation. Notably, DG has been an outperformer in 2025, and shares are off to a very good start in 2026. As a result, shares have gained over 100% in value over the last year, elevating valuation multiples by quite a bit – $DG shares are anything but cheap. At a current share price of $144, we are looking at:
22x 2025 earnings and 20x 2026 earnings, both of which are a premium to its 5-year average of just under 19x.
14x this year’s FCF and 13x next year’s FCF, which is roughly in line with the 5-year average.
Honestly, I believe this suggests that DG shares are now fully valued, with a significant portion of the anticipated recovery and forward growth already reflected in the price after the sharp run-up over the past year. At roughly 22x FY25 earnings and ~20x FY26 earnings, the stock trades above its five-year average multiple of just under 19x, a period that already included both unusually strong COVID-era results and the subsequent margin compression. On a free cash flow basis, the picture is more balanced, with the stock trading at around 14x current-year FCF and ~13x forward FCF, broadly in line with its longer-term average, suggesting that cash flow expectations are reasonable but not cheap.
From a historical perspective, Dollar General has typically traded in a mid-teens to high-teens earnings multiple during periods of stable execution, modest growth, and normalized margins. Higher multiples have generally been reserved for periods when margins were expanding rapidly or when macro conditions strongly favored discount retail. Today’s valuation implies confidence that the company can sustain mid-single-digit revenue growth, gradually rebuild margins, and deliver close to double-digit earnings growth over time, assumptions that are credible but no longer conservative.
Now, arguably, DG looks much better than it has in the past 5 years, so a mild premium to this does make sense. The business is executing better, shrink is coming down, inventories are under control, and cash flow generation has improved materially. In that sense, the current valuation reflects a higher-quality, more resilient Dollar General than investors were willing to underwrite during the margin trough. The company also deserves a premium relative to many discretionary retailers due to its defensive, countercyclical profile and strong free cash flow characteristics.
At the same time, paying over 20x earnings for a mass retailer growing sales by mid-single digits at best is tough. Dollar General remains a structurally low-margin business operating in a highly competitive industry with limited pricing power and ongoing exposure to labor and shrink. While margins can and likely will improve from today’s depressed levels, a return to historical peak margins is unlikely, and long-term growth will remain steady rather than spectacular. For retailers with similar growth profiles, the market has historically been reluctant to sustain earnings multiples much above the high-teens unless growth or margin expansion is unusually strong.
Viewed through that lens, a more “fair” valuation for Dollar General over a full cycle likely sits closer to its historical averages, somewhere in the high-teens earnings multiple range, which would still reward its quality, resilience, and cash flow generation without assuming flawless execution.
For reference, assuming a 19x (earnings) 2027 exit multiple, which I deem fair for this business (while leaving some margin), I calculate an end-of-2027 target price of $150. At a current share price of $142, this implies annual returns of roughly 4% (including dividends), which does not offer a compelling risk-reward.
In other words, DG shares are fully valued, likely even slightly overvalued, without some level of outperformance, which I don’t deem highly likely. Therefore, I don’t deem DG shares attractive right now. While I do think this is a great business to own in a long-term-oriented portfolio, offering a high level of reliability and durability, I am absolutely not willing to overpay for it due to overly run-up optimism.
Personally, I think the risk-reward becomes much more compelling below $120 - $125 per share. For now, I remain on the sidelines, but I will add this one to my watchlist.
Rating: Hold - Accumulate below $125
FY27 Target Price: $150
Implied CAGR from the current price: 4%
Please leave a like if you enjoyed this post and found it valuable!

Dear Daan, thanks for your write-up. Lidl seems to have a similar value proposition and expanding in the USA. Do you see Lidl possibly as a long term competitor to DG?
The company doesn’t fit my investment universe, but it was a real pleasure reading your deep dive.
Thanks for sharing it!