

GE Aerospace is one of those stocks I own and never intend to sell.
The company is the dominant force in the global aircraft engine market, spanning both commercial and defense, an industry that is a quasi-oligopoly of GE/CFM, Pratt & Whitney, and Rolls-Royce, where the capital intensity and certification risk of developing a new large turbofan discourages new entrants and fragmentation – this position, built over decades with accumulated data and trust, is something rivals can’t replicate even if they matched GE on engineering. It is a perfect example of a durable business, impossible to disrupt, guaranteed to continue dominating for decades to come.
And GE is the undisputed leader of this oligopoly. The company supplies engines to the F-16, F-15, and F/A-18E/F Super Hornet fighter jets, as well as the AH-64 Apache and UH-60 Black Hawk helicopters. Commercially, it is the sole supplier to the Boeing 737 MAX and Boeing 777, the majority provider to the Airbus A320neo and the Boeing 787 Dreamliner.
In other words, it dominates. It has a blinding 80,000 aircraft equipped with its engines, 2.3 billion in accumulated flight hours, and roughly three of every four commercial flights worldwide fly on a GE-built engine.
And this isn’t a boring, slow-growing business either, with GE having a good runway ahead. The global commercial fleet is projected to grow from roughly 29,000 aircraft in 2025 to about 38,300 by 2035, engine MRO spend is expected to grow 3-4% annually through 2035 as utilization and fleet age both rise, and defense budgets are climbing on a separate but complementary growth track, providing a strong growth backdrop for GE.
But that leaves me yet to point out the most beautiful part – the business model, which is, structurally, about as close to an industrial annuity as exists in public markets. GE sells engines to Boeing and Airbus at thin or near-zero margins, but that’s merely the ticket into a 20-to-30-year relationship: the servicing, spare parts, and long-term service agreements that follow each engine into the field generate the bulk of GE’s profit, with services making up roughly 70% of revenue. And once GE wins a platform, such as the F-16 or the Boeing 777, it effectively locks in decades of inflation-resistant, high-margin cash flow.
That is just brilliant. You have a business that dominates a structural oligopoly with genuine switching costs, insane barriers to entry, and a mission-critical product; an industry supported by secular tailwinds; and a brilliant business model that provides incredibly decade-long revenue visibility through recurring service contracts on an 80,000 aircraft installed base.
Layer on top of that a capable management team, very strong financials and cash flows, excellent reinvestment metrics, and explosive dividend growth, and you get exactly the kind of business I want to own and never sell. This one is guaranteed to be around in another 20-30 years and be worth significantly more.
If you want to know even more about the business, check out my Deep Dive from January here!
Today, however, I want to focus on GE’s Q2 results and update my thesis and view of the stock. GE released its Q2 results last Thursday, April 16, and delivered impressive numbers across the board. The company blew past expectations, raised the full-year outlook, and provided very positive commentary, with demand trending above expectations despite near-term concerns over the war in Iran and lower-than-expected global flight activity.
So, let’s break down the numbers and H1 developments before updating my financial model and thesis. Let’s delve in!
Welcome to InvestInsights — an independent equity research publication rooted in long-term, buy-and-hold investing, publishing actionable stock/equity research reports weekly!
📈 You’re reading my latest [FREE] stock analysis. If you like this analysis, make sure to like & subscribe to receive much more like this, weekly!
Q2 Financial & Performance Review
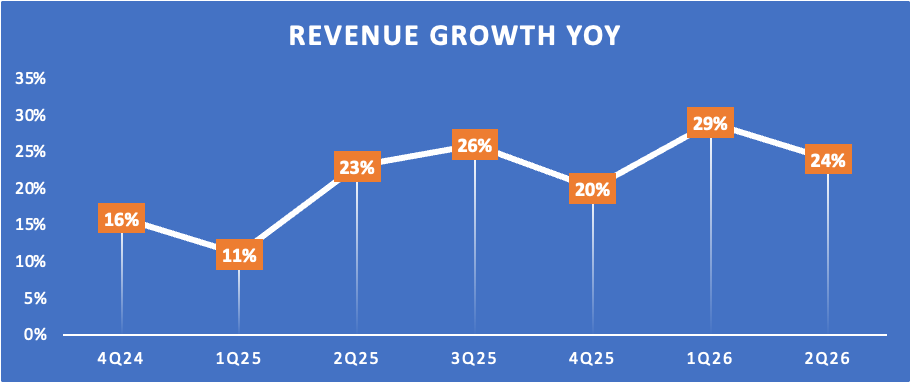
Let me jump straight into the Q2 numbers. GE reported Q2 adjusted revenue of $12.6 billion, clearing the consensus by a strong $710 million and easily beating my own expectations. Moreover, this reflects 24% YoY growth, with momentum remaining very much in line with the impressive numbers GE has delivered for most of 2025 and 2026, proving more sustainable than anticipated.
That is especially impressive against the first-half departures flat due to the Iran war disruption, which management indicates didn’t lead to any changes in customer behavior.
Crucially, this growth also continued to be driven by both segments, with commercial (CES) revenue up 27% YoY and defense (DPT) revenue up 16% YoY. Driving this is a very favorable combination of post-COVID tailwinds, including a historic MRO (services) surge, a rapid LEAP production ramp-up, supply chain normalization, exceptionally high engine utilization, and strengthening defense demand.
Most important here is the steep recovery in air travel in recent years to levels above 2019 (pre-COVID). Simply put, more flight hours lead to more engine service activity, which drives a recovery in MRO (Maintenance, Repair, and Overhaul) revenue, also boosted by postponed shop visits during the 2020-2022 period. On top of that, Boeing and Airbus are struggling to keep up with demand, as air travel has fully recovered and new jets are not being delivered fast enough. As a result, airlines are stretching the utilization of existing fleets, accelerating engine wear, and giving MRO another boost. And with this making up the majority of revenue, this is an important growth driver.
These tailwinds ultimately drove 22% growth in service revenue in Q2 and 34% in the first half of the year.
Of course, these dynamics should normalize in due time, with these tailwinds not permanent, but these are now proving slightly more durable than anticipated, although we should see a normalization kick in more strongly in the second half.
Besides services, GE’s hardware shipments have arguably been even more impressive. Demand is high right now, and as GE works through supply chain constraints and air travel booms again, it is able to deliver significant growth in engine deliveries, with total engine deliveries up 31% in the first half, driven by 41% growth in LEAP deliveries.
Those are hugely impressive numbers, enabled by significant supply chain improvements that have grown output. Through its FLIGHT DECK playbook – its version of Toyota’s “lean manufacturing” system for the auto industry – it has achieved significant improvements in recent years. Take a 50% reduction in lead time for 56 final assembly processes, bringing down total shop visit turnaround times by about a week since the end of 2025. Another example is the reduction in overall production lead time for a critical component by roughly 60%, supporting 50% growth in F110 deliveries in Q2.
Simply put, supply chain improvements through its FLIGHT DECK system are directly enabling it to increase output and reduce process lead times, translating into improved customer satisfaction (shorter time-of-wing) and strong growth in engine shipments.
This is an important enabler of current momentum, and there is still plenty of room for improvement.
Let’s then break down the result by segment. Starting with CES, the commercial business, revenue in Q2 was $9.7 billion, 77% of total revenue, and up an impressive 27% YoY. This was primarily driven by 30% growth in equipment (engine) revenue, with units up 26%, including 24% growth in LEAP. Also, wide-body deliveries were up 30%, with the GE NX up significantly more. So really, strength across the product catalog.
For reference, LEAP is the engine family made by CFM International — the 50/50 joint venture between GE Aerospace and France’s Safran. It is effectively the workhorse of modern narrowbody aviation, powering the Airbus A320neo and the Boeing 737 MAX. And demand for it is huge, with the installed base expected to double between now and 2030, helped by an edge over the competing Pratt & Whitney GTF, which is really the only alternative, and huge demand for single-aisle jets, way more than wide-body jets.
Take Riyadh Air’s recent commitment for 120 LEAP engines, Pegasus Airlines’ commitment for up to 300 LEAP-1B engines, American Airlines’ agreement for more than 300 LEAP-1A engines, and a long-term materials deal with Ryanair covering roughly 2,000 CFM56 and LEAP engines. LEAP’s dominance puts GE in a very strong position.
What is worth pointing out is that LEAP was dealing with some reliability issues, focusing on fine airborne particles getting ingested during takeoff and, over time, in hot and harsh environments, working their way into the engine core, wearing down components and degrading efficiency and durability. The same issue plagued the Pratt & Whitney GTF, but whereas P&W’s response is a fleet-wide recall, GE’s (CFM International) fix for the problem is an aftermarket upgrade in the form of a durability kit, which should more than double the interval between shop visits under demanding operating conditions, with the goal of bringing LEAP-1A maintenance cycles in line with the CFM56 — the LEAP’s predecessor engine, which set the industry standard for long time-on-wing.
So far, the roll-out of the durability kits is well underway, making it once again the industry standard for reliability and time on wing. That is a very good development.
Most importantly, apart from a 30% growth in equipment revenue, service revenue, which makes up 75% of CES revenue, was up 26% in Q2, with internal shop visit revenue up 25% due to higher volumes, including 50% LEAP growth from the durability kits rollout. Spare parts sales were up 25%, helped by improved material availability, which allowed it to meet strong customer demand.
Ultimately, commercial services revenue was up 32% in H1, with record internal shop visit output in the second quarter and first-half total engine deliveries up 31%, including LEAP engines up 41%. Those are just sublime numbers.
Moving to DPT, the defense segment, revenue was up 16% in Q2 to $3.4 billion, accounting for a much smaller share of the total business. Defense & Systems revenue (engines and integrated systems for fighter jets, helicopters, and other defense platforms) was up 12% YoY, driven by growth in both services and equipment, with engine deliveries up 7%. Propulsion and add technologies grew 23%, driven by strong performance from Avio Aero, GE’s Italy-based subsidiary, which produces military engine components, some commercial/marine engines, and gearbox technology.
Across the DPT portfolio, GE continues to see robust demand both domestically and with Allied partners.
Finally, let’s address orders, which were up 17% YoY to $16.5 billion, reflecting a group book-to-bill of 1.31, which is excellent, even if down from peak levels in recent quarters. Really, any book-to-bill above 1 is great, indicating that GE is taking in more orders than it is generating revenue and leaving room for long-term growth. And GE’s number is consistently well above 1.
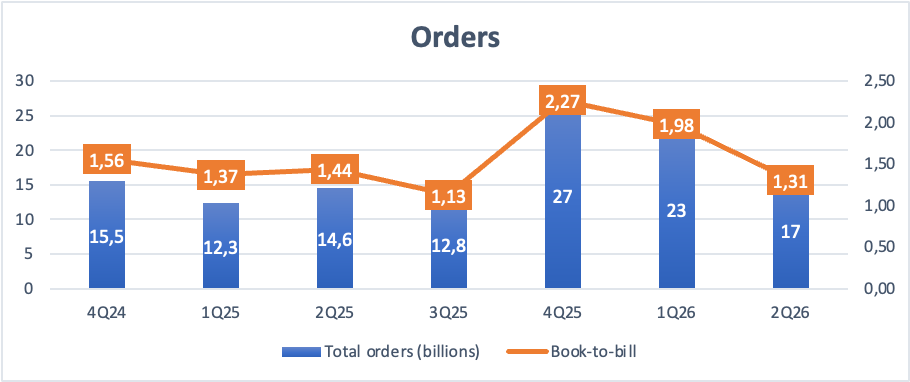
CES orders in Q1 were up 18% YoY and DPT 12% YoY, with a defense book-to-bill of 1 in Q2 and 1.7 in H1, which is healthy.
This strong order intake meant GE ended Q2 with a commercial services backlog of $170 billion and a DPT backlog of over $30 billion, up $5 billion since the start of the year. The total backlog stood at a whopping $210 billion, providing GE with a huge growth runway.
Ultimately, GE closed out the first half of the year with exceptional numbers. It delivered 49% YoY growth in orders and 27% YoY growth in revenue, signaling strong execution and unmatched demand.
We really can’t wish for much more. As a shareholder, I am really pleased with these numbers.
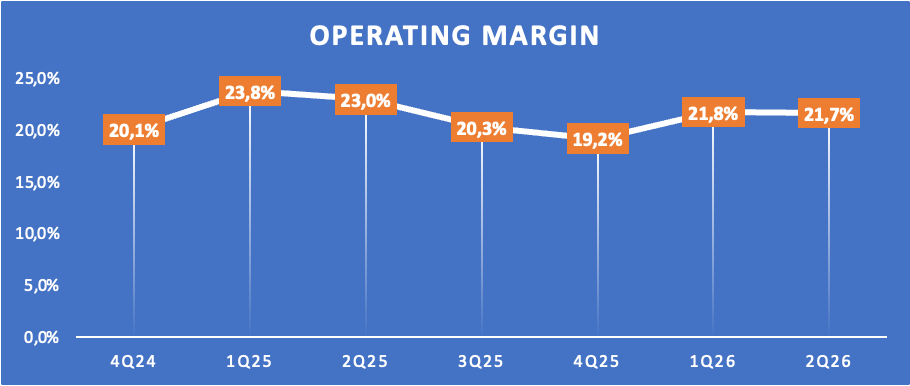
Moving to the bottom line, GE reported an operating profit of $2.7 billion, up 18% YoY and reflecting an operating margin of 21.7%, down 130 bps YoY. Driving this operating margin decline was mainly rapid equipment revenue growth, which well outpaced services, and, since equipment margins are significantly lower, this mix shift was a drag on the operating margin. On top of that, the LEAP and 9X production ramp continues to be a margin drag, with losses likely peaking in 2028, leaving room for margins to improve thereafter. So, no real structural problems are causing the lower margins, more so timing.
Moving further down the line, Q2 EPS was $2.02, up 22% YoY and beating the consensus by $0.16. EPS outpaced the operating profit thanks to a lower tax rate and a reduced share count. To be precise, a higher operating profit contributed 85% ($0.31) of the improvement in EPS, the tax rate was down 2 percentage points to 16.7%, and the share count was down by 24 million.
Finally, Q2 FCF totaled $3 billion, up 43% YoY, driven by higher earnings and a nearly $200 million reduction in working capital and AD&A, as well as some tariff favorability. This reflects an excellent 24% FCF margin, the best since the split in late 2024. The TTM FCF margin now sits at 17%, up from 16% in 2025 and 10% in 2024, showing healthy improvements despite margin pressure.
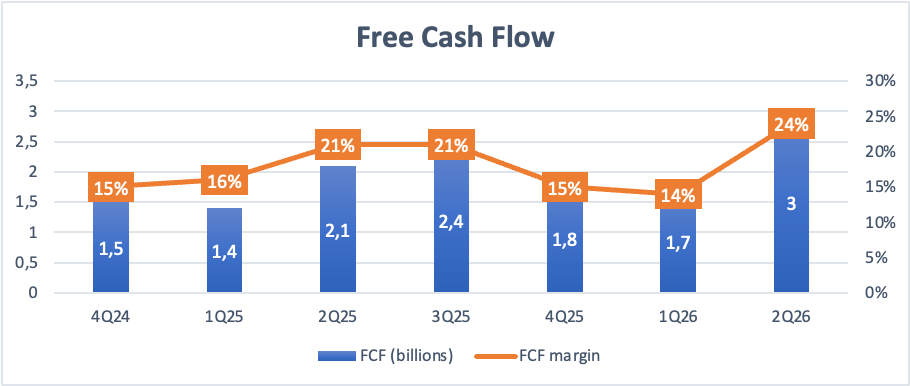
Thanks to these excellent cash flows, GE maintains a healthy balance sheet. It ended the quarter with $9.4 billion in total cash and $19.2 billion in debt, which is down $2.3 billion from the start of the year. Net debt at the end of Q2 stood at $9.8 billion, which is healthy, especially given GE’s improving cash flows. Sure, net cash would be preferred from a financial health standpoint, but given that GE is now generating $9 billion in FCF annually, debt is more than manageable.
This also allows management to remain opportunistic with its capital returns to shareholders. GE raised its dividend by an impressive 31% earlier in the year, with shares now yielding 0.54% based on a 23% payout ratio. Additionally, GE has bought back a significant amount of its own stock, reducing its share count by over 2% YoY in every quarter since the spin-off in late 2024.
On a final note, GE’s reinvestment metrics also still deserve highlighting, having trended up consistently since 2021. The TTM ROIC now sits at 22% and the TTM ROE at 46%, both very strong numbers that highlight management’s ability to deploy its cash and generate shareholder value.
Overall, it was simply an excellent quarter.
More content like this? Consider InvestInsights Premium
InvestInsights Premium is designed to help you find best-in-class compounders, identify deep-value opportunities, avoid costly mistakes, and stay focused on fundamentals when markets get noisy, with full transparency into how I make decisions over time.
In practice, this gets you:
6–8 Research Reports per month, 2x more than free subs do, which includes 3-4 Deep Dives!
Full visibility into my personal portfolio, including allocations, transactions, and conviction levels
An overview of target prices and ratings, updated weekly, all available in a web-based Hub.
Price tag? Only $95 per year or $9.50 a month. That comes to just $1 per analysis, with the rest provided at no cost.
Sound useful? You can upgrade to Premium today using the button below!
Outlook & Valuation
Following a strong first half of the year and ahead-of-expectations demand trends, GE management raised the 2026 outlook across the board, with the expectation that second-half departures will return to modest growth after a flat first half due to the conflict in Iran and subsequent high kerosene prices.
Therefore, management now guides to high-teens revenue growth, up from a prior low-double-digit range. This includes 20% CES revenue growth, supported by services revenue growth in the low 20s, a big raise from prior expectations, helped by the fact that third-quarter planned engine servicing exceeds the prior guidance by over 40%, giving management good visibility.
This likely indicates that management remains fairly cautious with this updated guidance. For reference, guidance implies just 12% service growth in H2 compared to 30%+ in H1, which seems like a dramatic slowdown. Sure, we are likely to see moderating growth given easing tailwinds and tougher comparables from a very strong H2 last year, but management still seems to be lowballing.
Meanwhile, commercial equipment revenues are expected to also grow by around 20%, with LEAP deliveries likely up in the high teens. And DPT is now forecast to grow revenue in the low-double digits, up from mid-single to high-single digits previously.
On the bottom line, management now expects the operating profit to be in a range of $10.55 billion to $10.75 billion, driven by higher revenue, partially offset by higher equipment growth. Still, this should allow for a FY26 EPS in the range of $7.65 to $7.85, up $0.35 at the midpoint from previous guidance, reflecting higher profits and a lower tax rate. Finally, management also raised its FCF guidance to $8.9-$9.2 billion, up $650 million from the high end of the prior guidance, reflecting a better working capital performance.
That is very solid guidance, sitting well ahead of consensus expectations, including my own. And I still think that is management applying a fair share of caution.
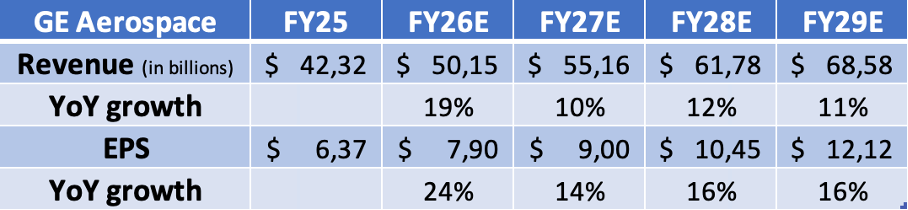
With that, let me get to my own updated financial forecast. Following the strong H1 performance and guidance update, I now expect GE to deliver FY26 revenue of just over $50 billion, reflecting 19% YoY growth. This is up significantly from my prior forecast of just under $47 billion, driven by strong momentum in both equipment and services, which held up better than expected. On the bottom line, I expect EPS to come in just above the high end of management’s guidance, driven by upside in revenue.
Looking ahead, I am quite cautious about 2027. I am still unsure about the potential implications of lower-than-expected air travel activity in H1, which might lead to some repairs and service being pushed out. Layer that on top of incredibly hard comparables and tailwinds losing steam, and conditions normalizing, and we get a pretty rough year. However, even under these conditions and taking a conservative approach, I believe GE can maintain double-digit growth.
I expect growth to then reaccelerate in 2028 and stabilize in the low-teens, driven by growing defense budgets and strong commercial demand. We will likely see equipment growth ease into the high-single digits, but I expect service revenue to still grow in the low- to mid-single digits through 2030. For reference, management expects shop visits to maintain a 25% CAGR through 2030, purely a function of the existing installed base needing servicing. Beyond 2030, I believe high single digits are a reliable assumption.
On the bottom line, as discussed, GE will face some margin pressure from the LEAP and 9X ramp through 2028, but I expect easing equipment growth and, subsequently, revenue shifting more toward services again to support healthy margin expansion from today’s moderate levels, still allowing for expanding margins in 2027 and 2028, likely accelerating from 2029 onward as cost pressure eases. By my estimates, this should allow for mid-teens EPS growth through 2030, likely easing to the low-teens beyond that.
These assumptions are reflected in the revised financial framework below!
That brings me to valuation, and, as so often, this is where it gets tricky, with GE consistently demanding hefty multiples given its quality. Additionally, GE shares have been a strong performer in recent months, jumping from sub-$280 per share in April to $349 today – shares are up 34% over the past year and 13% YTD. As a result, at a current price of $349, shares trade at:
44x 2026 earnings
41x 2026 FCF
Clearly, GE deserves a good premium – a business of this quality and reliability never comes cheap. I mean, as explained, GE sits in a structural oligopoly position with genuine, decades-long switching costs; it generates over 70% of revenue from service contracts locked in through long-term contracts regardless of new engine sales in any given year, and its financials look good, with excellent reinvestment metrics and a healthy balance sheet. It is forecast to grow its earnings at a mid-teens rate into the 2030s and is well positioned to continue compounding at a good rate for decades to come.
That is quite incredible.
And that level of quality, visibility, and demonstrated execution will always come at a premium, one that the company has the durability to grow into, so I don’t mind paying it right here. However, there’s a difference between paying a fair premium for quality and paying a price that already assumes everything goes right for the next several years. At 44x 2026 earnings and 41x FCF, there really is no margin of safety anymore.
And GE isn’t without risk. I mean, we still have considerable losses from the 9X rollout, the risk of reliability issues, and a combination of very tough comparables in the next few years while tailwinds ease, which could put pressure on the growth the street assumes, probably expects to outperform.
In other words, I don’t like the risk-reward I am seeing, despite the quality of the business and its ability to grow into a premium multiple. Say we assume a 40x earnings exit multiple for 2028, reflecting some contraction toward its 5-year median, and it is about the highest multiple I am willing to pay for future earnings. I mean, it is still incredibly expensive, but assuming GE can continue to deliver high-single-digit revenue growth and low-to-mid-teens EPS growth beyond 2030 (and I think it absolutely can), then that multiple seems very reasonable, even leaving room for some expansion.
Taking this multiple and my 2028 EPS, I calculate an end-of-2028 target price of $418. From a current share price of $349, this implies annualized returns of roughly 8%, including dividends. That is well below my 15% threshold and does not reflect a compelling risk-reward without significant outperformance, which I think isn’t easy to come by.
Therefore, I am not compelled to add to my position at this point. Personally, I am looking for a share price below $300 again before I would consider buying more GE, as that would raise expected returns toward 15%, making the risk-reward much more compelling.
For now, I am happy to hold on to my shares at a cost base of around $290, but I am not buying.
Rating + fair value: Hold — Accumulate below $300
2028 Target Price: $418
Implied CAGR from current price: ~8%
Please leave a like if you enjoyed this post and found it valuable!

Finally got a chance to read - excellent breakdown!
It's a good company to invest.