

Every time a plane takes off, the engine maker collects the quiet “tax” on global mobility. Not once, but repeatedly, for decades. And in commercial aviation, where reliability is existential and switching costs are borderline absurd, that “tax” is about as close as you get to an industrial annuity.
GE Aerospace sits right in the middle of that profit pool, not as a niche supplier, but as the dominant force behind a huge portion of the world’s flights. The result is a business that looks cyclical on the surface (planes, travel, airlines) but behaves far more like a compounding machine underneath, powered by long-term service contracts, recurring maintenance events, and a massive installed base that can’t be recreated overnight.
What makes GE especially interesting today is that it’s no longer hidden inside the old GE conglomerate. After the breakup in 2024, the company that remained wasn’t “GE the conglomerate” at all; it was GE’s best asset wearing the family name.
That matters because the aerospace industry is not a typical industrial market. It’s a concentrated, high-barrier, long-duration industry where the real economics don’t come from selling engines at the factory gate, but from owning the lifecycle: the parts, the upgrades, the shop visits, the performance optimization, and the decades of service revenue that follow.
In that world, scale becomes self-reinforcing. More engines in service means more data. More data means better predictive maintenance and lower downtime. Lower downtime means happier customers. Happier customers mean more engine selections. And once an airline standardizes, it rarely switches unless something breaks, literally or figuratively.
That’s why this is a fascinating equity story. GE checks nearly every “dream industrial” box: an oligopoly market structure, mission-critical products, deep customer lock-in, inflation-resistant services revenue, and long-term secular tailwinds from both commercial aviation growth and rising defense budgets. And the market, unsurprisingly, has noticed, pricing GE more like a luxury compounder than a standard industrial.
So, the real question isn’t whether GE is a great business. It clearly is, as I’ll show you in today’s Deep Dive. The question is whether the stock offers attractive long-term returns from here, or whether we’re looking at a classic case of a wonderful business meeting a valuation that already assumes a lot of wonderful things keep happening.
This is my General Electric Aerospace Deep Dive. Let’s break down this wonderful business from top to bottom!
Welcome to InvestInsights — an independent equity research publication rooted in long-term, buy-and-hold investing, publishing actionable stock/equity research reports weekly!
📈 You’re reading my latest [FREE] stock analysis. If you like this analysis, make sure to like & subscribe to receive much more like this!
If you’d like full portfolio access (16% CAGR since 2022) & additional exclusive analyses, consider becoming a paid subscriber!
This is General Electric Aerospace
Business breakdown + model
Headquartered in Cincinnati, Ohio, GE Aerospace is widely regarded as one of the most technologically capable and strategically important aerospace companies in the world. GE Aerospace is a leading global provider of aircraft propulsion systems, avionics, and services, operating as the successor to the aviation division of the former General Electric conglomerate, with a dominating presence in both commercial and defense aircraft engines.
Back in 2024, GE Aerospace was the final step of General Electric’s multi-year plan to dismantle the conglomerate and create three independent, industry-focused companies. The process unfolded in stages: GE HealthCare was separated in early 2023, GE Vernova (energy businesses) and GE Aerospace completed the split on April 2, 2024. From that moment, GE Aerospace became the remaining GE, publicly traded under the ticker GE.
The rationale behind the breakup was to simplify GE’s structure, reduce debt, sharpen strategic focus, and allow each company to pursue capital allocation tailored to its industry. For GE Aerospace, the spin-off formalized its identity as a pure-play aviation and defense propulsion company, free from the financial drag and complexity of GE’s legacy businesses.
Most importantly, it retained GE’s most profitable and strategically important operation: the aviation engine business.
Today, GE Aerospace designs and manufactures jet engines for commercial and military aircraft, powering a majority of the world’s commercial fleet through long-standing programs such as the GE90, GEnx, and CFM International’s LEAP engines, the latter produced through its highly successful joint venture with Safran Aircraft Engines, giving it an extensive portfolio spanning widebody and narrowbody platforms, business aviation, regional jets, and a deep presence in rotorcraft and combat aircraft propulsion.
The company is an absolutely dominant force. Whether you step into a Boeing or Airbus plane next time you go on a business trip or a vacation, odds are that the aircraft uses GE Aerospace engines under its wings, since it dominates roughly 75% of the active commercial fleet. In other words, ¾ of the world’s commercial planes use GE engines.
This fleet totals 78,000 engines and continues to grow. These engines have accumulated over 2.3 billion flight hours across seven certified commercial engine programs over the last 20 years.
In this aerospace vertical, GE is as dominant as it gets.
Meanwhile, the company also has a good presence in defense. Roughly 80% of revenue comes from commercial revenue, with the remaining 20% coming from defense contracts.
For defense customers, GE offers propulsion for fighters (including the F-16), transport aircraft, and helicopters, along with technical support, upgrade programs, and decades of experience working with military operators. GE Aerospace is a critical supplier to the U.S. Department of Defense and allied nations.
Alongside propulsion, GE Aerospace also provides integrated systems, including flight management, electrical power systems, and advanced digital solutions that help airlines and defense customers improve safety, efficiency, and fleet availability.
So, simply put, GE Aerospace offers airlines and militaries the engines that power their aircraft. That is its main business model. Yet crucially, it’s the operations after the initial sale that generate most of the company’s revenue.
The relationship with customers goes far beyond the initial sale. GE becomes a long-term partner responsible for the performance and upkeep of those engines throughout their entire lifecycle. GE monitors engine health in real time, helps airlines optimize performance, and provides maintenance, spare parts, and overhauls when engines need work. Because downtime is costly, airlines rely on GE to keep their fleets in the air, and GE’s deep data and predictive analytics allow customers to prevent problems before they occur.
As a result, GE makes money in two main ways: by selling new jet engines and by servicing those engines over their multi-decade operating life. The second part, services, is by far the larger and more profitable part of the business.
First of all, GE sells engines to aircraft manufacturers like Boeing and Airbus, as well as to military programs. These engine sales are often low-margin or even sold at close to cost, because the industry’s economics depend on what happens afterward. Once an engine enters service, it generates a long stream of high-margin revenue through maintenance, repairs, spare parts, and long-term service agreements. Since a modern jet engine can remain in service for 20 to 30 years, this creates a powerful recurring-revenue model that is extremely reliable.
These services typically account for roughly 70% of total revenue, reflecting the size of its installed base and the intensity of engine maintenance needs. The remaining 30% comes from original equipment sales.
The margin profile is skewed heavily toward services, which are far more profitable than engine sales. The split is therefore best understood this way: GE uses new-engine production to grow its installed base, and that installed base becomes an annuity of recurring service revenue. The bigger the fleet of GE engines flying around the world, the bigger the long-term cash flows. This lifecycle model (build engines, place them into service, and earn high-margin revenue for decades) underpins almost all of GE Aerospace's financial strength today, especially since these service revenues are based on long-term, inflation-resistant contracts that span the entire multi-decade engine lifecycle.
The value of this model cannot be overstated: once an airline commits to an engine platform, switching would be operationally disruptive and financially punitive. This creates long-term customer lock-in and a recurring revenue stream that has historically produced exceptional returns.
That is an incredibly powerful business model!
Market share & competitive environment
Competition in aircraft engines is unusually concentrated, technologically intense, and shaped by decades-long product cycles. Only a handful of companies worldwide have the capital, engineering talent, certification experience, and supply-chain depth required to design and support large turbofan engines. As a result, GE Aerospace, Safran (via CFM), Pratt & Whitney (RTX), and Rolls-Royce form a quasi-oligopoly, with each player strong in different segments.
Across all segments, competition is driven by engineering capability and lifecycle economics far more than price. Developing a new large turbofan costs billions of dollars, takes years of certification work, and exposes companies to enormous financial risk if reliability falters after entry into service. As a result, the industry tends to avoid excessive fragmentation. Airlines, airframers, and governments prefer proven partners with deep service networks and long track records, which reinforces the dominance of the existing players.
This competitive landscape benefits GE. Among these four, as alluded to before, GE is by far the most dominant, in part through its Safran partnership, with three out of four commercial flights powered by its engines.
Breaking this down slightly further, in the high-volume narrowbody segment (single-aisle jets, e.g., the A320 family and 737 series), about 72% of the worldwide active fleet is equipped with GE’s CFM engines. Meanwhile, in the widebody segment (twin-aisle, long-haul jets), around 52% of in-service aircraft use GE engines, and this market share is holding steady, with 54% of the widebody aircraft orders equipped with GE engines.
In narrowbody aircraft, GE, through its Safran partnership, practically only faces competition from Pratt & Whitney. Airbus offers both engine options on the A320neo, but the LEAP (from CFM) has outsold the PW1100G (Pratt & Whitney) by a wide margin due to better reliability, lower operating cost, and fewer early-in-service issues. Boeing’s 737 MAX uses only the LEAP, which means GE/Safran controls the entire propulsion market for Boeing’s most important aircraft.
Because narrowbodies dominate global airline fleets and account for most flying hours, this segment provides GE and Safran with unmatched scale and recurring service revenue.
The widebody market is more contested and varies by platform. GE is the sole-source supplier for the Boeing 777 and 777X with the GE90 and GE9X, and it holds a major share of the Boeing 787 market with the GEnx. Rolls-Royce, meanwhile, dominates the Airbus A350 and has a strong position on the A330neo. Widebody engines are fewer in number but technologically demanding and highly profitable over their lifecycle. Competition here is less about winning every platform and more about securing monopoly positions on select aircraft, because sole-source contracts create decades of service revenue.
While GE is less dominant here, especially thanks to its Boeing relationship, it still captures over 50% of the market, making it a dominant player.
As is probably clear by now, a defining factor in GE’s commercial success has been its joint venture with Safran, CFM International. The partnership proved uniquely effective because it blended GE’s high-power-turbine expertise with Safran’s compressor and manufacturing strengths. When the CFM56 became the de facto standard for Boeing 737s and major Airbus A320 operators, GE gained an enormous installed base that expanded predictably for decades.
The follow-on LEAP engine, adopted for the 737 MAX and A320neo, reinforced this position and ensured that GE-powered aircraft dominated the highest-traffic segment of global aviation.
Beyond scale and customer integration, GE’s moat is also reinforced by its technological leadership, exclusive program positions, and unmatched global service infrastructure. Jet engines sit at the edge of what materials science and thermodynamics can achieve, and GE’s long history of pioneering advances, from ceramic matrix composites to advanced cooling architectures and additive manufacturing, gives it a performance and efficiency edge that competitors struggle to match.
This technological credibility is a key reason Boeing has repeatedly selected GE as the sole-source engine supplier on platforms like the 777 and 777X, effectively locking competitors out of these programs for decades and guaranteeing GE a multi-decade stream of high-margin service revenue. That service ecosystem itself is another formidable barrier: GE’s global network of certified repair shops, proprietary parts, deep telemetry datasets, and predictive-maintenance tools creates lifecycle economics that no rival can easily replicate.
Even if a competing engine matches GE on paper, replicating this aftermarket infrastructure would take decades. Together, these technological, contractual, and infrastructural advantages deepen GE’s competitive position and make its already dominant share extraordinarily difficult to erode.
Jumping a little deeper into competitive dynamics, the strength of this existing infrastructure cannot be overstated. Once an airline commits to an engine platform, switching becomes operationally disruptive and financially punitive. Maintenance routines, spare-part inventories, crew training, digital diagnostics, and flight-planning tools are all built around the chosen engine.
This creates long-term customer lock-in and a recurring revenue stream that has historically produced exceptional returns. It is one of the reasons GE’s customer relationships are among the strongest in the entire industrial world. Airlines depend on GE not only for propulsion, but for reliability, planning, and operational uptime, effectively making GE a long-term partner for the full 20- to 30-year life of an engine.
This integration is just as strong with Boeing and Airbus. Airframe manufacturers must commit to engine partners years before an aircraft ever enters service, and GE’s consistent execution, certification record, and engineering collaboration have made it a trusted partner. The same dynamic holds on the military side, where decades of powering fighters, transports, and rotorcraft have entrenched GE as a preferred supplier in the U.S. and allied defense ecosystems.
These relationships are reinforced by the scale of GE’s installed base. With roughly 78,000 engines in service and more than 2.3 billion accumulated flight hours, GE has an operational track record that competitors cannot match.
In aviation, trust is earned through real-world performance: engines that behave predictably, wear as expected, and maintain reliability across millions of flights and every type of operating environment. This empirical history strengthens GE’s credibility with airlines, airframers, leasing companies, and regulators. It also enhances resale values and reduces perceived risk when customers consider future engine selections.
The size of this installed base also powers GE’s data advantage. Every flight hour generates telemetry that feeds predictive-maintenance algorithms, improves cost forecasting for customers, and guides GE’s next-generation engine designs. Competitors with smaller fleets simply do not have access to a comparable depth of data, limiting their ability to match GE’s diagnostic accuracy and lifecycle optimization. Over time, this creates a compounding advantage: the more engines GE has in service, the better its models become, and the more indispensable GE becomes to operators.
All of this creates a structural moat that is extremely difficult to dislodge. GE is not merely a supplier but a deeply embedded partner in global aviation.
Given this backdrop, GE Aerospace is well-positioned to maintain, and in some segments, modestly grow its market share over the next decade. It is likely to retain and grow dominance in narrowbodies, driven by the scale of the CFM partnership and continued preference for the LEAP over Pratt & Whitney’s GTF, which has faced reliability challenges. In widebodies, GE’s share should remain stable, with strong positions on Boeing programs offsetting more limited opportunities at Airbus. On the military side, GE’s share is durable, with potential upside from future fighter programs and international modernization cycles.
The only meaningful long-term competitive threat would be a disruptive propulsion technology cycle where a competitor delivers a step-change in performance or environmental efficiency. But GE is already investing heavily in open-fan architectures, hybrid-electric systems, and next-generation materials, making such a leapfrogging event unlikely.
In the near to medium term, the company’s market position is structurally supported and highly resilient, with major share losses appearing improbable under current industry dynamics. In fact, given its dominance in narrowbody aircraft, being the highest-volume and fastest-growing category, I see room for gradual market share gains in the overall market over the next decade.
Industry growth
Turning to the underlying market, GE Aerospace operates in one of the most attractive demand environments in industrials.
Global commercial aviation is expected to keep expanding for decades as population, GDP, trade, and urbanization rise. Airbus’s long-term forecast sees passenger traffic growing significantly through 2044, which, in practice, means more routes, more frequencies, and ultimately more aircraft in the sky.
That demand is already visible in the fleet numbers. The global commercial fleet is projected to grow from roughly 29,000 aircraft in 2025 to about 38,300 by 2035, an increase of around 32%. Over the next 20 years, the fleet is expected to almost double, driven primarily by additions rather than replacements. Only about a fifth of today’s aircraft are still expected to be flying in 2044.
As a result, Airbus anticipates more than 43,000 new aircraft deliveries over that period, most of which will be incremental capacity rather than simple one-for-one swaps. Every one of those aircraft needs at least one, and usually two, engines, and each engine will generate decades of future servicing revenue.
Moreover, behind these fleet numbers sits a powerful demographic driver: by 2044, the global middle class is expected to grow by roughly 1.5 billion people. These are households that may not fly weekly, but can now afford to fly occasionally for holidays, family visits, or business. That incremental demand is especially concentrated in high-growth regions like Asia and the Middle East, which are already investing in larger, younger fleets. As airlines in those regions scale up capacity and utilization, they become long-duration demand engines for aircraft manufacturers and engine OEMs.
The composition of the fleet matters as much as the growth rate. Narrowbodies have become the workhorses of global aviation, favored for their fuel efficiency, lower trip cost, and flexibility on short- and medium-haul routes. Narrowbody fleet growth is expected to run around 2.8% to 3% per year, supported by strong 737 MAX and A320neo deliveries. As older aircraft are retired and replaced with these new-generation platforms, modern engines such as GE/Safran’s LEAP and Pratt & Whitney’s GTF benefit directly.
Furthermore, what really supercharges the economics of this industry is not just the number of aircraft, but how intensely they are flown. Airlines have been pushing utilization higher as travel recovers and OEM supply constraints limit how quickly they can add new capacity. Engines wear based on flight hours and cycles, not just how many exist in the fleet.
Higher utilization means more maintenance, more shop visits, and more parts. Industry forecasts point to engine MRO growing at roughly 3–4% per year through 2035, with engines taking a growing share of total MRO spend. As the fleet ages, that maintenance intensity rises further, creating a durable structural tailwind for engine makers with large installed bases.
Alongside commercial aviation, defense adds another structural growth leg. Global military spending has surged to record levels, reaching around 2.7 trillion dollars in 2024 and growing at close to double-digit YoY rates. This isn’t a one-off spike; it reflects a more fundamental shift in security priorities. The United States, Europe, Japan, and key Indo-Pacific countries are all increasing budgets, modernizing air forces, and investing in next-generation fighters, transports, and rotorcraft. Military fleets require both new propulsion systems and continuous maintenance and upgrades over very long-time horizons.
GE is positioned squarely in the middle of this trend. It already powers a substantial portion of Western fighters and helicopters, including F-16s, F-15s, Black Hawks, and Apaches, and is advancing adaptive-cycle engines such as the XA100 for future platforms.
Defense propulsion markets are expected to grow on the order of 3% to 5% annually, and GE’s installed base plus technology pipeline puts it in a good position to grow at or above that rate. Crucially, defense programs tend to lock in engine suppliers for decades, with revenues that are relatively insulated from economic cycles and often indexed to inflation.
Putting all of this together, the industry dynamics point to a multi-decade runway of growth in both new-engine builds and aftermarket services. The commercial fleet is expanding and renewing, utilization is high, engine MRO is growing steadily, and defense budgets are structurally elevated.
For GE specifically, that translates into expanding addressable markets in commercial engines, military engines, and services. Given these trajectories, a mid–single-digit to high–single-digit long-term revenue growth profile (roughly 7% to 9% CAGR) looks like a reasonable and defensible base case, especially amid the expectation for steady market share gains, as just established.
In other words, the long-term outlook for GE is looking quite brilliant. It should be able to deliver strong, compounding growth, driven by structural global trends that won’t budge, and supported by a massive active fleet and reliable, inflation-resistant service contracts that ensure decades of reliable revenue.
The model and backdrop for GE are exceptional for long-term investors.
Now that we have established the business model, industry dynamics, and the long-term dynamics, let’s move on to recent performance and financials!
GE Aerospace is firing on all cylinders
GE released its latest financial results – fiscal Q3 – on October 21, delivering excellent results that surpassed consensus estimates by a wide margin and raising full-year guidance, as business momentum remains phenomenal.
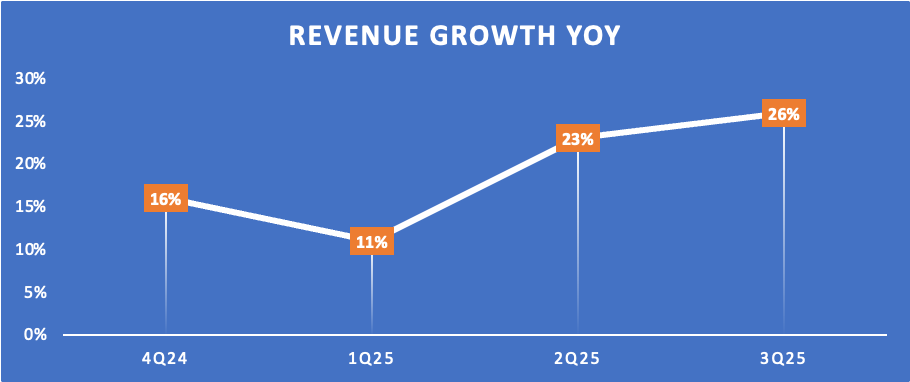
The company is seeing an extraordinary convergence of cyclical and structural tailwinds, driving exceptional growth across the business. Jumping straight into the numbers, GE reported Q3 revenue of $11.3 billion, up 26% YoY and surpassing consensus estimates by $890 million.
Obviously, 26% growth for such a mature business in an industry typically growing no faster than mid-to-high single digits is exceptional. This growth was driven by strength across the entire business, with strong deliveries across aftermarket, OE (original engines – new deliveries), and defense.
As highlighted below, last quarter’s 26% growth reflects a further acceleration from recent quarters, with business momentum still improving.
So, what is driving this standout performance?
As I said, it is a combination of tailwinds, including a historic MRO surge, rapid LEAP production ramp-up, supply-chain normalization, exceptionally high engine utilization, and strengthening defense demand. These conditions temporarily elevate growth well above GE’s long-term mid-to-high single-digit trajectory.
For one, there is the ongoing recovery from the COVID-19 pandemic, with flight hours now above 2019 levels, which in turn drives engine shop visits, parts consumption, and service revenue. Simply put, more flight hours lead to more service activity on the engines, which drives a recovery in MRO (Maintenance, Repair, and Overhaul) revenue, also boosted by postponed shop visits in the 2020-2022 period.
On top of that, Boeing and Airbus are struggling to keep up with demand, as air travel is fully recovered and new jets are not being delivered fast enough. As a result, airlines are stretching the utilization of existing fleets, accelerating engine wear, and giving MRO another boost.
When it comes to engine deliveries, GE is benefiting from a huge backlog of LEAP orders, which are now finally being converted into new deliveries. As demand is booming, Boeing and Airbus are increasing monthly build rates, and supply chain bottlenecks are mostly resolved, allowing GE itself to increase output.
And finally, while defense rarely grows faster than 5% annually, the recent push by NATO countries to increase spending and investment in their defensive capabilities is driving rapid growth for GE as well.
Again, it is a combination of structural and temporary factors coming together that drives today’s amazing growth.
GE’s Q3 numbers reflect these positive dynamics. Shop visit revenue increased 33%, and spare parts revenue increased 25%. And shop visits still remain below 2019 levels, so this recovery still has legs. For reference, “shop visits” refers to the event when an aircraft engine is removed from the wing and sent to a specialized maintenance facility for inspection, repair, or overhaul. In other words, it refers to engine servicing.
The fact that this is still below 2019 levels means that service revenue will continue to recover, driven by earlier-discussed dynamics. This is what drove 25% growth in service revenues in Q3 and 20% YTD. This is considerably better than the high teens growth management had guided toward. Accounting for 72% of revenue, this was and will continue to be a critical driver of growth. Management sees room for further ramping in 2026.
Meanwhile, growth was also driven by strong engine deliveries. Total deliveries were up 41% YoY, well above Q2 and the same quarter last year. GE has cleaned up many supply chain issues in recent quarters, but it still has work to do. It will invest another $1 billion in its supply chain to expand capacity and continue seeking operational improvements to increase output, as it is still not fully able to meet customer demand.
Exceptional engine delivery growth in Q3 was driven by all types, with 83% YoY growth in defense deliveries, followed by 33% in commercial, including 40% in LEAP. Year-to-date, commercial units are up 19%, with LEAP up 21%.
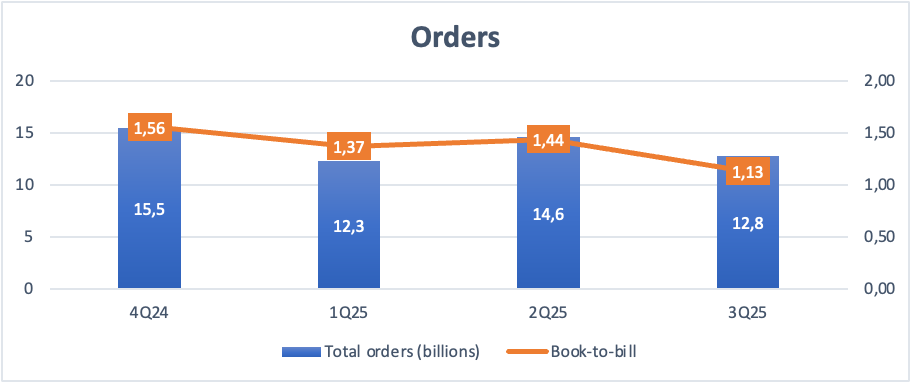
And finally, orders were also up 2% YoY, driven by strong momentum in commercial services, partially offset by the timing of equipment orders in commercial and defense. YTD, orders are up 13%, highlighting strong momentum. This is mostly driven by service orders, up 24% YoY, offset by a 6% decline in engine orders.
Most importantly, GE’s book-to-bill ratio since its 2024 split has consistently been above 1, meaning it has consistently taken in more orders than it has realized revenue, which is a strong long-term indicator.
As a result, the company now sits on a $175 billion backlog, helped by $12.8 billion in Q3 orders and $39.2 billion YTD.
Momentum across the business is just exceptional.
Breaking down revenue by end market, commercial performed very well, growing service revenue by 28% as improved material availability helped fulfill customer demand. This includes 33% growth in shop visit revenue from higher volume and 25% growth in spare parts revenue. Meanwhile, engine revenue rose 22% YoY, driven by 33% growth in deliveries. This led to total revenue growth of 27% YoY to $8.9 billion.
In defense, Q3 revenue rose 26% YoY to $2.8 billion, driven by higher output. Equipment revenues were up a whopping 53% YoY, driven by 83% growth in engine deliveries, somewhat offset by “just” 7% growth in service revenue.
All in all, GE’s Q3 results highlight a company operating with exceptional momentum.
On that note, let’s move to the P&L.
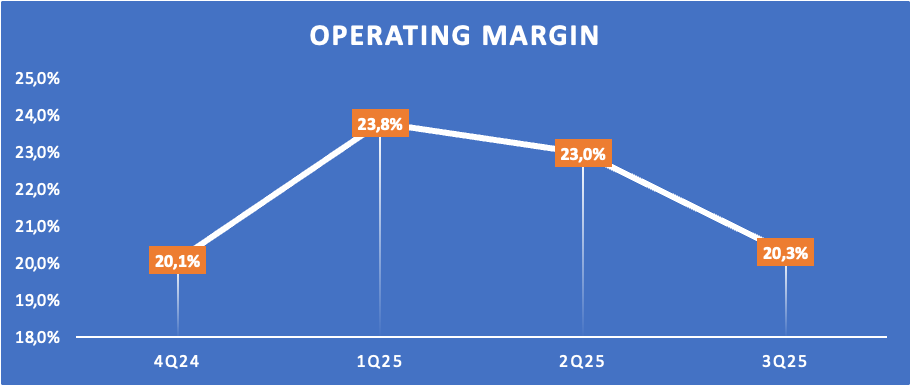
GE reported a Q3 operating profit of $2.3 billion, up 26% YoY and reflecting an operating margin of 20.3%, which was flat YoY. Strong high-margin service volume, a positive price mix, and productivity gains were offset by lower margin OE growth, higher investments, and higher corporate costs. The higher corporate costs were mainly due to the timing of reserves for environmental, health, and safety expenses, which will not recur to this extent.
Segment margins both expanded YoY, but were offset by the same timing of corporate costs. YTD, however, the operating margin is up 140 bps YoY, driven by 210 bps of segment margin expansion in commercial and 170 bps of margin expansion in defense, driven by strong results and subsequent growing operating leverage.
As conditions normalize in the coming years and low-margin engine revenue growth slows, I expect GE to steadily expand margins.
Moving further down the line, this resulted in an EPS of $1.66, up 44% YoY and beating consensus estimates by $0.19, driven by a higher operating profit, a lower tax rate ($0.10 benefit), and a reduced share count.
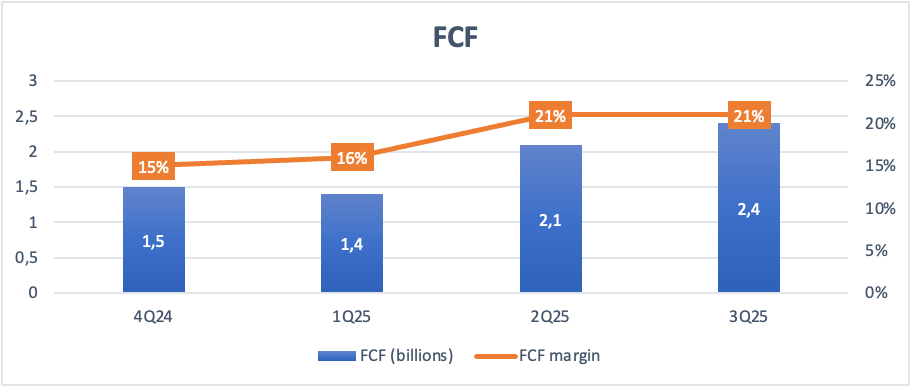
Finally, GE reported an excellent Q3 FCF of $2.4 billion, up 30% YoY, driven by higher profits and an over 130% conversion rate. This translates into an FCF margin of 20.3%, up 180 bps YoY. This brings TTM FCF to $5.9 billion, up nearly $1.3 billion at a 115% net income conversion.
Despite some cost headwinds and significant cost optimization still ahead, GE is already an exceptional FCF machine, on pace to deliver over $7 billion in FCF annually.
Meanwhile, the company clearly knows how to put this cash to work, as its reinvestment metrics are excellent. The company’s TTM ROE is 34%, and its ROIC is just over 8%. The latter has been trending up in every quarter since Q1 2024.
These are excellent numbers. And on top of that, the company maintains a healthy balance sheet. It ended Q3 with $12.5 billion in cash and $20.8 billion in debt, leaving it with manageable net debt and plenty of cash on hand. Especially given the $7 billion in cash it generates annually and the likelihood that this will grow to over $10 billion before 2030, this debt seems more than manageable.
This solid financial health also allows management to keep returning cash to its shareholders. In Q3 alone, management bought back $1.8 billion worth of shares, bringing the YTD total to $5.4 billion, and it is likely to return a total of $7 billion in 2025, retiring 2% of outstanding shares.
Additionally, the company pays a 0.46% dividend. While the yield in itself isn’t impressive, this is based on a conservative 22% payout ratio and has been growing at a 47% CAGR. Especially amid the outlook for strong, compounding earnings growth over the next decade, I view GE as a very compelling dividend growth stock, in addition to being a likely great, reliable long-term compounder.
Making up the balance, I am quite impressed with its recent performance. GE Aerospace is executing at a level that few industrial companies can match, translating exceptional demand conditions into accelerating revenue, expanding profitability, strong cash generation, and rising returns on capital. With a record backlog, robust service momentum, healthy financials, and disciplined capital allocation, GE sits in a position of considerable strength.
On that, let’s get to the outlook!
Want more out of your subscription? Even more content like this weekly? Consider InvestInsights PRO — $7.50/month ($70/annually)
PRO gets you:
A guaranteed minimum of 6-8 stock analyses every month (of which at least 3-4 are paid-exclusive).
Full insight into my own portfolio, including allocation, transactions, watchlist, and performance (16% annualized return since January 2022).
Instant transaction alerts anytime I buy or sell any shares (Fully transparent).
An overview of all my target prices and ratings (available online, updated weekly).
Access to the InvestInsights Hub, containing all of the above in a single online sheet, updated constantly!
Outlook & Valuation
As always, let’s start with management’s own commentary and guidance.
Following the blowout Q3 results, supported by brilliant business-wide momentum far ahead of expectations and expected to persist, management raised its FY25 guidance across the board by quite a bit.
Management now guides for FY25 revenue to be up by high teens, up from our prior outlook of mid-teens and likely well ahead of a 16% pre-earnings consensus. This will be supported by low-20s growth in commercial (up from high-teens), driven by much stronger service revenue growth and engine shipments mostly as expected. Additionally, defense is now expected to grow revenue by high single digits, up from prior mid-to-high single digits.
This is exceptional guidance, suggesting momentum will remain strong in Q4 and likely into 2026.
Thanks to this higher revenue guide, management also raised its operating profit guidance by $400 million at the midpoint to a range of $8.65 billion to $8.85 billion. This upside mainly comes from the strong commercial service revenue performance, which carries higher margins. This more than offsets higher corporate costs and eliminations of $1 billion.
Taken together, this is expected to result in an EPS of $6 to $6.20, up $0.40 at the midpoint, reflecting 33% YoY growth, and sitting ahead of a $5.92 pre-earnings consensus. Additionally, FCF is now expected to be between $7.1 billion and $7.3 billion, also up $500 million from prior guidance, driven by higher earnings.
Looking ahead to 2026, management still expects departures to grow by 3-4%, which is kind of a normalized and stabilizing rate, but shop visits will likely outpace this and remain firmly in the double digits, as the earlier-discussed tailwind will persist. This suggests another year of excellent service revenue growth, especially in the first half.
However, management also added that 2026 will not be a repeat of 2025, as conditions will start to normalize throughout the year, toward management’s targeted medium-term low double-digit growth. This seems fair considering COVID headwinds will ease, and it will start lapping last year’s recovery quarters.
Commercial momentum will likely remain quite strong, but will face some headwinds from higher engine shipments and easing service revenue, particularly in the second half. Meanwhile, defense should continue to grow in the mid-single digits, with some margin expansion and room for high-single-digit growth thanks to NATO investments.
Taken together (lower commercial margins due to engines + higher lower-margin defense revenue), management sees minimal room for margin expansion in 2026.
Furthermore, management hangs on to its 2028 targets, aiming for an operating profit of $11.5 billion, FCF of $8.5 billion, and an EPS of roughly $8.40.
Then, turning to my own projections, I am very bullish on GE’s prospects through 2030, as I expect headwinds to persist for most of these years, driven by a gradual post-COVID normalization, struggles at Boeing and Airbus, and structural headwinds that are driving growth in air traffic.
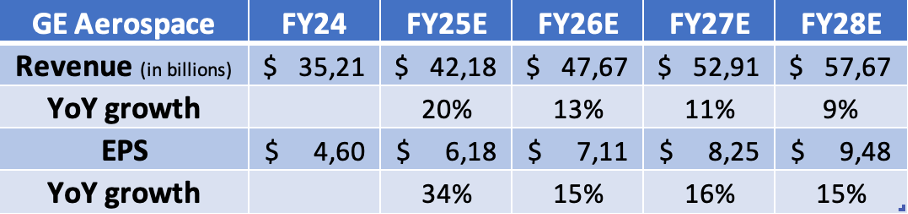
For 2025, I expect revenue growth of just under 20%, based on strong momentum expected to persist in Q4, and EPS growth toward the high-end of management’s guidance, given its conservative track record.
Looking ahead, I expect momentum to normalize throughout the years as YoY comparisons get tougher and tailwinds gradually ease. Nevertheless, I expect momentum to remain strong, with a projected 13% growth in 2026, 11% growth in 2027, and this to drop into the high-single digits through 2030, before stabilizing in the 7-9% range.
Meanwhile, I see plenty of room for GE to keep expanding margins, driven by a normalization of product mix (lower engine shipments) and growing operating leverage, driven by strong top-line growth. This should allow for gradual margin expansion, especially beyond 2026, when the business is expected to face some margin headwinds. As a result, I expect EPS growth to remain fairly stable in the mid-teens during the 2026-2028 period, before easing to the low-teens.
These assumptions are reflected in the forecast below.
That then brings us to valuation, and this is where it gets tricky, especially with shares up 81% over the last twelve months. Obviously, GE is an absolutely brilliant business, positioned to compound at a very strong, reliable rate for decades to come, driven by structural industry tailwinds, its dominance, and a massive moat – this is definitely one of the best stocks to own for decades to come.
However, this is exactly how it’s priced today. At a current share price of $315, GE shares trade at:
51x this year’s earnings and 44x next year’s.
46x this year’s FCF and 42x next year’s (expected) FCF.
This highlights that investors are already paying up for quality, and optimism around GE Aerospace appears largely priced in. Trading at roughly 51x current-year earnings and 44x next year’s, and more than 40x forward free cash flow, the stock reflects not just confidence in execution but an expectation that today’s exceptional momentum persists for an extended period. That is a high bar, even for a business of this quality.
While GE clearly deserves a premium multiple given its dominant market position, service-heavy revenue mix, inflation-resistant cash flows, and long runway for compounding, the current valuation leaves little room for normalization. As the post-COVID recovery effects fade, engine shipments weigh on margins, and growth rates gradually revert toward management’s medium-term low-double-digit targets, it is reasonable to expect valuation multiples to compress over time, even if fundamentals remain strong.
For a business like GE Aerospace, a low-40s earnings multiple arguably represents a more balanced long-term valuation. Such a multiple would still reflect its exceptional moat, visibility, and compounding characteristics, while better aligning with a normalized growth profile rather than peak-cycle momentum. Under this framework, long-term returns are likely to be driven more by earnings and cash-flow growth than by multiple expansion, with valuation acting as a modest headwind rather than a tailwind.
In other words, GE Aerospace remains an outstanding business and a highly attractive long-term compounder, but at today’s price, investors are paying upfront for that quality.
Suppose we use a 42x (earnings) 2027 exit multiple, which is the highest premium I can get behind, I calculate an end-of-2027 target price of $347. At the current price of $315, this suggests annualized returns of just 5%, which isn’t an attractive risk-reward at all.
In other words, too much optimism is priced into the shares at these levels. Yes, this is a business I would love to own, very much so, but only at the right price.
And so I’ll be patient on the sidelines. What price am I aiming for? I think a share price below $280 offers a much more compelling long-term risk-reward. This still reflects a hefty premium, but a business of this quality just doesn’t come cheap.
Rating: Hold - Accumulate below $280
FY27 Target Price: $347
Implied CAGR from the current price: 5%
Please leave a like if you enjoyed this post and found it valuable!

Great post, Daan! Thanks a lot!!!
Excellent write up; thanks for your efforts. Truly the gem to come out of the deconstruction of the old GE conglomerate. Chris Hohn at TCI was right to bulk up on this early.