

Back in April, I laid out exactly why I really liked Intuitive Surgical, the company holding an 80% market share in the global surgical robotics market, one of the most exciting and promising healthcare verticals.
For those who don’t know it yet, Intuitive develops, manufactures, and markets robotic-assisted surgical systems, combining advanced robotics, high-definition 3D visualization, and sophisticated instruments to enhance a surgeon’s precision, dexterity, and control, enabling them to perform complex operations through small incisions, thereby making procedures less invasive and more precise.
And this comes with a stunning business model, with the razor-and-blades economics underneath. You see, every system placement locks in a decade-plus annuity of high-margin, recurring instrument and accessory revenue that now makes up the vast majority of the business, so procedure growth (growing adoption of surgical robotics) compounds directly into recurring cash flow rather than one-off hardware sales. Roughly 85% of Intuitive’s revenue is therefore recurring in nature.
On top of that, Intuitive’s dominant position is protected by a huge moat, driven by an early-mover advantage that has allowed for technological dominance and a massive installed base of nearly 13,000 systems. Two decades of surgeon training and muscle memory create brutal switching costs; a dense patent thicket and FDA-cleared indication library keep competition at a distance; and the installed base itself becomes a flywheel — more systems mean more training programs, more clinical data, more hospital-system lock-in.
So, this is a business in a brilliant position for several decades of compounding as surgical robotics becomes the standard. And not only is the surgical robotics market one of the fastest-growing healthcare verticals, but despite its dominance, Intuitive has loads of potential to expand its TAM through equipment innovation to enter new markets, new indications, and international expansion.
However, no matter how much I like any business, valuation always matters, and Intuitive has historically always demanded a premium, with a 40-50x earnings multiple that is no standout. This is exactly why I concluded in April that I would remain on the sidelines at $473 per share, reflecting a near 50x earnings multiple, waiting for a more attractive entry point.
Last week, Intuitive released its second-quarter results, and even though the company beat consensus expectations, Intuitive shares lost 14% in the subsequent session amid outlook concerns, falling to their lowest level in 2.5 years, 42% below an early 2026 high, and well below my buy target from April.
So, plenty of reasons to update my thesis and view of the stock by breaking down the Q2 results and developments, before updating my financial model.
Let’s delve in!
This is a paid-exclusive analysis. Want full access? Consider upgrading to InvestInsights PRO for $9.50 a month or $95 a year! This gets you:
6–8 Research Reports per month, 2x more than free subs do, including 3-4 Deep Dives and 2 mid-week analyses (that comes down to just $1 per analysis)
Full visibility into my personal portfolio, including allocations, transactions, and conviction levels
An overview of target prices and ratings, updated weekly
InvestInsights Premium is designed to help you find best-in-class compounders, identify deep-value opportunities, avoid costly mistakes, and stay focused on fundamentals when markets get noisy, with full transparency into how I make decisions over time.
Financial & Performance Review
Intuitive Surgical released its latest financial results – Q2 2026 – just last Thursday, and delivered a solid report, beating consensus estimates and largely maintaining its full-year guidance. Really, Intuitive delivered good numbers across the board, continuing to grow its top line at a strong rate, and delivering strong margin expansion and excellent cash flows.
Starting at the top, Intuitive reported Q2 procedure growth of 16% YoY, driven by 15% growth in Da Vinci procedures and 36% growth in Ion procedures, reflecting a further slowdown from recent quarters in both total procedures and da Vinci procedures to the lowest growth rate in years.
Yes, that isn’t ideal and deserves attention, but let’s be clear: this isn’t a dramatic growth deceleration, nor is it unexpected. This slowdown was anticipated, being largely the result of external conditions outside of Intuitive’s control, specifically headwinds in China due to local policy and the expiration of certain subsidies in the U.S., both of which I will discuss later on. Above all, I will argue Intuitive’s growth rate is still excellent, still sitting in the mid-teens, largely in line with recent years, which is a strong performance from a huge base.
So, yes, growth is slowing from strong numbers in recent quarters, but as long as this doesn’t move much lower from here and remains in the low-teens range in 2026, I am quite pleased.
To provide some background for those not quite familiar with Intuitive, da Vinci, multi-port and single-port (SP), are Intuitive’s flagship surgical robots for minimally invasive soft-tissue surgery. A surgeon sits at a console and controls robotic arms that hold cameras and tiny instruments inside the patient, used for procedures like hernia repairs, hysterectomies, prostatectomies, and general/gynecologic surgery. Ion, by contrast, is a much smaller, catheter-based robotic system built for lung biopsies. It navigates thin, flexible tools through the airways to reach small nodules deep in the lungs for diagnosis, typically for early lung cancer detection, and doesn’t involve incisions the way da Vinci procedures do.
SP procedures were up 61% YoY in Q2, reflecting continued momentum in Korea and the U.S., driven by new indications and product innovation. SP remains a growth opportunity for Intuitive as adoption remains low and is ramping quickly. Ion procedures were up 36% YoY in Q2, with the system now installed in 12 countries outside the U.S., with adoption ramping quickly. Again, the runway is very long here.
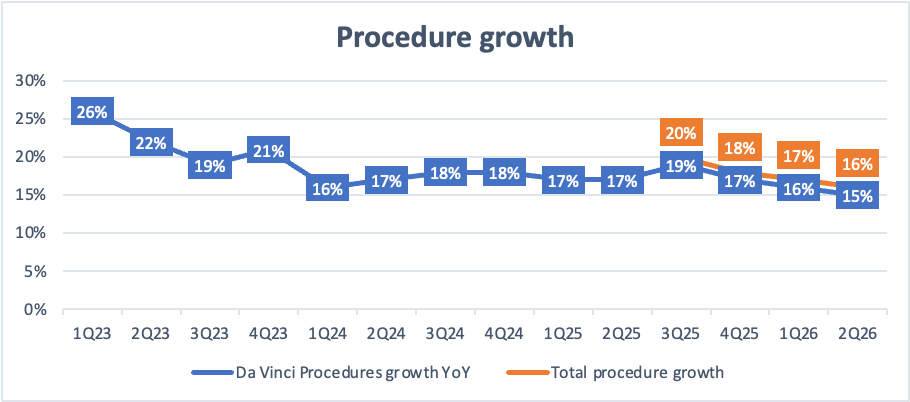
Breaking down procedure growth by regions, U.S. total procedures were up 13% YoY, driven by 34% growth in Ion and 12% growth in da Vinci procedures. Da Vinci growth was led by general surgery growth, specifically 26% YoY growth in after-hours procedures. For reference, “After-hours procedures” refers to da Vinci surgeries performed outside standard daytime operating room hours, so largely emergencies and acute cases that come in at night or on weekends, as opposed to scheduled, elective surgeries booked during normal OR hours.
It’s the best proxy for how much da Vinci is becoming the default tool even for emergency/urgent general surgery, not just a “nice to have” for scheduled operations. This after-hours market is more stable and reflects deepening penetration, so outsized growth here is a big positive.
Nonetheless, 12% growth in da Vinci procedures YoY is a further slowdown from 14% in Q1, which wasn’t unexpected. Demand trends in Q2 played out largely as expected, with Intuitive facing headwinds in the U.S. market from the expiration of subsidies for ACA enhanced premiums, which had a modest but notable impact on procedure growth. Simply put, management can see a slowdown in benign procedure growth, the subset that can be deferred, as changes in insurance coverage led to patients postponing non-emergency surgeries.
For background, the enhanced ACA subsidies, in place since 2021 under the American Rescue Plan, which had removed the 400%-of-poverty income cap and capped benchmark premiums at 8.5% of income, expired in late 2025. Not eliminated entirely, but scaled back significantly. According to the Urban Institute, this means around 4.8 million people would drop coverage without an extension of the enhanced credits. KFF estimates that it would push average premiums up by about 75%, or more than $700 per year on average, for the roughly 22 million of the 24 million ACA marketplace enrollees who received a premium tax credit in 2025.
So, the logic is simple: marketplace enrollees facing higher premiums or losing coverage are more likely to defer elective procedures. And they are, impacting procedure growth for Intuitive. This was anticipated and remains fully outside of Intuitive’s control.
And with the U.S. accounting for 56% of the installed base and an even higher percentage of revenue, the impact is outsized.
Crucially, it is worth pointing out that patients are only postponing procedures – these aren’t canceled. These procedures are still poised to happen in due time, with improved coverage as the most direct catalyst for procedure growth to improve. So, this is a near-term headwind, but not a long-term destroyer of demand or a weakening of the business.
I am not worried about this development, but it is worth monitoring closely.
Outside of the U.S., total procedure growth was 21%, with da Vinci growth solid at 20%, driven by 20% growth in Europe and Asia, and the rest of the world up 22%. Positively, da Vinci adoption for benign procedures outside the U.S. is looking very good, with procedure growth accelerating to 37% in Q2, now representing 25% of the international business.
At the same time, Intuitive continues to face serious headwinds in China. As explained last time out, Intuitive is facing very intense competition in China, impacting its win rate, largely due to local policy supporting and favoring domestic manufacturers. Q2 continued to see a drop in tender activity, driven by increased domestic robotic competition and policy-driven pricing pressure.
This is probably one of the bigger concerns today. Intuitive’s access to the Chinese market, which is a huge one, is increasingly restricted, limiting its TAM and dragging on growth in Asia, likely long-term.
Positively, this slower growth in China was offset by new policies supporting robotic surgery in Japan, including reimbursement for additional procedures and economic incentives for higher-utilization programs. Also, India had another strong quarter, and Intuitive received clearance for the da Vinci 5, which could be a potential growth catalyst in a huge market.
In general, even without China, the international runway for Intuitive remains large, and I expect this to remain a key growth driver for years to come, especially as it gains a foothold in large markets like India and Japan.
Ultimately, solid mid-teens procedure growth drove I&A revenue (instruments & accessories), which is directly tied to procedure volume, up 18% YoY to $1.73 billion. You can see this slightly outpace procedure growth itself, reflecting higher I&A revenue per procedure, with da Vinci revenue per procedure in Q2 sitting at $1,830, up from $1,800 last year, driven by a higher mix of SP and da Vinci 5 procedures, offset by customer ordering patterns, higher cholecystectomy procedures, and lower bariatric procedures (the latter two are lower-margin procedures).
Now, driving the growth in procedures is a combination of two factors – higher utilization and new system placements. In other words, its machines are being used more, and Intuitive is growing the number of machines performing procedures.
Starting with utilization, this trend remains largely stable in recent quarters. Q2 da Vinci utilization was up 3% YoY and Ion 11%, in part driven by a growing installed base of da Vinci 5 systems, which can be used for more procedures and therefore see higher utilization out of the box.
Then, on systems, Intuitive delivered a good capital performance in Q2. It placed 468 da Vinci systems, up 18% YoY. Of the 468 placements, 246 were da Vinci 5 placements, and 38 were da Vinci SP systems. Additionally, it sold 64 refurbished Xi systems and 58 X systems in Q2, both older generations that have been replaced by new versions. Both reflect a significant increase in refurbished demand by more cost-constrained customers. Finally, Intuitive placed 55 Ion systems in Q2.
Ultimately, this translated into total da Vinci installed base growth of 12% YoY, in line with the last two quarters, growing it to nearly 12,000 da Vinci systems and 13,000 total systems, which is unmatched.
I am positively surprised that growth held up well here.
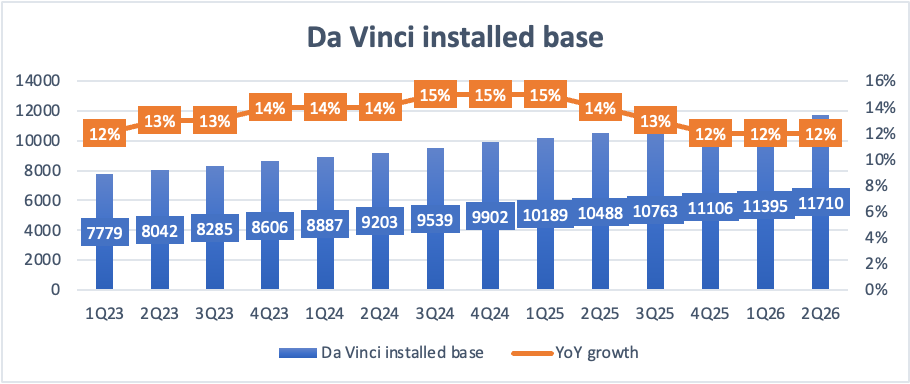
Looking at the performance by region, Intuitive placed 267 systems in the U.S., up an impressive 24% YoY, driven by adoption of and upgrades to da Vinci 5. Internationally, it placed 201 systems, up 12% YoY, with 75 in Asia and 79 in Europe. In Asia, strength in Japan (25 placements) was offset by competitive dynamics in China (2 placements).
This solid performance in systems sales drove systems revenue up 19% in Q2 to $685 million. This outpaced total placements growth due to a higher average selling price of $1.6 million, up from $1.5 million a year earlier, driven by a higher mix of da Vinci 5 and dual console systems, partially offset by higher trade-ins and a higher mix of lower ASP X and XiR systems.
Additionally, service revenue, which is closely tied to the installed base growth, was up 21% YoY in Q2 to $472 million. This was also driven by higher service revenue per system, up 8% YoY, reflecting a higher mix of da Vinci 5 systems, which come with a higher price tag and more expensive service contracts.
Taken all together, Intuitive reported Q2 revenue of $2.89 billion, up 19% YoY, with recurring revenue (now 85% of the total) up 19% to $2.47 billion. In constant currency, revenue growth was 18%. Overall, revenue growth remains largely in line with recent years, with strong system placements and service revenue growth offsetting a slowdown in procedure growth.
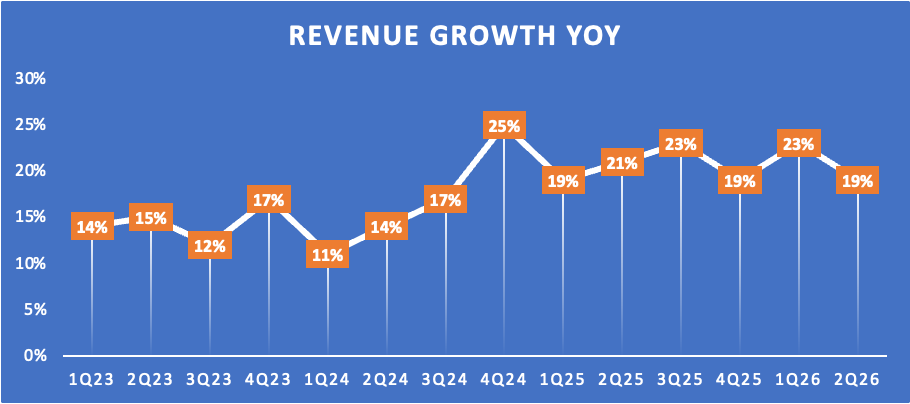
All in all, yes, Intuitive’s Q2 top-line results show some anticipated weakness, but the overall result was absolutely solid. It lacked a real positive surprise, which might have disappointed Wall Street, but I was quite pleased with the numbers.
With that, let’s move to the bottom-line results!
