

Lam Research, the third largest manufacturer of semiconductor equipment, is one of the highest-quality and best-managed businesses in the semiconductor industry, and you can’t change my mind. I mean, the numbers speak for themselves.
A 14% revenue CAGR since 2013.
A 24% EPS CAGR since 2013.
Outgrown the underlying industry by 20% over the last decade.
An ROIC at least 5x the cost of capital since 2016, and an ROIC of above 35% since 2019.
A TTM ROE of 54%, which hasn’t fallen below 43% since 2019.
A 29% FCF margin -> $5 billion in annual FCF.
14% dividend growth CAGR (10 consecutive years) and 60%+ share count reduction since 2013 – management returns 99% of FCF to shareholders.
This is a market leader with a massive moat and a capital-light business model.
This is a Rule of 50 business as of its last fiscal year.
There’s a good reason why Lam is one of the Top 5 positions in my portfolio - the company is the perfect combination of growth through secular tailwinds, exceptional business fundamentals, and brilliant execution – this is a long-term gem!
Last week, Lam delivered another strong quarterly report, surpassing consensus estimates and issuing guidance that well exceeded both Wall Street’s and my own expectations. Meanwhile, the company’s outlook only continues to improve amid record data center deals being signed left, right, and center, suggesting incredible demand for compute that should last well into the 2030s – this AI momentum we’re seeing seems to only be improving. And Lam is in the prime position to benefit, as laid out in my prior coverage of the shares, which is also perfect for a closer look at this business. You can find it below!

As a result of these improving dynamics, Lam shares are up 156% since their April low, up 110% YTD, and up another 59% since I last covered them in early August, when shares weren’t cheap any longer. Yet I still rated shares a buy in August, simply because everything was going Lam’s way and I saw significant upside to my estimates if trends held.
And boy, did that materialize quickly. Yes, a 59% share price gain in just under three months is pretty insane for a business with a market cap approaching $200 billion, but this gain is supported by a rapidly improving outlook and extremely promising long-term market conditions, as just pointed out. I was already very bullish on Lam, but clearly nowhere near bullish enough.
However, this promise does come at a price, as Lam shares have become considerably more expensive. Shares trade near their highest TTM P/E of the last decade and at a 50% premium to their 5-year average and a 22% premium to the sector average. Clearly, shares have gotten a lot more expensive.
So, time to make up the balance again and reconsider whether Lam is still a good buy today or whether it’s time to move to the sidelines, or even take some profits. To do so, let me take you through the fiscal Q1 results, adding some perspective to the numbers, and reviewing performance.
Let’s delve in!
Welcome to InvestInsights — an independent equity research publication rooted in long-term, buy-and-hold investing, publishing actionable stock/equity research reports weekly!
📈 You’re reading my latest exclusive stock analysis. If you like this analysis, make sure to like & subscribe to receive much more like this!
If you’d like full access to this post and all my other exclusive analysis & portfolio access (14% CAGR since 2022), consider becoming a paid subscriber!
Lam’s Q3 - Another sublime quarter
Lam reported its September quarter (fiscal Q1) results on September 22 and saw a strong share price reaction (+5%) in the following trading sessions as investors digested results that were once again very robust. The company exceeded the midpoint of its guidance and the Wall Street consensus on every single metric!
Lam reported total fiscal Q1 revenue of a record-high $5.3 billion, up 28% YoY, 3% sequentially, and beating consensus estimates by $90 million. Additionally, the deferred revenue balance was up to $2.77 billion, driven by an increase in “services and system-related transactions where revenue recognition was not yet complete.” For reference, Lam recognizes revenue only when a system is installed at the client or a service action is completed, but the timing of this can fluctuate. This deferred revenue is revenue that will be realized soon.
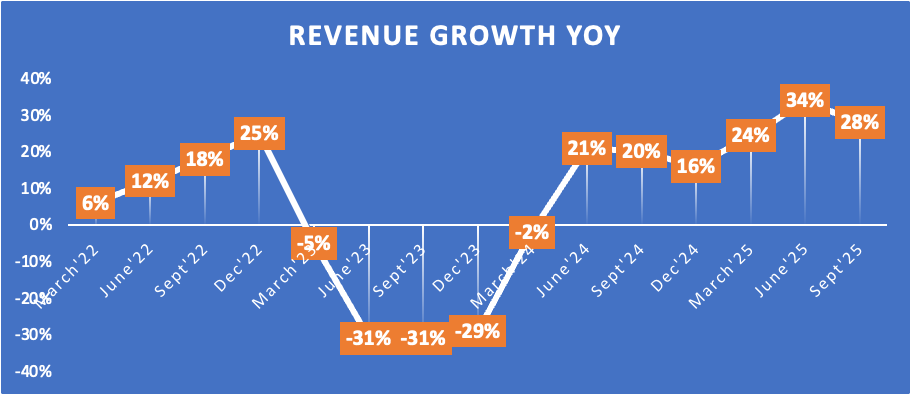
Anyway, I am pleased to see revenue momentum remain strong, as Lam is seeing excellent demand for its cutting-edge systems amid accelerating investments by its 20ish customers. This was best reflected in a whopping 48% growth in systems revenue in Q1, which is awe-inspiring growth. Including guidance for the final quarter of calendar year 2025, Lam seems poised to grow systems revenue by roughly 40%, which is miles ahead of the expected 10% growth for the WFE sector as a whole, highlighting tremendous outperformance.
This once again confirms Lam’s growing role in semiconductor manufacturing, thanks to its exposure to faster-growing technologies. Simply put, as semiconductors become more advanced and the manufacturing process more complex, Lam’s equipment becomes more critical – a brilliant dynamic. This is what allows it to outpace the industry as a whole, a trend that should persist.
Breaking down systems revenue by market segment, foundry continues to account for the majority of revenues, at 60%, up from 52% last quarter. Meanwhile, memory accounted for 34% of revenue, down from 41% last quarter, but this was purely due to the timing of customer investment plans. In the quarters and years ahead, I expect memory to account for the comfortable majority of revenue again, as it enters an explosive investment cycle. Lam is excellently positioned to benefit!
Besides explosive growth in system revenues, Lam reported services revenue that was practically flat from last quarter and the same quarter one year ago. However, it hit a record level in Q1 at $1.8 billion. This is driven by continued strength in its spares and upgrades business.
CSBG (services) remains one of Lam’s most important revenue streams, and it is the highest-quality one. As its installed base continues to grow, so should CSBG revenues, as demand for upgrades, spare parts, and maintenance should remain strong. Most importantly, these revenues are mostly recurring, being based on multi-year service contracts. This means these revenues will remain strong, even in a broader downturn. For reference, CSBG revenues have only registered negative growth once over the last 13 years.
Turning to geographical exposure, most revenues once again came from China, which is probably one of the biggest bear arguments in the Lam investment thesis, giving it considerable exposure to the impact of future export restrictions imposed by the U.S. In Q1, 43% of revenues came from Chinese customers, up from 35% in Q4. Most of these revenues came from domestic Chinese clients.
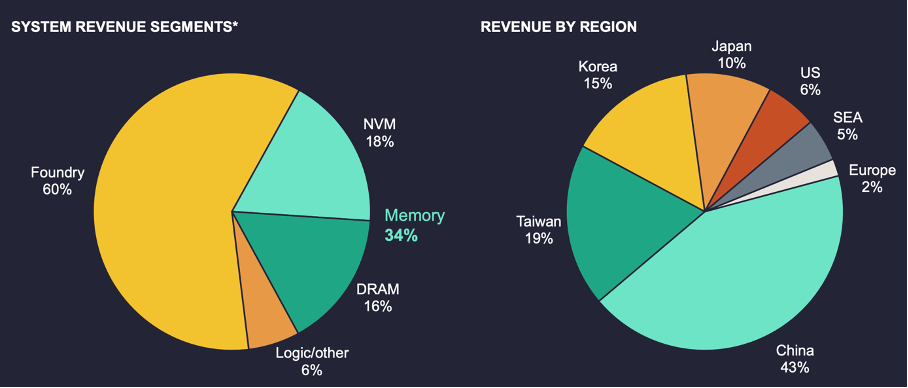
Positively, we should see this percentage decline considerably in 2026, creating a drag on short-term revenue but improving its long-term risk profile. This is driven by the 50% affiliate rule, which restricts shipments to specific domestic Chinese customers. In Q2, this will create a $200 million drag on revenue and a likely $600 million drag in calendar year 2026. However, the result is that Chinese customers will start to account for less than 30% of overall revenues, which I deem a very positive development!
Yes, this short-term drag isn’t ideal, but this is easily offset by explosive demand elsewhere, and it will improve the long-term revenue mix, lowering risk.
On that note, let’s move to the bottom-line result, where we see more record highs across the board.
Lam reported a record-high gross margin of 50.6%, up 240 bps YoY, driven by a more favorable customer mix, partially offset by a limited tariff impact. As for the favorable customer mix, this refers to larger China exposure, which carries higher margins. The loss of this revenue in the coming quarters will create a minor drag on margins. Positively, tariffs are having less impact than feared, though the effect should grow in Q2.
Moving further down the line, Lam reported total operating expenses of $832 million, up 16% YoY, growing more slowly than revenue and improving operating leverage. 68% of expenses came from R&D investments, which were up 16% YoY but declined as a percentage of revenue. Growth in SG&A expenses was also limited to 15%, resulting in minimal cost growth.
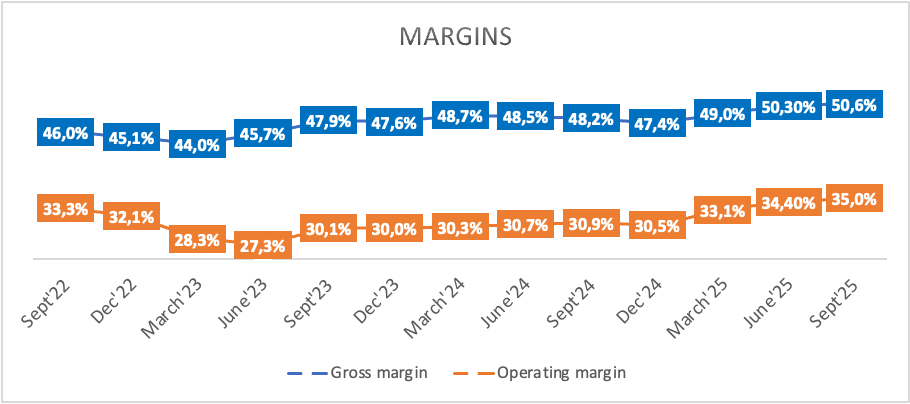
As a result, Lam reported a record-high operating margin of 35%, up a whopping 410 bps YoY.
This also led to strong EPS growth. Q1 EPS was up 47% YoY to $1.26, coming in above the midpoint of guidance and beating consensus estimates by $0.04.
Ultimately, Lam reported $1.78 billion in net cash provided by operating activities. This fully covered Lam’s $990 million returned to shareholders in Q1, consisting of $292 million in dividends and $698 million in buybacks.
Lam continues to be extremely shareholder-friendly. The company still aims to return 85% of FCF to shareholders over time. It currently still has $6.5 billion remaining under its current repurchase plan and raised its dividend by 13% earlier in the quarter, marking its 10th consecutive year of dividend growth.
Despite these capital returns and some CapEx investments, Lam still strengthened its balance sheet in Q1. The company ended the quarter with $6.7 billion in cash and equivalents, up $300 million from the prior quarter. Meanwhile, debt remained limited to $4.5 billion, leaving Lam with an excellent net cash position.
What is there not to like!
On that, let’s move to the highlight of this analysis, which is the medium-term outlook!
Want more out of your subscription? Even more content like this weekly?
Consider InvestInsights PRO - $7.50/month ($70/annually)
This gets you:
A guaranteed 6+ stock analyses every month (of which at least 2-4 are paid-exclusive).
Full insight into my own portfolio, including allocation, transactions, watchlist, performance, and relevant thoughts (14% return CAGR since January 2022).
Instant transaction alerts anytime I buy or sell any shares (Fully transparent).
A complete overview of all my target prices and ratings (online available).
Access to the InvestInsights Hub, containing all of the above in a single online sheet, updated instantly!
Want to keep reading? You will get immediate access to the remainder of this LRCX 0.00%↑ analysis!
Outlook & Valuation
Let’s start with some notes on its long-term outlook, which only continues to improve.
You see, all these massive data center/compute deals being signed are a very optimistic signal for Lam’s long-term prospects. Ultimately, Lam provides cutting-edge equipment for semiconductor manufacturing. The company focuses on Deposition, Etching, and Wafer Cleaning, each of which is expected to outgrow the sector as semiconductors become increasingly complex in the advanced computing and AI era.
