

Those who thought a post-earnings sell-off of 14% back in March was bad for Lululemon were in for a not-so-pleasant surprise last week, as Lululemon shares lost a whopping 20% of their value after reporting its Q1 financial results, which actually came in roughly in line with consensus estimates. However, LULU’s underlying numbers were surprisingly weak, with very poor comparable sales growth in the U.S. and international growth slowing quite dramatically.
LULU’s Q1 numbers simply showed broad-based weakness and a loss of traction, even without any impact from tariffs, which is far from ideal and well short of what I anticipated seeing. In response, $LULU shares have fallen back to near the lows they put down following Trump’s Liberation Day tariffs, at peak panic.
Now, the big question right now is: Is this massive drop an overreaction to short-term issues and a great buying opportunity? Or is Lululemon showing fundamental weakness and losing traction?
Buying opportunity or a justified sell-off amid a weakening thesis?
Let’s go over the results and developments and make up the balance!
A Q1 earnings review
Interestingly, LULU actually delivered revenue growth at the high end of the guided range, and still managed to really disappoint investors. Why? Yes, revenue was at the high end of the guidance range, but expectations were higher amid the tariff cancellations and the subsequent consumer relief. This wasn’t incorporated in management’s guidance yet, so this isn’t entirely representative.
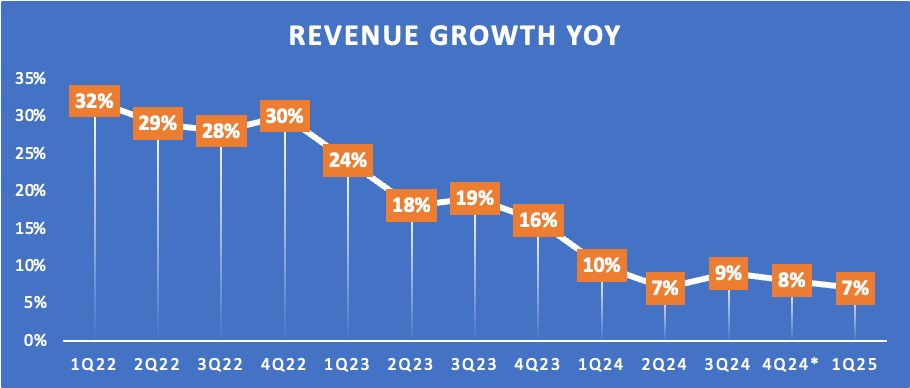
LULU reported total Q1 revenue of $2.4 billion, up 7% YoY, showing some further weakening from recent quarters. Clearly, LULU is no longer the rapidly growing apparel brand we have gotten to know in recent years. Growth has slowed from the high twenties in 2022, when the company experienced incredible demand and rapid international expansion, to just high single digits today, as the company has lost traction amid operational flaws and macroeconomic headwinds, the latest being Trump’s tariffs.
Over the last 1.5 years or so, LULU has seen weakening demand for its products. Initially, this was caused by management’s own missteps, as it fell behind in terms of product innovation and newness. As a result, customers were less likely to buy LULU products when visiting the stores, which led to a decline in sales growth. Additionally, in recent quarters, macroeconomic headwinds have further impacted growth, as LULU is experiencing weakness in demand amid cautious consumer spending, particularly in the U.S., its largest market.
This same weakness was clearly visible in its Q1 results and is showing no sign of improvement.
Q1 comparable sales growth (sales growth excluding new stores) dropped further to just 1% YoY, down from 4% in Q4, showing weakening demand. This time out, demand in North America actually showed some sequential improvement, with revenue growth accelerating from 1% in Q4 to 3% in Q1, although comparable sales remained negative at -1%.
According to management, U.S. consumers continue to exhibit considerable caution, as reflected in these numbers. However, on a positive note, the company appears to be gaining market share in both the women’s and men’s premium athletic wear markets in the country, which is about all we can wish for.
Meanwhile, this still weak U.S. growth was once again offset by strong growth outside of North America, although this is now slowing down considerably from previous quarters, which isn’t a positive sign. Growth in China was 21%, slowing considerably from 38% growth in Q4, which is almost entirely driven by far lower comparable sales growth, coming in at just 8%. This suggests that LULU is not experiencing the same demand it previously did in China, with the majority of growth in the region coming from store expansion.
This is exactly why I prefer comparable store sales over revenue to monitor growth. Comp sales indicate the extent of growth coming from the core business, not just geographic expansion. It signals actual business health and customer demand. It seems like Chinese customers may be pulling back due to macroeconomic factors or shifting preferences. However, since LULU also delivers comparable growth below some of its peers, I am cautious of some brand fatigue or competitive pressures as well.
One minor note here is that the Chinese New Year shifted from Q1 to Q4 of last year, which resulted in a roughly four percentage point headwind in growth. However, this still meant growth was relatively poor, especially considering this is supposed to be LULU’s largest growth market.
I really hope this growth trend reverses, but it will be crucial to monitor. Currently, I am not too pleased.
The exact same goes for the Rest of the World, where LULU reported revenue growth of 16% in Q1, down from 22% in Q4. Comparable sales here also dropped considerably from 17% to 7%, showing broad-based weakness.
For the business as a whole, this demand weakness was largely offset by 14% growth in store square footage, achieved through the addition of 59 stores compared to Q1 of last year, bringing the total to 770.
This ultimately led to a 7% year-over-year revenue growth. By category, this was driven by 8% growth in men’s, 7% growth in women’s, and 8% growth in accessories.
Now, to turn a bit more positive, management did indicate that guests are responding well to the improved newness and innovation across LULU’s assortment, which is back in line with historical averages. Earlier, I mentioned that a lack of newness had cost it plenty of sales in recent quarters, but management has at least turned that ship around, showing better product inventory and plenty of new offerings.
In addition, LULU has launched several strong campaigns in Q1, which have received a positive reaction. In fact, the company’s unaided brand awareness in the United States increased from the mid-30s in Q4 to 40% in Q1, yielding strong results and a positive ROI. Nevertheless, growing brand awareness remains a large opportunity for LULU, but I appreciate the results we see today.
On that note, let’s move to the bottom line, where tariffs are a leading subject.
You see, LULU has most of its production located in countries like Vietnam, Sri Lanka, and Cambodia. As a result, record-breaking U.S tariffs often exceeding 50% were extremely bad news for LULU’s U.S. business, which is by far its largest market. It could destroy margins and demand amid higher prices.
Positively, earlier in the quarter, Trump postponed reciprocal tariffs by 90 days, and these Asian countries have proven eager to negotiate to bring tariffs back to zero. As a result, for now, the impact LULU suffered was relatively limited, facing only 10% tariffs and a 30% tariff on goods imported from China, which allowed LULU to keep margins relatively healthy, even amid a top-line slowdown, in large part thanks to strict cost management.
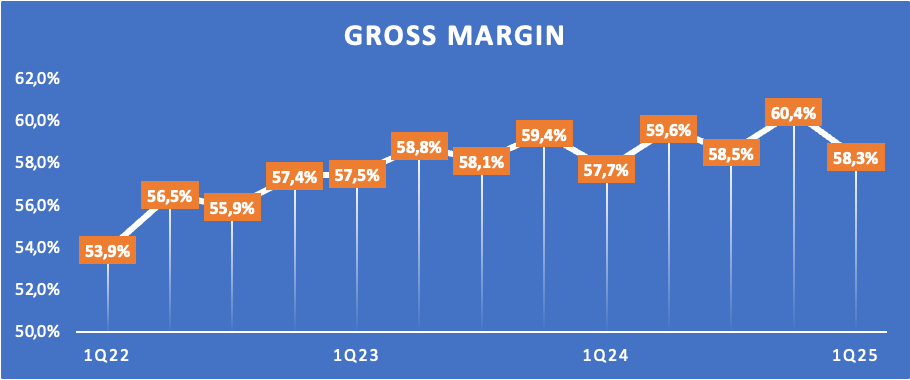
For Q1, LULU reported a gross profit of $1.4 billion, reflecting a gross margin of 58.3%, which is an improvement of 60 bps YoY, nicely ahead of expectations. This improvement was driven by a 130 bps product margin improvement, thanks to lower product costs, improved damages, and reduced markdowns, partially offset by higher airfreight costs and foreign exchange (FX) effects. This is remarkably strong, and it remains best-in-class, while still showing steady improvement.
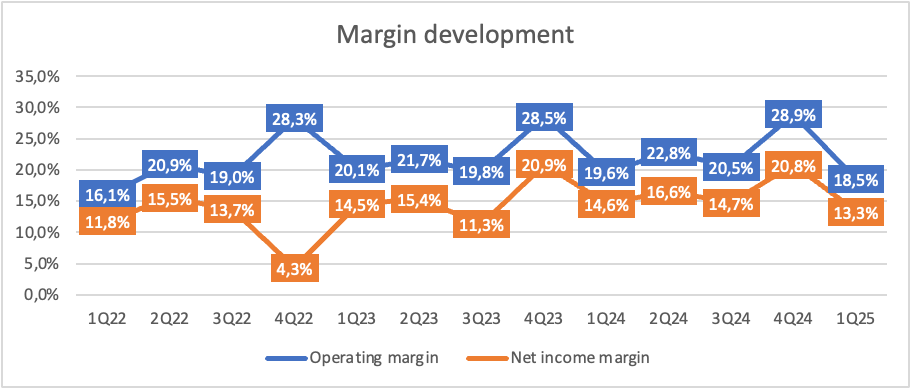
Moving further down the line, driven by the slower top-line growth and continued investments, SG&A as a percentage of revenue was up 170 bps YoY, which was more than the 120 bps management guided for due to the FX effect.
As a result, the operating margin in Q1 was only 18.5%, down 110 bps YoY. Furthermore, the net income margin was 13.3%, down 130 bps, in part due to a higher tax rate. This translated into an EPS of $2.60, up 2% YoY.
Overall, margins remain strong for now, although some weakness is starting to appear due to the combination of continued investments and slowing sales growth.
With margins holding up well, so did LULU’s cash flows, which allowed it to maintain a healthy balance sheet with $1.3 billion in cash and no debt, leaving it in an excellent financial position, especially in the face of near-term headwinds.
Finally, a notable development in Q1 was a 23% increase in dollar inventory, largely due to hedging against further tariffs and mitigating a potential later impact, at least to some extent. I wouldn’t say this is concerning for now.
Before we move on, just a quick word…
Want more out of your subscription?
InvestInsights PRO - $7.50/month ($70/annually)
An additional 2-5x/month premium stock analysis.
Full insight into my own portfolio (15% return CAGR since 2022).
Monthly portfolio updates + Instant transaction alerts (Fully transparent)
A complete overview of all my target prices and ratings (Excel file).
Exclusive access to the PRO subscribers Discord channel
Instant access to earlier premium analysis on, for example, Adobe, Thermo Fisher, Spotify, and The Trade Desk.
The remainder of this post, including the outlook, valuation, and conclusion, is for PRO subscribers only.
