

It wasn’t long ago that Monday.com felt like one of the easiest enterprise software stories to love. A sleek, colorful platform, beloved by users, growing 30–40% a year, throwing off cash, and expanding into new product categories seemingly every quarter. What’s not to like?
For years, Monday was the SaaS poster child for speed and flexibility, an antidote to clunky legacy software and overengineered point solutions.
But the past year has been different. The stock is down 30% over the last twelve months (and about 13% YTD) despite the S&P 500 powering higher.
Growth is slowing from the breakneck pace of earlier years. And, more importantly, investors are starting to wonder if Monday’s greatest strength, its ability to innovate quickly and integrate within teams without deep IT involvement, is enough to keep it competitive in an era where AI-driven automation may favor the largest, most deeply embedded platforms.
Before diving into that strategic debate, let’s quickly recap what Monday actually is and why it’s earned so much investor enthusiasm in the first place.
Monday.com is a low-code/no-code Work Operating System (Work OS) that lets organizations design and automate their own work management tools, from simple task boards to complex, cross-department workflows, without the cost and rigidity of traditional enterprise software. Founded in 2012 and launched commercially in 2014, it has evolved from a lightweight collaboration app into a broad enterprise platform sold under three main product lines:
Monday Work Management – project and portfolio management for any business function
Monday Sales CRM – a flexible, fast-evolving CRM for sales teams
Monday Dev – an agile development hub for engineering teams
All three products run on a single underlying infrastructure, where ~80% of the code is shared. This makes it unusually efficient to launch new features and modules. This structural advantage has fueled rapid expansion, allowing Monday to compete simultaneously with lightweight SMB tools (Trello, Asana, Smartsheet) and rigid enterprise suites (Salesforce, Atlassian, ServiceNow).
What’s made Monday stand out so far is its blend of ease of use and deep flexibility. Teams can build workflows, automations, dashboards, and integrations without heavy IT involvement, but the platform also scales to enterprise complexity. Combined with an open integration ecosystem and a land-and-expand sales motion, where adoption often starts with one team and spreads across an organization, Monday has built a loyal base of over 225,000 customers. Larger enterprise accounts are growing quickly, and newer modules like CRM, Dev, and Service are expanding revenue per customer, giving Monday a long runway in a fragmented, $100B+ TAM growing at a mid-teens rate.
Financially, Monday is among the healthiest SaaS players:
Revenue has compounded 30–40%+ annually in recent years.
Gross margins near 90% and free cash flow margins approaching 30% put it well above most peers.
It regularly exceeds the “Rule of 40,” often running at a “Rule of 50–60,” while still investing heavily in product development.
The balance sheet is pristine, with $1.5B+ in cash, no debt, and founder-led management with meaningful insider ownership.
So, why is there a souring sentiment and falling stock price?
That’s the question I want to tackle. In this analysis, I’ll discuss Monday’s latest quarterly results and Investor Day takeaways, update my financial projections and valuation, and, most importantly, reassess whether this is still a long-term buy-and-hold SaaS winner or a good business facing an increasingly uphill competitive battle in an AI-driven, consolidating enterprise IT market.
Welcome to InvestInsights — an independent equity research publication rooted in long-term, buy-and-hold investing, publishing actionable stock/equity research reports weekly!
📈 You’re reading my latest [FREE] stock analysis. If you like this analysis, make sure to like & subscribe to receive much more like this!
If you’d like full portfolio access (16% CAGR since 2022) & additional exclusive analyses, consider becoming a paid subscriber!
A Q2 Financial & Performance Review
Let’s start with a quick review of Monday’s latest quarterly financial and performance update.
The company announced its most recent financial results on August 11. Although the company surpassed consensus estimates and issued guidance that came marginally ahead of expectations, investors were left quite disappointed, as highlighted by a substantial mid-twenties percent sell-off in the subsequent trading session.
In large part, one could attribute the sell-off to the simple reason that expectations had grown way too high. At some point, just beating expectations by a slim margin isn’t enough; investors already price in a considerable beat and a huge positive surprise. That Monday definitely didn’t deliver with its Q2 results, and so a reset based on this alone was unavoidable, which is why I already stepped out of Monday one month earlier.
However, the more important argument to explain the sell-off is a combination of slower growth guidance and macroeconomic sensitivity, as reflected in key metrics. In other words, the underlying numbers simply revealed weakness, which has raised concerns about the viability of Monday’s growth story in the highly competitive enterprise software industry, particularly given its seemingly thin moat.
Let me take you through the numbers and provide some perspective.
Starting at the top, Monday reported second-quarter revenue of $299 million, up 27% YoY and topping consensus estimates by $5 million. In itself, 27% YoY growth in an industry plagued by cautious budgets, this isn’t a bad performance at all, yet it does show a further deceleration in top-line growth for Monday, now falling into the high-twenties.
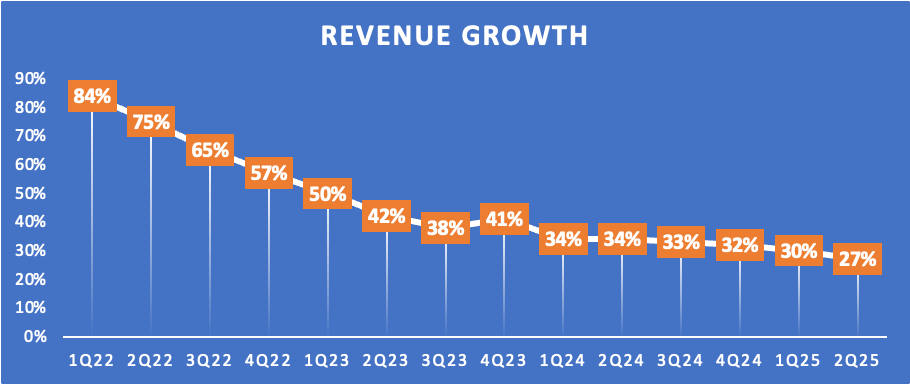
So, what is driving this slowdown? It comes down to the fact that Monday is seeing some weakness downmarket as a result of more cautious IT spending and changes in the Google algorithm, which come on top of a tough YoY comparison.
The downmarket, which refers to SMB and mid-cap businesses, is still Monday’s largest customer base, so weakness here is dragging on its results. Though, considering the macro conditions and spending caution, this shouldn’t come as much of a surprise, since these smaller businesses are the most sensitive to these fluctuations, so some loss of momentum here for Monday is not a huge surprise.
However, what accentuated the slowdown here were changes in the Google algorithm. You see, earlier in the quarter, Google changed its algorithm by incorporating AI, with the first answer to any search query now coming from Gemini. This change pushes Monday’s advertisements linked to that query down, leading to a slowdown in organic Google traffic for Monday. Simply put, its links are less prominent on Google, and since this accounts for roughly 10% of its new ARR and just under 30% of new signups, this is a drag on results.
According to Monday, its high-quality customers still manage to find its ads, as they are looking beyond just a simple AI answer. However, the overall volume is down, and the impact is apparent.
Notably, management expects this headwind to be temporary and easily resolved.
Furthermore, demand remains strong overall. Particularly upmarket, among larger businesses and enterprises, Monday is seeing good traction, recording a record high of 100,000 customers and its highest-ever net ads, as recent product investments aimed at these exact customers are paying off. It’s this customer category that is driving growth for Monday and which presents a massive opportunity going forward.
As this upmarket momentum should hold up and downmarket growth recovers toward the end of the year, I think it’s safe to say Monday’s growth story isn’t broken here; the business is just dealing with near-term headwinds, which it is actively mitigating.
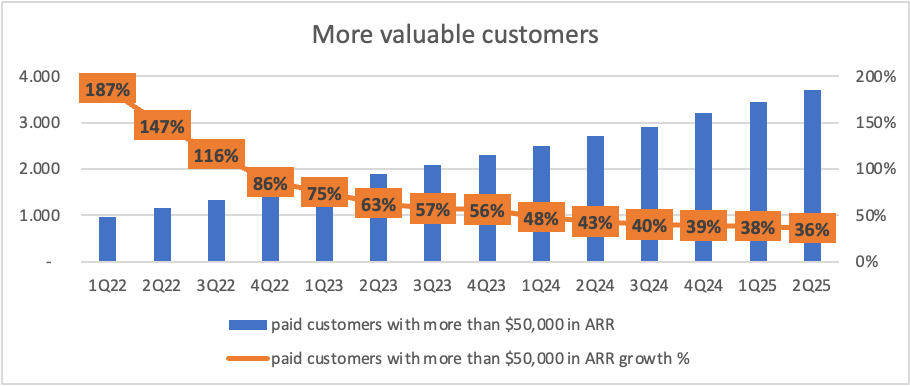
Pointing out some more Q2 numbers, customers bringing in 50k or more in ARR grew by 36% in Q2, slowing down from 38% in Q1 and 43% in the same quarter last year. Yes, this continues to decelerate, but this is as expected, given that the base is growing rapidly. If anything, growth is holding up pretty well.
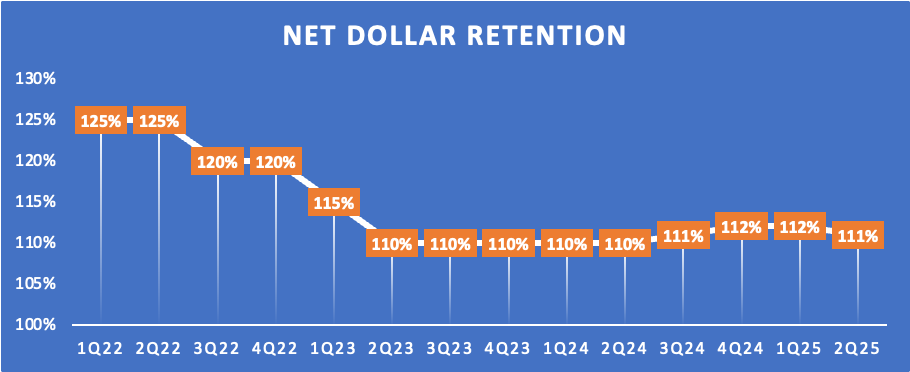
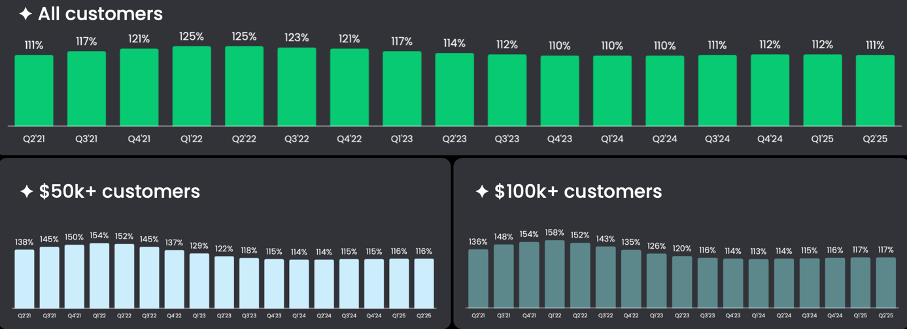
Furthermore, net dollar retention fell from 112% in Q1 to 111% in Q2, also showing a slight weakness, but remaining within the same range as it has over the last two years. Additionally, upmarket customer retention was flat, so there is not much to be concerned about, although it is not showing the improvement investors were hoping for.
However, one factor I am increasingly cautious about – and one that feels more structural than simply short-term macro noise – is the cost of sustaining Monday’s growth engine.
The company’s rapid expansion has been powered primarily by relentless platform innovation and product launches. That strategy has worked brilliantly so far: Monday has taken a relatively simple collaboration tool and expanded it into a full Work OS with CRM, Dev, and other vertical solutions. But as the platform has scaled, each incremental step forward is becoming more expensive.
To maintain its pace of innovation and stay ahead in a fiercely competitive market, Monday has aggressively expanded its headcount and maintained elevated R&D spending, even as it improves profitability on a non-GAAP basis. This is starting to weigh on GAAP margins, as stock-based compensation remains high and true operating leverage has yet to materialize.
For reference, R&D expenses in Q2 rose to 20% of revenue, up from 16% in the same quarter last year, amid the company’s AI push. Positively, this was offset largely by sales and marketing expenses falling to 47% of revenue, down from 51% one year earlier, which still allowed for the non-GAAP operating margin to come in at 15%, down just 100 bps YoY.
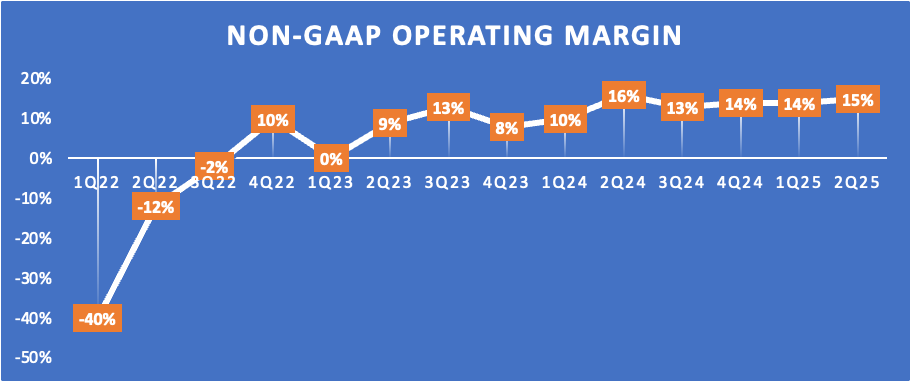
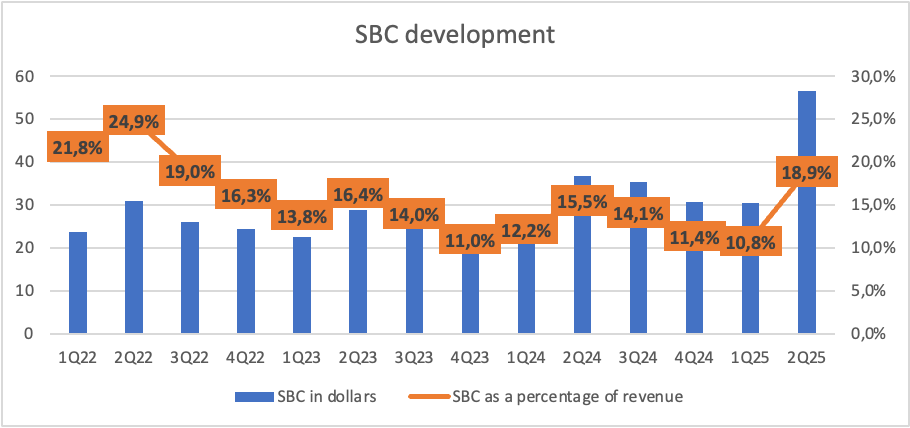
However, the real problem is GAAP profitability, which includes stock-based compensation. This means that GAAP profitability more accurately reflects actual growth investments, as it includes the impact of headcount growth. Here, the company is performing significantly worse.
Most notably, SBC expenses in Q2 hit a 2.5-year high when defined as a percentage of revenue, hitting 18.9%, up 340 bps YoY.
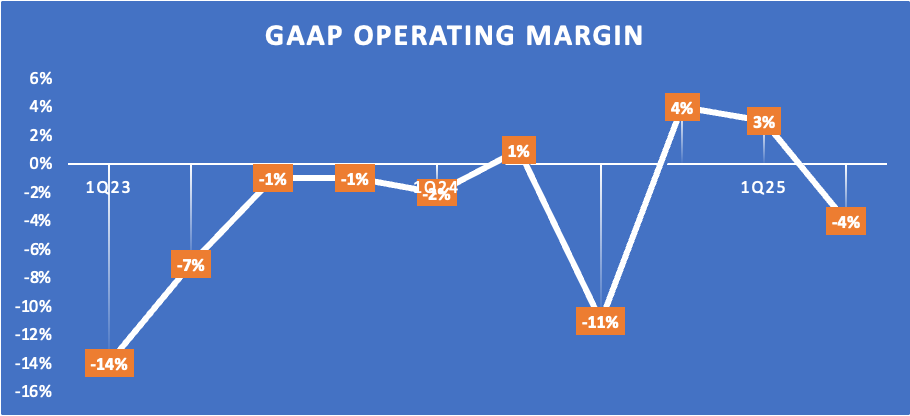
As a result, the GAAP operating margin turned negative again at -4%, down 500 bps YoY and clearly reflecting the impact of higher costs and investments.
You see, the challenge is that Monday operates in a hyper-competitive, fast-moving software landscape where barriers to entry are low and switching costs, while real, are not insurmountable. Larger incumbents like Microsoft (Teams, Planner), Atlassian (Jira, Trello), Salesforce (Slack, platform integrations), and Smartsheet continue to innovate and can bundle or cross-sell their own solutions, often at lower effective cost to customers. Meanwhile, newer players can mimic core functionality relatively quickly thanks to the rise of no-code/low-code frameworks.
That means Monday can’t simply slow its investment in innovation without risking product parity, but keeping the pedal down comes with rising costs and delays the path to truly durable GAAP profitability. The company’s lack of a deep moat (no proprietary network effect, no unique data advantage, and relatively modest switching friction compared to platforms like Salesforce or ServiceNow) forces it to rely on speed of execution as its primary defense. Execution is an advantage now, but it is not an enduring one if the cost to maintain it keeps rising.
This dynamic raises the question of long-term scalability: can Monday sustain premium growth and product differentiation while gradually converting more of its economics into true GAAP profitability? Or will it remain caught in an arms race of feature velocity and sales expansion to hold its position in a crowded market?
Regarding this, Q2 results do raise valid concerns.
Still, some levers could help alleviate some of the pressure over time. Monday’s land-and-expand strategy has historically been a powerful driver of operating leverage: once the platform is embedded in a department, it tends to spread across teams and geographies with relatively little incremental sales effort. If this motion continues to scale upmarket, particularly as larger enterprises adopt multiple Monday modules, the lifetime value of each customer should rise faster than the cost to acquire and support them, allowing sales and marketing intensity to ease. If successful, this could lead to a gradual improvement in GAAP margins, even as the company continues to invest in product development.
Another potential growth vector is artificial intelligence. Management has been leaning heavily into AI to make Monday more intelligent and proactive, surfacing insights, automating routine workflows, and helping users build solutions faster. In theory, this could open up new monetization paths (higher-tier plans, usage-based AI features) and expand Monday’s reach without a proportionate increase in engineering spend.
Ultimately, Monday remains a high-quality growth story: a flexible, widely loved platform in a vast and expanding market, with a proven ability to innovate and a long runway to grow revenue 20%+ annually while steadily expanding free cash flow margins beyond 30%. However, the cost of sustaining that innovation advantage is likely to remain high, and true GAAP profitability may remain elusive for longer than investors would prefer.
For long-term holders, the company still offers a compelling mix of growth, product strength, and cash generation. Still, it deserves its premium valuation only if management can translate today’s heavy investment cycle into durable operating leverage over the next several years.
And that remains massively uncertain and a serious risk – the Q2 numbers accentuated this.
To round up the financial review section on a positive note, Monday does maintain excellent financial health and generates strong FCF.
Q2 FCF was $64 million at a 21% FCF margin. This allowed Monday to further strengthen its balance sheet, ending the quarter with $1.59 billion in cash and practically no debt.
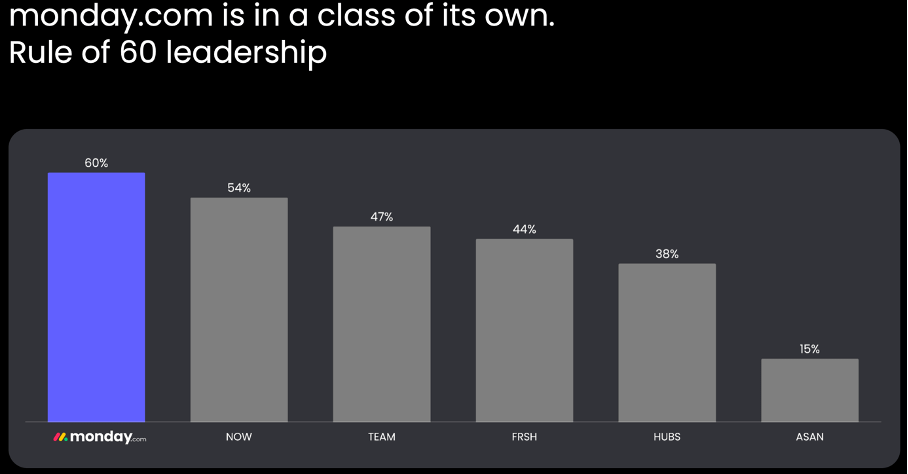
This means that even in a challenged Q2, Monday maintains its Rule of 40 status. In fact, in most quarters and years, including the trailing 12 months, Monday is a unique Rule of 60. This puts it well ahead of its peers and sets it apart in a class of its own.
The Monday.com Investor Day
Roughly one month after releasing its Q2 results, Monday held its Investor Day, providing much more background on its strategic priorities and financial targets. Having listened to the entire call, I would like to address several subjects that should matter most to investors and impact my thesis/projections, starting with AI.
AI integration
AI was a central theme at Monday’s investor day and is increasingly shaping its long-term product road map. Management was explicit that the company does not want to “add an AI layer” on top of existing workflows; instead, it is re-architecting products to embed generative AI deeply into the Work OS. The stated goal is twofold:
Make existing users dramatically more productive with the same headcount, and
make software creation and automation accessible to non-technical employees, taking Monday’s “anyone can build” vision “on steroids.”
This vision is already gaining traction today. Management disclosed that AI features are now used by 50% of customer accounts and have driven over 67 million AI actions to date, marking the fastest adoption the company has ever seen for a new feature. Recent launches such as Monday Magic (an AI-assisted solution builder), Monday Sidekick (an AI copilot for workflows), and Monday Vibe (a low-code app builder with AI help) have seen unusually rapid uptake, with 45,000 Sidekick actions, 7,000 apps built in two months on Vibe, and 2,000 new solutions in three months via Magic.
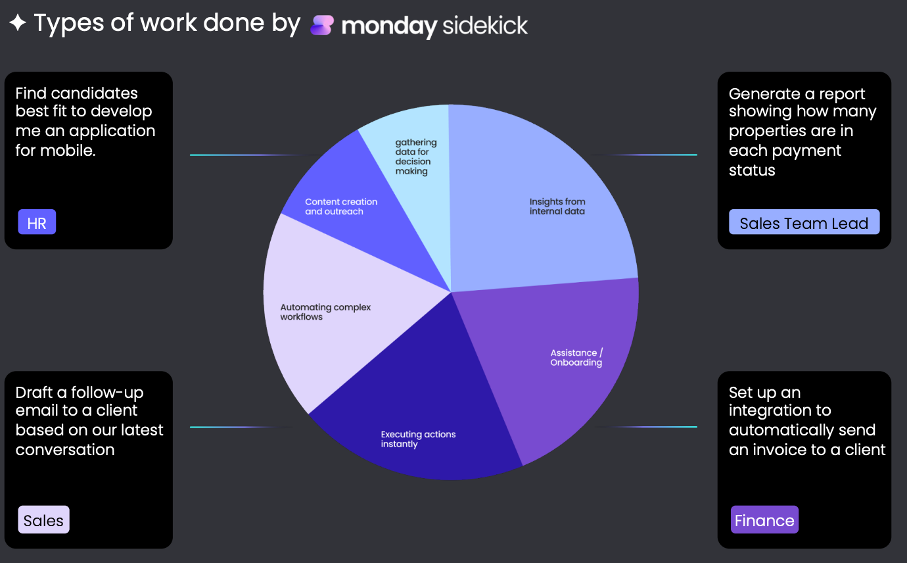
Furthermore, Monday is moving beyond simple productivity tools toward AI agents that “do the work”. The company envisions CRM agents that can call customers and schedule meetings, Dev agents that can write and maintain code while developers orchestrate them, and Service agents that can autonomously handle and close support tickets. In fact, a real-world HR use case was highlighted, where 98% of HR tickets were resolved without human intervention using Monday Service’s AI-equipped features.
To capture this shift, Monday is also expanding its product lineup: the newly announced Monday Campaigns adds AI-driven lead generation to its CRM suite, creating a more holistic customer lifecycle platform (campaign → sales → post-sale delivery).
From a business model perspective, these AI capabilities open the door to hybrid monetization. Monday plans to retain its familiar seat-based pricing but layer on consumption-based billing for AI usage (e.g., sidekick, AI blocks). If successful, this could increase ARPU, deepen account penetration, and create a recurring revenue stream driven by usage, alongside seat sales.
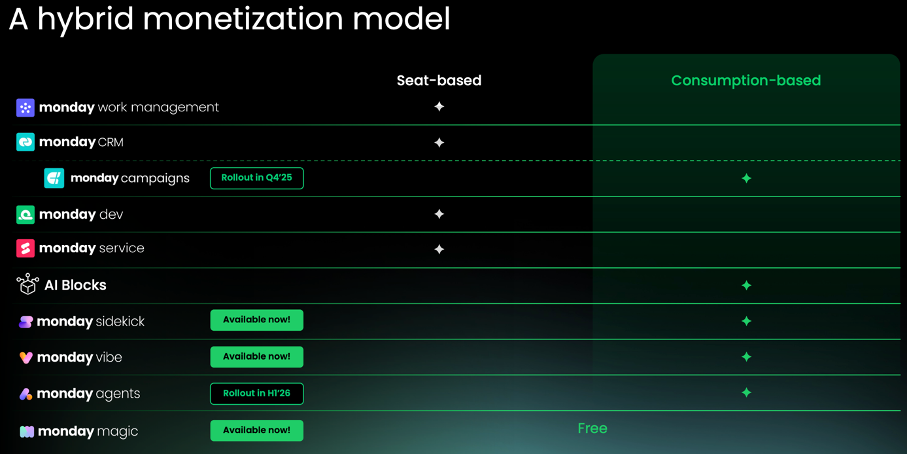
For investors, the upside is clear: AI could expand Monday’s addressable market, improve stickiness, and drive higher revenue per customer, all while helping customers automate work and lower costs, which supports the platform’s ROI case.
The challenge is that this AI push is not unique. Virtually every major competitor – Microsoft (Copilot), Salesforce (Einstein/agents), Atlassian, Smartsheet, ServiceNow – is embedding similar generative AI and autonomous agents into their platforms, often with larger installed bases, richer proprietary data, and deeper enterprise relationships. While Monday has demonstrated impressive product velocity and early adoption so far, there is no guarantee that AI will provide a defensible edge; it could become a table-stakes capability that companies must continually invest in to maintain parity – this is what I fear, especially for the smaller players, while the larger more embedded giants see the real benefit (i.e. ServiceNow and Salesforce).
Ultimately, the company’s progress in a short timeframe is impressive, but I am not yet convinced that AI will make a lasting difference.
Growth in the existing customer base
One of Monday’s most compelling growth levers remains deepening penetration inside its existing customer base. The company has proven it can build and launch entirely new modules that customers actually adopt. Each major product release (Monday Sales CRM, Monday Dev, Monday Service) has set new adoption records, validating both the platform’s extensibility and its ability to cross-sell into its installed base.
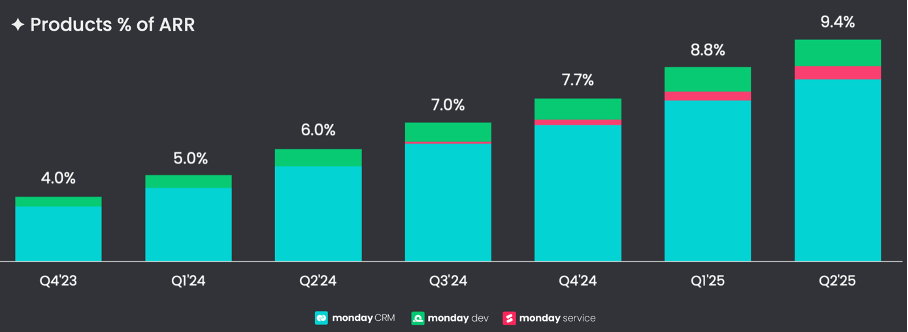
Yet, this opportunity remains largely untapped. Today, only about 6% of accounts use more than one Monday module, and just 9-10% of total revenue comes from products beyond the flagship Work Management offering. The low penetration is striking, given the economics: when a customer adopts more than one module, the average contract value (ACV) increases roughly 2.5 times. Since 2017, the average customer ACV has grown five times, thanks to platform expansion and broader usage. Management believes this trend can continue as Monday introduces new vertical solutions and pushes further upmarket.
Cross-selling is already showing early proof points. Roughly 60% of Monday Service ARR, 44% of Dev ARR, and 33% of CRM ARR have come from existing customers expanding their footprint.
The strategy typically follows a land-and-expand motion: Monday rarely lands a seven-figure contract upfront but often starts with a small deployment that grows to $100k, $300k, and eventually $1M+ ACV as more departments adopt the platform and add new modules over time. With Work Management still dominating the revenue mix and newer products like CRM (> $100M ARR), Dev (~$40M ARR), and Service (fastest-growing, ~$7M ARR) just beginning to scale, the runway for multi-product expansion is enormous.
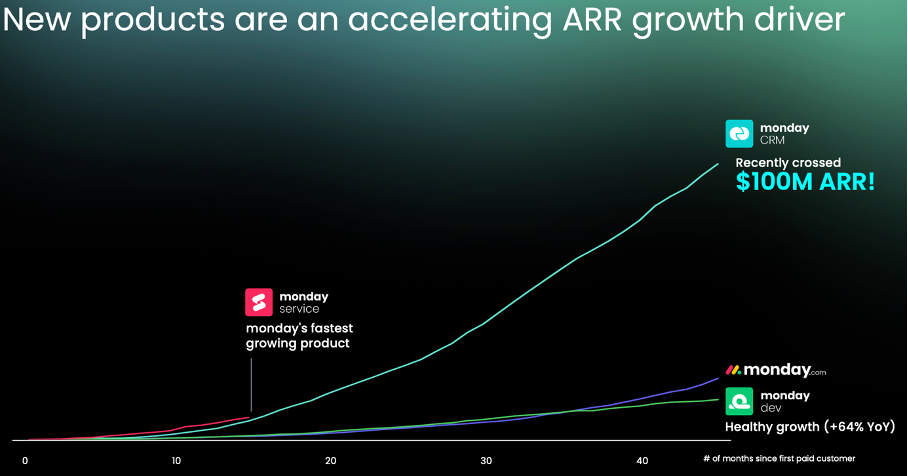
For investors, this multiproduct strategy could drive sustained high growth well beyond the company’s original work management niche. As Monday broadens its suite and captures more of the workflow stack inside existing accounts, it not only increases revenue per customer but also entrenches itself more deeply within organizations. This makes it harder for competitors to displace the company and supports durable growth as it scales upmarket.
This alone is a powerful growth lever, which Monday could leverage well into the next decade.
Customer acquisition
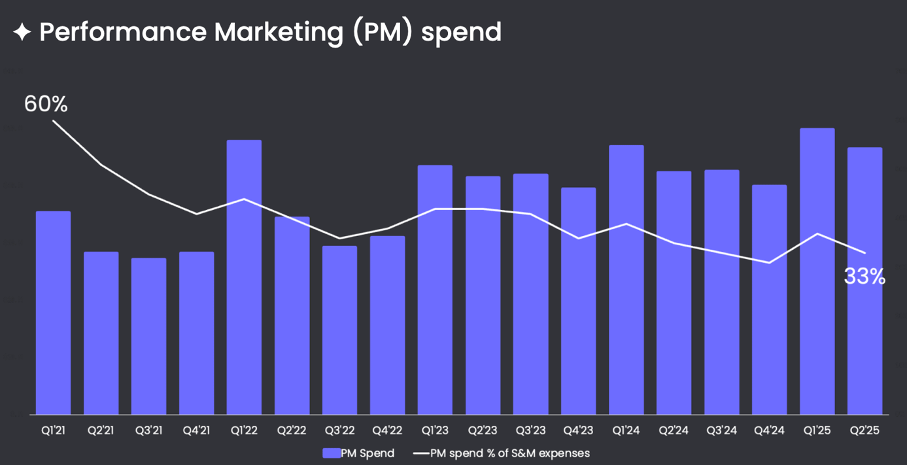
Another key theme from Monday’s investor day was the evolution of its customer acquisition strategy. The company began its life as a highly performance–driven marketing–focused SaaS business. For reference, in 2018, about 80% of new ARR came from paid performance channels. Over the past several years, Monday has deliberately built a much broader go-to-market engine, adding direct sales, channel partners, and enterprise-focused motions. As a result, performance marketing now represents a steadily shrinking share of total sales and marketing spend, reflecting a move from a volume-driven, SMB-centric approach toward a higher-quality, multi-channel acquisition model.
That diversification matters because it has improved the quality of new customers.
Monday now operates across 55+ acquisition channels, ranging from direct inbound and outbound sales to partners and newer emerging sources such as AI search (AIO). Particularly, the latter is interesting. Monday acknowledges that a growing portion of discovery is coming from AI-driven search engines, such as ChatGPT integrations; traffic from these “AIO” channels is still small but has grown 4.5 times over the past year as more buyers seek software recommendations through AI tools. Monday is investing early to win visibility in these emerging digital channels, which is a strong move!
Yet, more importantly, the company is clearly shifting its focus from quantity to quality in customer acquisition. New account ACV has doubled since 2019, and 38% of new ARR now comes from customers who start on the enterprise tier (the highest-end), up from just 25% at the IPO in 2021.
This means Monday is landing larger, more strategic accounts earlier, rather than relying on long, gradual expansions from tiny teams. Enterprise penetration is particularly striking: the number of accounts generating over $500k ARR has grown from just five in 2021 to 68 today — a 115% CAGR — with an average ACV of ~$900k and about 15 distinct use cases per customer. These are precisely the kind of complex, multi-department deployments that can expand well into seven figures and have long lifetimes, presenting a massive opportunity for Monday.
However, while Monday is clearly targeting the upmarket segment, it is not abandoning the SMB and mid-market segments. Management continues to invest across all customer tiers, leveraging its self-serve and freemium roots to fuel the funnel. At the same time, the growing sales organization focuses on converting and expanding higher-value accounts.
This evolution matters because it shows Monday’s growth is becoming more durable and less dependent on high-cost paid channels. The company is proving it can land bigger customers earlier, diversify acquisition beyond search, and tap new digital discovery paths such as AI-driven recommendations. Combined with its land-and-expand strategy, this stronger go-to-market engine is expected to provide a long runway for 20%+ revenue growth, supported by a healthier mix of customers and greater upmarket penetration over time.
Financials
Finally, there are financials. Monday’s financial profile continues to stand out among modern SaaS peers, characterized by high growth, rising efficiency, and strong cash generation.
Notably, the company now derives roughly 83–85% of its revenue from annual contracts, a shift that has steadily improved predictability and visibility in its model. Retention remains healthy: overall net dollar retention (NDR) is ~111%, stable despite a more challenging macroeconomic backdrop, while customers spending over $50k show an NDR of 115% or higher.
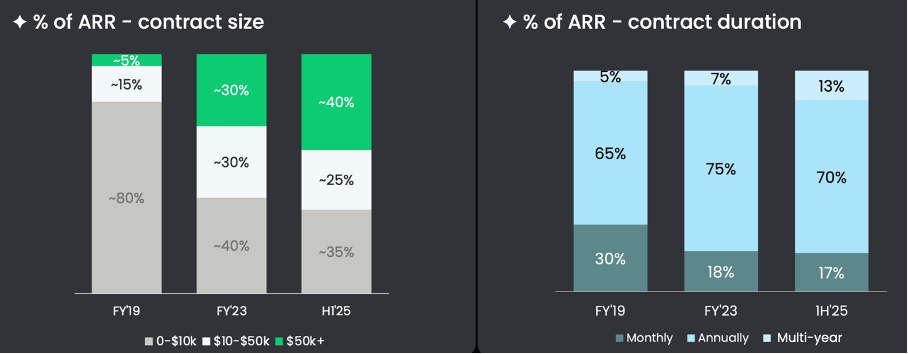
Management believes there is room to increase these figures, targeting a long-term NDR of 110–115% across all customers and 120–150% for enterprise accounts. Gross retention (although undisclosed) has improved by approximately 800 basis points since 2021, reflecting a more loyal and satisfied customer base.
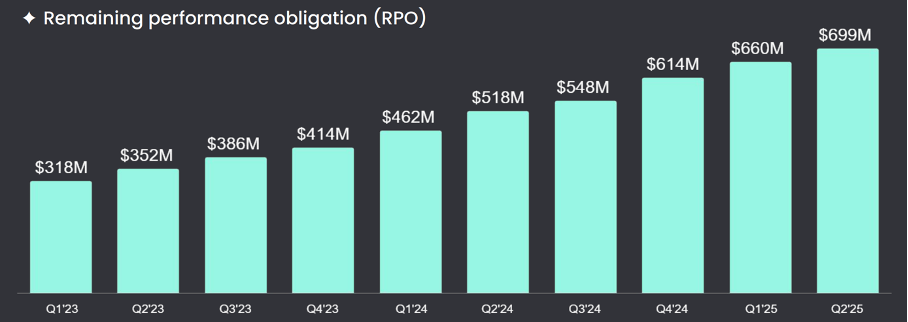
Revenue visibility is also evident in the company’s remaining performance obligations (RPO), which reached $768 million in Q2 2025, providing a solid backlog of future revenue. As the go-to-market engine moves further upmarket, average contract value (ACV) continues to climb, and an increasing share of new deals are large, multi-department deployments, which is beneficial.
Also, profitability and cash flow are improving at a strong pace. Since fiscal 2020, Monday has expanded its operating margins by 6,600 basis points, moving from a net loss of $86 million to a projected net income of approximately $156 million in fiscal year 2025.
Adjusted free cash flow (FCF) is projected to reach $326 million in FY25, underpinned by gross margins in the high-80% range (slightly lower than historic high-90% levels due to heavier AI computing costs).
Furthermore, sales and marketing leverage continues to improve as performance marketing shrinks to a smaller share of the mix and total S&M spend trends toward ~40% of revenue. R&D will remain a key investment area as the company prioritizes product velocity, especially in AI; however, overall operating efficiency is also improving, although GAAP profitability remains a challenge, as previously noted.
Looking ahead, Monday aims to sustain 20%+ annual revenue growth while steadily expanding free cash flow margins beyond 30%, supported by a richer mix of large enterprise contracts, growing multi-product adoption, and a more efficient go-to-market strategy.
That remains a compelling backdrop, with mostly optimistic targets from management.
Strategic Risk — AI Could Accelerate Platform Consolidation and Challenge Monday’s Position
While I don’t think the Monday growth story is broken after a tough Q2 (as pointed out) and I was generally optimistic following its Investor Day – given its strategic priorities, growth initiatives, and financial targets, which I liked – I also acknowledge that I see structural problems for the company going forward.
This might be the key part of this analysis – the most important takeaway for me personally.
While Monday has executed exceptionally well over the past several years, after my latest research, I’m increasingly cautious about its long-term competitive positioning in the age of AI. The company’s success has been built on product velocity, user-friendly design, and a highly flexible Work OS that appeals to teams frustrated with rigid legacy software – a great strategy, as proven in recent years.
But as the enterprise software landscape evolves toward AI-driven automation, the basis of competition may shift in ways that don’t naturally favor Monday.
The core issue is that AI agents work best when deeply integrated into a company’s systems of record, the platforms that already store critical operational, customer, and workflow data. Vendors such as Microsoft (Teams, Office 365, Dynamics), Salesforce (CRM, Service Cloud), ServiceNow (ITSM), and Atlassian (Jira) are deeply embedded in the heart of enterprise IT stacks. They control large volumes of proprietary data, have entrenched integrations with other corporate systems, and already function as the primary workflow backbone for many organizations. When AI transitions from being a simple assistant to actually executing work, such as creating records, updating pipelines, closing service tickets, writing and deploying code, deep integration and access to core data become critical advantages.
Monday, by contrast, has mainly succeeded as an overlay platform: flexible, fast to adopt, highly configurable, and loved by end users. However, it often sits next to, rather than inside, the core systems of record. Its flexibility makes it powerful, but it also makes it easier to replace if larger incumbents replicate key capabilities and bundle them into a broader suite of offerings.
Furthermore, Monday has no proprietary network effect (its value isn’t tied to having all your vendors or customers inside it), no unique data flywheel, and only moderate switching costs compared to truly mission-critical platforms like Salesforce or ServiceNow. Its primary competitive edge has been speed of innovation, which is an advantage that can erode if well-capitalized incumbents deploy similar AI-driven automation faster than expected.
Additionally, I expect AI to drive market consolidation. As autonomous agents begin to perform complex, cross-functional tasks, such as scheduling sales meetings, coding, resolving support tickets, and approving HR workflows, enterprises may increasingly prefer fewer, deeply integrated vendors for reasons of security, governance, and efficiency. Managing a patchwork of disconnected tools becomes riskier when AI agents need access to sensitive data and must act reliably across multiple domains. Large vendors with end-to-end suites (Microsoft, Salesforce, ServiceNow) could benefit disproportionately from this shift, using their installed base and trusted position to push AI deeper into enterprise workflows.
This trend could compress the opportunity for standalone platforms like Monday, making it harder to compete without either a massive ongoing R&D spend or a compelling differentiator beyond usability.
To its credit, Monday is not blind to this dynamic. Management is pushing hard into AI, building agents that can take actions across its CRM, Dev, and Service products, and experimenting with hybrid pricing (seats + AI consumption). Its rapid feature velocity remains impressive, and its land-and-expand model creates sticky departmental adoption that can grow into large, multi-module enterprise deals.
But I doubt whether this is enough to counteract the gravitational pull of consolidation. I believe AI-driven work execution becomes a core IT function, and the companies with deep data ownership and entrenched platform status may hold a structural edge that Monday cannot easily replicate, if at all.
This is why, despite my appreciation for Monday’s execution and long runway for 20%+ growth, I no longer view it as one of the best-positioned enterprise software names for the decade ahead. The market is shifting toward platform scale, deep integration, and proprietary data moats, areas where Monday is comparatively weaker.
Its continued success will likely depend on sustaining extraordinary product velocity and expanding its footprint fast enough to secure a place as a core enterprise platform before the established order fully weaponizes AI. That path is possible, but it is a much more challenging, execution-heavy race than the one Monday has been running until now.
I view this as the main thesis-breaker for Monday – it’s why I eventually didn’t buy the dip in the weeks post-earnings.
Want more out of your subscription? Even more content like this weekly?
Consider InvestInsights PRO - $7.50/month ($70/annually)
This gets you:
A guaranteed 6+ stock analyses every month (of which at least 2-4 are paid-exclusive).
Full insight into my own portfolio, including allocation, transactions, watchlist, performance, and relevant thoughts (14% return CAGR since January 2022).
Instant transaction alerts anytime I buy or sell any shares (Fully transparent).
A complete overview of all my target prices and ratings (online available).
Access to the InvestInsights Hub, containing all of the above in a single online sheet, updated instantly!
Outlook & Valuation
That then brings us to the outlook. Let’s start short-term.
Following its Q2 results, Monday issued (what I believe to be) very cautious guidance to de-risk its outlook amid some macro and Google search uncertainty.
Management now guides for FY25 revenue to be in the range of $1.224 billion to $1.229 billion, representing YoY growth of 26% at the midpoint, suggesting a further deceleration in growth in Q3 and Q4. Additionally, management guides for a non-GAAP operating income of $154 million to $158 million and an operating margin of approximately 13%, suggesting a mostly flat margin YoY. Finally, FCF is expected to be between $320 million and $326 million, reflecting a FCF margin of 26% to 27%.
This means Monday will maintain its Rule of 50 status in 2025, which remains exceptional, even amid weakness. And as I said, this is management exercising a lot of caution.
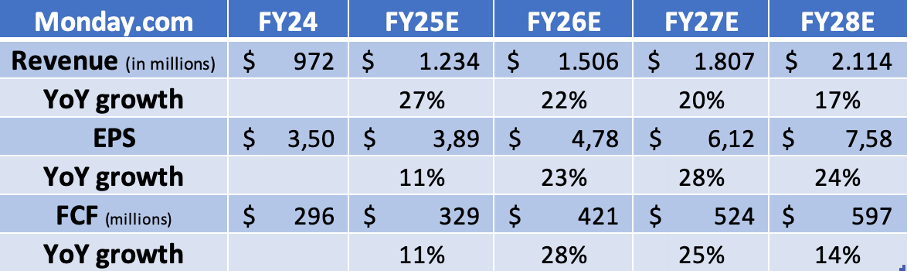
Realistically, based on current industry dynamics and management’s guidance for headwinds to ease toward the end of the year, I believe FY25 revenue will come in closer to $1.234 billion, reflecting growth of roughly 27% YoY, sitting just above management’s guided range and my projection from earlier in the year.
At the same time, I expect margin pressure to persist, reflecting slower top-line growth and higher costs associated with AI implementation. As a result, I anticipate non-GAAP EPS growth of just 11% YoY, which sits slightly below street estimates but comfortably above my prior estimate for only 5% growth, as Monday has still done better in the first half of the year than I expected amid macro headwinds.
Ultimately, this still reflects a fairly optimistic outlook for 2025, primarily as headwinds are expected to ease.
Looking further ahead, management sees its TAM grow at a 12% CAGR through 2028, while the expectation for continued market share gains results in Monday targeting 2027 revenue of at least $1.8 billion, reflecting a minimal 21% CAGR from 2025-2027.
Honestly, this isn’t too bad, although it does clearly suggest that revenue growth will slow down further in 2026 and 2027, more than I expected. At the same time, 20%+ growth is still reasonably strong.
On profitability, Monday is guiding for non-GAAP operating margins of 20–25% by 2027, up meaningfully from the ~13% expected in 2025, and for free cash flow margins “around 30%.” These targets indicate solid operating leverage and continued strong cash generation, even as the company continues to invest in product innovation and enterprise expansion.
My own base case remains aligned with management’s outlook. I see little reason to deviate from these estimates: revenue growth is likely to moderate into the low-20% range as Monday scales and should face growth headwinds ahead, while non-GAAP margins expand steadily toward the mid-20s on an adjusted basis, and free cash flow approaches 30%. It’s a slower growth profile than the market once hoped for, but still robust, especially if Monday executes on its multi-product strategy and continues to win larger enterprise deals.
You can find my updated projections below!
That then brings us to valuation, and it’s at least encouraging to see that Monday shares have become meaningfully more attractive than they were during the peak SaaS exuberance. At a current price of $205, the stock trades at:
53× this year’s earnings and 43× next year’s,
a growth-adjusted PEG of ~2.1×,
and 33× this year’s free cash flow, 26× next year’s.
These are no longer the nosebleed multiples we saw during the pandemic SaaS bubble, but they’re still firmly in premium territory. Relative to peers, however, Monday looks more compelling: most high-quality Rule-of-40+ SaaS companies trade well above 2× PEG, and paying just ~26× next year’s FCF for a business still compounding cash flows at a mid-20% clip is not unreasonable.
On a purely numerical basis, Monday now looks fairly priced for a premium SaaS asset. But valuation alone is not enough. I’m looking for long-term buy-and-hold opportunities with both strong growth and durable competitive positioning.
And that’s where my skepticism remains.
Monday continues to execute well, combining 20%+ revenue growth with expanding margins, strong free cash flow, and a pristine balance sheet. Yet the strategic backdrop is shifting. AI-driven automation is pushing enterprises toward platform consolidation, favoring vendors with deep IT integration, proprietary data, and entrenched workflow control, exactly where Microsoft, Salesforce, ServiceNow, and Atlassian are strongest.
Monday, meanwhile, remains more of an overlay tool: flexible and fast-moving, but lacking network effects, data moats, or mission-critical lock-in. Its edge is still speed of execution — valuable, but not necessarily durable if well-capitalized incumbents replicate features and leverage their installed bases.
If Monday can continue to innovate at its current pace, expand within its 225,000+ customer base, and secure enough large-scale enterprise deployments to establish a core role, today’s multiples could prove justified. However, that path is execution-heavy and strategically fragile, and it’s unclear whether Monday can defend its position once AI agents become deeply integrated into systems of record.
As a result, I’m not convinced its mid-term growth and margin expansion targets will hold through the end of the decade. The risk of slowing growth or eroding competitiveness remains material, and the current premium assumes Monday will keep up with a rapidly consolidating, AI-driven enterprise IT market.
For my own portfolio, this means I need a wider margin of safety. Using a 2027 exit multiple of 38 times earnings, I arrive at a target price of $233, which implies ~5% annualized returns from today — not enough to offset the risks involved.
Simply put, at $205, the risk/reward doesn’t stack up. Monday is a strong company, but the durability of its edge is too uncertain to pay a premium today. Therefore, I remain on the sidelines.
I would only consider buying closer to $165, where the potential upside better compensates for the long-term competitive risks.
Rating: Hold - Accumulate below $165
FY27 Target Price: $233
Implied CAGR from the current price: ~5%
Please leave a like if you enjoyed this post and found it valuable!

Great analysis as always. Difficult to discern which way this will play out. Killed by AI agents or swept along with the tech tsunami?? $165 target seems reasonable and certainly attainable if there is a correction.
have you begun accumulating?