

Last week’s 10% sell-off of Netflix shares after the company reported earnings the prior evening is all the proof you need to realize how short-sighted the markets are and how irrational and emotional they can be.
As a Netflix shareholder, I welcome these irrational market reactions that are often disjointed from fundamentals. These kinds of market reactions allow us to buy great businesses at much better price levels.
Investors just completely misread the Netflix earnings report, responding solely to the headline miss and completely ignoring underlying trends. And even more importantly, they ignored management’s commentary, which very clearly explained that the driver of the Q3 miss reported by Netflix was a one-off.
And yet, shares fell 10% in the following trading session, dropping shares to their lowest levels since May 2025. Yes, the “priced for perfection” argument is entirely fair, with shares trading at over 45x earnings pre-earnings, but I saw no reason to reprice shares in the Q3 report. If anything, Netflix seems to be executing well, delivering on its long-term priorities, reporting continued mid-teens growth (with no signs of weakness), and expanding margins (excluding one-offs).
So, let’s go over the Q3 results in greater detail, putting numbers and performance trends into perspective before making up the balance and updating financial estimates.
Let’s delve in!
Welcome to InvestInsights — an independent equity research publication rooted in long-term, buy-and-hold investing, publishing actionable stock/equity research reports weekly!
📈 You’re reading my latest [FREE] stock analysis. If you like this analysis, make sure to like & subscribe to receive much more like this!
If you’d like full portfolio access (14% CAGR since 2022) & additional exclusive reports, consider becoming a paid subscriber!
Netflix’s Q3 – A solid quarter with one big stain
Netflix reported its Q3 results last week, on October 21, and delivered a solid report, performing about as I expected and showing healthy underlying dynamics.
Let’s delve right into the numbers!
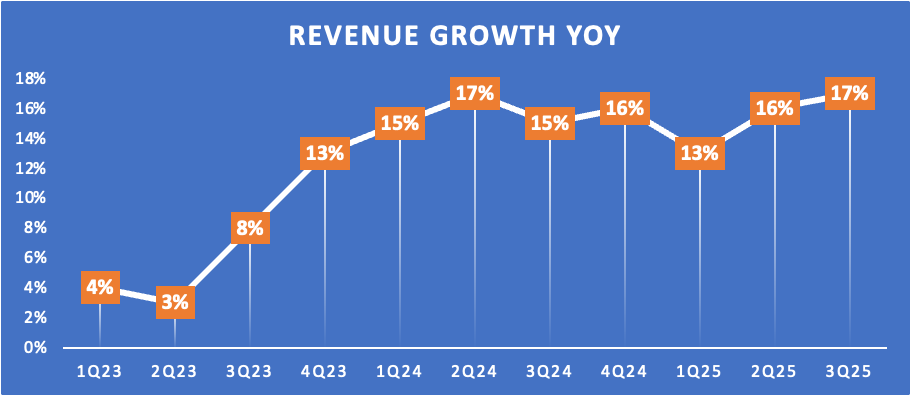
Netflix reported total Q3 revenue of $11.5 billion, up 17% YoY, which was bang on in line with the Wall Street consensus and in line with management’s own forecast. Growth was supported by double-digit growth across all regions.
Isolating this performance, I think we can all agree that Netflix’s 17% revenue growth — the best in just over a year — is nothing short of excellent. The company is seeing excellent momentum in its business, driven by growth in subs, pricing adjustments, and a growing ad revenue stream. As a result, growth accelerated compared to prior quarters, even as it has already reached considerable size and lapped 15% growth last year.
Netflix continues to see plenty of growth levers to sustain this excellent momentum despite its significant size, including continued global expansion, rapid market share gains (it still captures only 7% of its TAM and has plenty of room to keep growing subs), expansion into other content categories, and scaling its ads business, which remains in its very early stages.
On the note of advertising, Netflix provided some interesting commentary. The company recorded its best ad sales quarter ever and doubled its commitments in the U.S. upfront. In other words, Netflix is seeing upfront ad buys from advertisers double. These are advance commitments to purchase ad inventory, which is a very promising signal for the ad revenue growth that’s ahead. Additionally, management confirmed that fill rates continue to improve and are supported by stronger go-to-market capabilities, greater measurement, and better targeting.
Subsequently, management now guides for ad revenue to double in 2025 and could very well see the same in 2026, based on current momentum. Yes, this is still from a very small base, as Netflix’s ads business is still in its very early stages, but the traction it’s seeing is very promising. The business is scaling nicely and is gradually becoming a solid revenue contributor.
Meanwhile, Netflix’s streaming performance and viewership trends also remained strong in Q3, with continued market share gains and healthy engagement. As a result, total view hours in Q3 grew faster than they did in the first half of 2025, which is a promising sign.
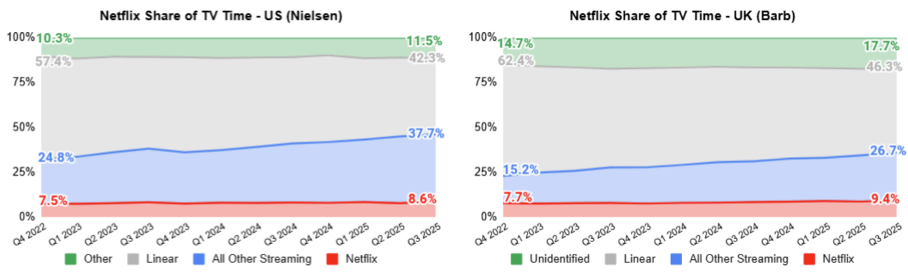
Netflix also hit its highest quarterly view share in the U.S. and U.K., two of its largest markets, growing 15% and 22%, respectively, since Q4 2022, according to Nielsen and Barb. Netflix now captures 8.6% and 9.4% of all TV time in the U.S. and the U.K., respectively, representing substantial progress in just three years. This highlights that Netflix remains the clear leader in streaming and continues to take market share from linear TV — a very positive trend.
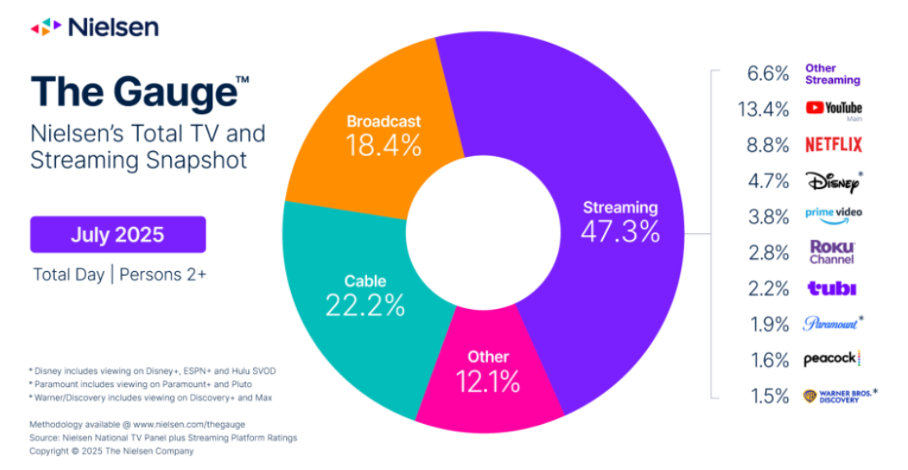
Now, while this market share still seems relatively low, the graph below shows just how powerful and dominant Netflix is compared to its streaming peers. It captures almost 2x the market share in the U.S. as its closest peer, Disney+, which tells you all you need to know – Netflix is still the default in streaming.
Meanwhile, the numbers also show that Netflix still has significant room to grow its share of TV viewership, with its market penetration still relatively low, leaving it with a massive growth runway for years to come.
Helping it maintain and grow this market position + maintain healthy engagement is an unequaled content offering, consisting of both originals and licensed content. In Q2, this included Wednesday S2, Bon Appétit, Your Majesty from South Korea, Happy Gilmore 2, and KPop Demon Hunters, which became its most popular film ever.
Over the years, Netflix has built remarkable in-house production capabilities, building its own IP from scratch. Today, Netflix is among the top studios globally, producing hit after hit, often with a smaller budget. Take gems like Stranger Things and Squid Game, but also K-pop Demon Hunters, which highlights Netflix’s ability to produce large breakout hits and spot cultural relevance.
And then there is licensing, which further adds to Netflix’s moat.
You see, many of Netflix’s rivals are now licensing content back to Netflix simply because they need the cash and the audience that Netflix provides. Most legacy studios built their own streaming services at enormous cost, only to discover that running a global platform that is both profitable and scalable is far harder than it looks. Their libraries, once hoarded to drive subscriptions, are now under-monetized behind smaller or stagnant user bases. Netflix, on the other hand, offers instant global reach and meaningful licensing fees, effectively becoming the most lucrative outlet for older or underused content.
This dynamic strengthens Netflix’s moat in two ways. First, it expands its already unmatched content catalog without bearing the full production risk. Second, it reinforces Netflix’s position as the default streaming home for consumers: even competitors’ shows are available there. The more other studios depend on Netflix for distribution and monetization, the harder it becomes to compete with it, and the stronger Netflix’s flywheel of scale, data, and engagement grows.
It’s a brilliant dynamic.
As for Q3, I am pleased with the top-line results and dynamics. Netflix continues to execute well, with no negative surprises or disappointments.
On that note, let’s get to the bottom-line results, which need a bit more explaining, as it were the bottom-line results that upset investors: Netflix missed the operating margin and EPS consensus by some distance, as well as its own guidance.
However, it is not as bad as it seems.
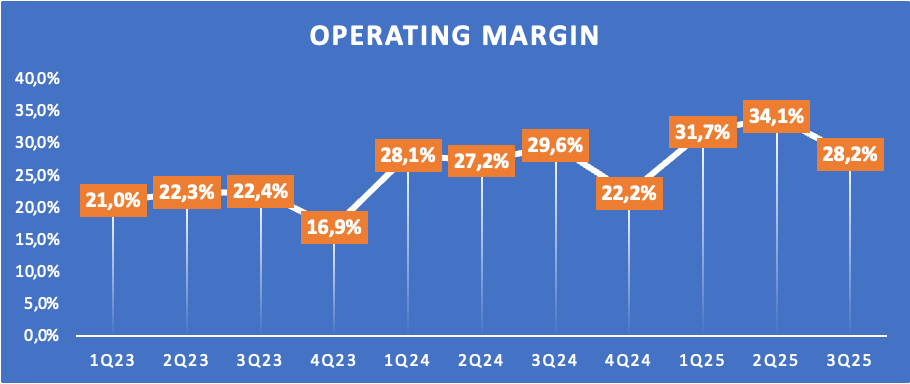
Netflix reported a Q3 operating income of $3.2 billion, up “just” 12% YoY and reflecting an operating margin of 28.2%, down 140 bps YoY, which fell short of management’s 31.5% guidance. However, this wasn’t due to higher structural costs or anything like that. Instead, the operating margin decline was due to a regulatory ruling in Brazil on a unique tax Netflix hadn’t accounted for in its guidance, forcing the company to absorb $619 million in one-off operational costs in its Q3 results and pressuring the operating margin by 5 percentage points.
Let me explain in a bit more detail!
Like I said, the margin hit was due to a one-time hit tied to the Brazilian tax system. Specifically, it concerns the Contribution for Intervention in the Economic Domain (CIDE), a 10% gross tax on certain payments made by Brazilian companies to foreign entities. It’s not an income tax or something unique to Netflix; it applies broadly across industries and will likely affect other multinationals as well.
Here’s what happened: Netflix Brazil pays Netflix U.S. for the services that enable the Brazilian platform to operate. In 2022, Netflix received a favorable lower-court ruling stating that those payments weren’t subject to the CIDE tax, so the company didn’t accrue any expense for it. But in August this year, Brazil’s Supreme Court ruled in an unrelated case that the tax applies more broadly than previously thought, even to service payments that don’t involve a transfer of technology.
That ruling forced Netflix to reassess its own exposure. Management now considers it probable that the tax applies to them, so they recorded a $619 million charge in Q3 to cover potential liabilities from 2022 through 2025. The expense was booked as a cost of revenue, not an income tax, and it reduced Q3’s operating margin by about five percentage points.
Importantly, this is a non-recurring, one-off charge that shouldn’t lead to a material impact in any future quarters.
If we exclude this expense, Netflix’s operating margin would have been closer to 33%, exceeding guidance and suggesting healthy margin expansion, which I believe should be the only takeaway here.
On the cost front, Netflix did well, driving operating leverage. Its sales and marketing expenses continued to outgrow revenue (up 22% YoY), but technology and development costs grew only 16%, and G&A expenses were up only 10% YoY in Q3.
Down the line, this resulted in a net income of $2.6 billion at a 22.1% net income margin, down 190 bps, driven by the lower operating margin. Nevertheless, EPS was up 8% YoY to $5.87, despite a slightly lower margin, offset by strong revenue growth and a lower share count from buybacks.
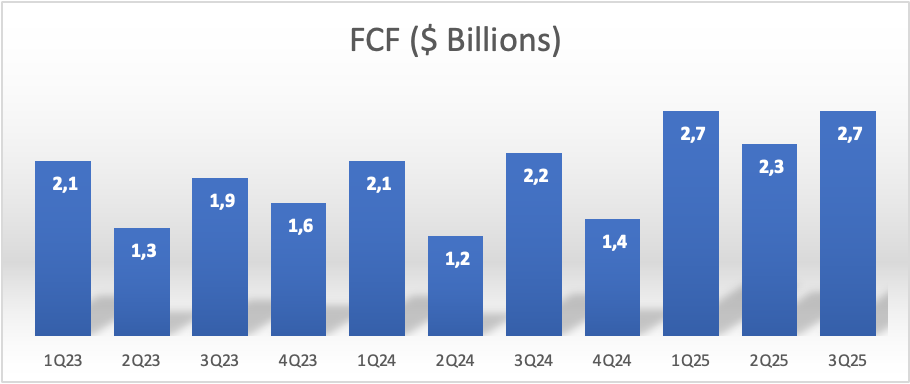
In Q3, management bought back 1.5 million shares for $1.9 billion, leaving $10.1 billion under its current authorization. Positively, this cash was fully provided for by Q3 FCF of $2.7 billion, which reflects a 23% FCF margin, up roughly 100 bps YoY. TTM FCF sits at $9 billion, with Netflix steadily becoming a real FCF machine.
Finally, management also maintains a healthy balance sheet. The company ended the quarter with $9.3 billion in cash and $14.5 billion in total debt. This does reflect a net debt position of just over $5 billion. However, I don’t view this as much of an issue, given that Netflix generates over $9 billion in FCF annually.
Also, reinvestment metrics are sublime, with a TTM ROIC of 28% (trending up nicely) and a TTM ROE of 35%. Those are exceptional numbers.
Ultimately, excluding the one-off tax impact, I will argue that Netflix delivered a solid Q3 report.
The Live Sports Opportunity
In my opinion, the biggest expansion opportunity for Netflix — and one of the primary reasons I bought Netflix shares in the first place — is that I view Netflix not only as the long-term default in movie and series streaming, but also as the most likely to expand into live sports and potentially live television, which I believe to be a massive opportunity for Netflix to expand its platform, improve its value offering, generate additional revenues (through higher tiers), and, of course, grow its user base by a more complete offering making it suitable for an even larger number of people globally.
The opportunity is straightforward. Netflix already dominates on-demand streaming, but there’s a ceiling to how much time people spend watching pre-recorded content. Live programming, particularly sports, taps into a completely different kind of engagement and a totally new viewer base. It’s the only major category of video consumption where Netflix has virtually no presence, and that gap is full of potential.
In other words, expanding its platform in this direction would significantly grow its addressable viewer base, which could bode well for viewership of all its content types.
Furthermore, live sports are among the few remaining “appointment viewing” formats. People don’t just watch a football match or the Olympics; they have to watch it live. That drives engagement, retention, and pricing power.
Every single sports fan who wants to watch F1 or the NFL when Netflix has the rights will subscribe to Netflix. And those subscribers won’t leave, as they’ll keep watching their favorite team or driver, no matter what. In other words, bringing in these viewers would create significant upside on all three factors for Netflix: engagement, retention, and pricing power.
It also opens the door to advertising and sponsorships, something Netflix is just beginning to explore with its ad-supported tier. Owning live moments would give Netflix premium ad inventory that brands pay a huge premium for. Live sports would also reinforce Netflix’s advertising push and premium-tier strategy. Sports content attracts high-CPM ad slots and provides a natural reason to introduce higher-priced or bundled tiers, expanding ARPU without saturating the core market.
We’re already seeing early signs of this shift. Netflix is increasingly investing in massive live events.
The Canelo vs. Crawford boxing match (became the most-viewed men’s championship fight this century).
NFL Christmas Day NFL games.
The Jake Paul vs. Tank Davis boxing match
The MLB’s Yankees vs. Giants season opener in 2026 (part of the new three-year agreement between the MLB and Netflix)
Netflix will reportedly make a bid for the global rights to show one UEFA Champions League soccer game per round for years to come.
While small today, these are proof-of-concept experiments that can scale quickly once Netflix fine-tunes the tech and economics. The infrastructure is already there: its global CDN, massive subscriber base, and maturing ad stack make supporting large live audiences far easier than just a few years ago.
And it doesn’t have to stop at sports. A live layer could extend to news, talent shows, concerts, or award ceremonies. This hybrid (on-demand plus live) could redefine what a streaming platform is and bring Netflix even closer to being a true global television network.
But why is Netflix in particular so well positioned to capture this opportunity, given that live sports streaming rights are generally hard fought for?
First, financial strength. While traditional entertainment companies face declining cable revenues and rising debt, Netflix is moving in the opposite direction, growing profitably, generating over $9 billion in free cash flow annually, and building a balance sheet strong enough to pursue selective, yet impactful, live content deals.
Second, scale and distribution. With over 300 million subscribers across 190+ countries, Netflix offers leagues instant global exposure and marketing reach that no regional broadcaster can match. Its vast user base also helps amortize rights costs, making the economics far more sustainable than for smaller or local platforms.
Lastly, global focus. Netflix doesn’t have to start with the biggest U.S. leagues. It can target emerging or regionally dominant sports, such as cricket in India, Formula 1, or football in Europe, and scale up over time. It doesn’t need to outbid everyone from day one; it can enter selectively, learn, and expand, which is exactly what it’s doing.
All in all, Netflix is in a unique position where strong financials, global scale, technological leadership, and deep consumer relationships converge. These strengths give it not just the means to enter live sports but the ability to win once it does.
So, ultimately, I view this as the biggest opportunity for Netflix over the next decade. This company is in the best position to become the default streaming platform in every household for any type of entertainment.
This gives it a massive TAM and an incredible growth runway. For reference, the global live sports industry is valued at over $400 billion. Of course, Netflix doesn’t need to capture the entire $400+ billion sports market. Even securing a few billion in rights-linked streaming revenue, premium tier upgrades, or advertising inventory could meaningfully move the needle on top-line growth.
If Netflix succeeds here, it doesn’t just win more viewing hours, but it cements itself as the world’s entertainment operating system. That’s the kind of platform optionality I look for as a long-term investor.
On a final note, Netflix management did point out during the earnings call that it isn’t focused on big season packages but, for now, only on single events, so it is scaling slowly.
Want more out of your subscription? Even more content like this weekly?
Consider InvestInsights PRO - $7.50/month ($70/annually)
This gets you:
A guaranteed 6+ stock analyses every month (roughly 2-4 paid-exclusive).
Complete insight into my own portfolio, allocation & performance
(14% return CAGR since 2022).
Instant transaction alerts anytime I make a move (Fully transparent).
A complete overview of all my target prices and ratings (online available).
Outlook & Valuation
Obviously, the $619 million, or 5 percentage point, impact on Netflix’s operating income and operating margin, respectively, will drag on its FY25 performance, as reflected in management’s guidance.
Nevertheless, Netflix’s 2025 guidance looks solid, remaining largely in line with my prior estimates. This was helped by solid Q4 guidance that sat ahead of consensus estimates, adding further confirmation that Q3 was a (negative) standout in terms of margins.
For Q4, Netflix now guides to revenue growth of 17%, similar to Q3, translating into revenue of roughly $11.96 billion, versus a consensus of $11.90 billion. Supporting this growth is a strong content slate, “including the final season of Stranger Things, new seasons of The Diplomat and Nobody Wants This, Guillermo del Toro’s Frankenstein, Kathryn Bigelow’s A HOUSE OF DYNAMITE, Rian Johnson’s Wake Up Dead Man: A Knives Out Mystery as well as more live events including NFL Christmas Day games and the Jake Paul vs. Tank Davis boxing match,” to quote management.
As a result, this growth will continue to be driven by subscriber growth, pricing, and ad revenue. Furthermore, the operating margin is expected to be 23.9%, up a potential 200 bps YoY, as Netflix continues to drive operating leverage. Finally, EPS should be roughly $5.45, versus a consensus of $5.42.
For FY25, this translates into a revenue guide of $45.1 billion, suggesting 16% YoY growth, which sits at the high end of management’s prior guidance and bang on my earlier estimate. Furthermore, management expects its operating margin to be around 29%, down from 30% previously, reflecting the Brazilian tax impact in Q3.
So ultimately, we got FY25 revenue at the high-end of the guided range and an operating margin just 100 bps below prior guidance. On top of that, management raised its FCF forecast for the year, now guiding to $9 billion in FCF, up from a previous range of $8-8.5 billion, reflecting the timing of cash payments and lower content spend.
All in all, this is still robust guidance for 2025, and in no way justifies a 10% sell-off.
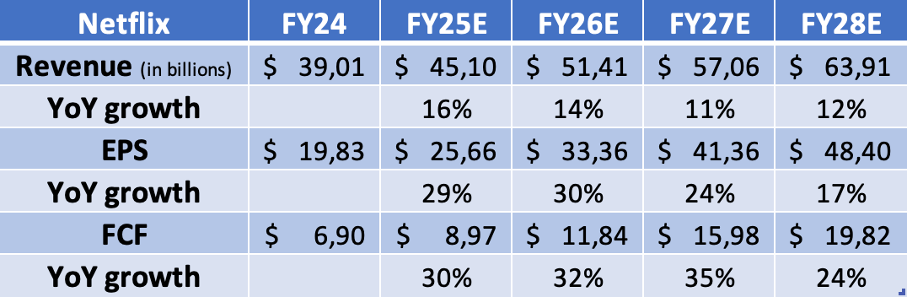
Getting to my own projections, I largely follow management’s guidance for FY25. I maintain my revenue projection at $45.1 billion and lowered my EPS estimate by roughly $0.90 to reflect the lower Q3 profit.
Looking further ahead, as discussed, the outlook for Netflix remains brilliant, with ample room to grow in its existing markets, with the company now just capturing 7% of its TAM and 10% of all spend on TV in even its largest markets, and obvious opportunities to expand its platform into other content categories in the years ahead. As a result, I expect Netflix to keep delivering impressive growth through 2030, with this likely remaining firmly in the double digits, as reflected in my estimates below, and that is without any further move into live sports or similar.
For profits, I expect a margin recovery in 2026 to drive very strong EPS growth, which should moderate in the years that follow. At the same time, I see loads of room for Netflix to keep expanding margins and grow cash flows, so a low twenties EPS CAGR through 2028 is well within reach.
Additionally, I expect rapid FCF growth for Netflix through 2028, assuming similar content-cost growth to recent years and no accelerated push into live sports yet, both of which could impact this number. In a base-case scenario, I believe significant scale advantages, reduced competition, and greater price leverage will allow Netflix’s FCF margin to expand to 31% in FY28, up from 20% in 2025. This is reflected in the numbers below.
That then brings us to valuation, and this is where it gets really interesting, as the recent sell-off has brought Netflix shares right back to earth. While my medium-term estimates have gone up quite a bit since my last coverage of the shares back in late July, Netflix shares have lost 8% of their value.
As a result, valuation multiples have come down a bit. At a current share price of $1,098, we are looking at the following multiples:
43x this year’s earnings and 33x next year’s.
A growth-adjusted PEG of 1.8x
53x this year’s FCF and 40x next year’s FCF.
Obviously, Netflix isn’t a bargain in any way. I mean, paying 43x earnings and 53x FCF is demanding. However, given the sheer quality and growth runway we get for this price tag, I believe these are very reasonable multiples.
No, Netflix isn’t cheap, but few businesses of this caliber ever are. The company combines global scale, recurring subscription economics, pricing power, and a near-unmatched brand in entertainment, all while still growing revenue at a healthy double-digit rate, which I believe it can maintain well into the 2030s, given the growth levers it can still pull and its rapidly expanding margins. I mean, I am now projecting an EPS CAGR of 23% through 2028 and a high twenties FCF CAGR.
In other words, it’s not just a mature media company; it’s a platform with optionality.
So yes, paying 43x 2025 earnings and 53x FCF might look demanding on the surface. But for a dominant, capital-light, cash-generative platform with expanding monetization levers and a widening moat, that premium isn’t just tolerable, it’s justified.
Don’t underestimate the durability of Netflix’s growth and the strength of its positioning as the global leader in streaming.
When we assume a 36x 2027 exit multiple, which I think is more than fair, all things considered, I calculate an end-of-2027 target price of $1,489. From a current share price of $1,098, this reflects potential annualized returns of 14.5%.
In conclusion, at these prices, I believe $NFLX shares represent excellent value, with a favorable risk-reward balance. I think there is plenty of upside to my estimates, and with a cautious medium-term multiple translating into annual returns approaching 15% annually, I really like the value on offer.
In my view, the sell-off we saw last week is an excellent opportunity to buy Netflix shares on irrational weakness.
I did!
Rating: Buy - Accumulate below $1,130
FY27 Target Price: $1,489
Implied CAGR from the current price: ~14.5%
Please leave a like if you enjoyed this post and found it valuable!

great writeup
great analysis of the brazilian tax situation! netflix actually had another regulatory clash brewing that didn't get much attention. the board rejected jay hoag's resignation in june 2025 after shareholders voted him out 259.8m to 71.4m votes. that's a massive governance red flag that could signal deeper management entrenchment issues beyond just the brazil tax hit.