

SAP has been one of the market’s more brutal repricings this year, and I mean that literally: shares are down 34% YTD and 44% over the last twelve months, wiping out a staggering amount of market cap from a company that, by every operational metric, just delivered a good quarter. That disconnect alone tells you this isn’t really a story about SAP’s business breaking; it’s a story about a narrative getting priced in faster than the fundamentals can keep up with, and last Friday’s 9% pop on Q2 earnings that were no more than solid was the market’s first tentative acknowledgment that maybe, just maybe, it overshot.
And to be clear, the Q2 numbers genuinely were all right. Cloud growth held firmly in the double digits, current cloud backlog reaccelerated even against a tough comp, and renewal rates stayed rock-solid, all while SAP navigated real macro turbulence from the Middle East conflict weighing on deal-signing. It just showed good execution across the board and not a single sign of AI disruption in a genuinely difficult environment.
Nonetheless, the only important question seems to be whether Agentic AI structurally erodes the value SAP has spent decades building. And some caution does seem to be justified.
So, following the Q2 results last week and a turbulent first half of 2026 for the stock, today I want to update my SAP thesis by breaking down the Q2 results and developments and delve into the question of whether AI is a threat to SAP or an opportunity – in other words, are concerns overblown or justified – before updating my financial model and view of the German software giant.
Without further ado, let’s delve in!
Welcome to InvestInsights — an independent equity research publication rooted in long-term, buy-and-hold investing, publishing actionable stock/equity research reports weekly!
📈 You’re reading my latest [FREE] stock analysis. If you like this analysis, make sure to like & subscribe to receive much more like this, weekly!
Financial & Performance Review
German enterprise software giant SAP released its latest financial results just last week – its Q2 2026 – and it delivered solid results, surpassing expectations and showing good, accelerating deal momentum, enough to relieve concerns over AI disruption, even as the company is navigating a tough macro environment.
Really, while the stock is obviously out of favor, SAP’s numbers look good.
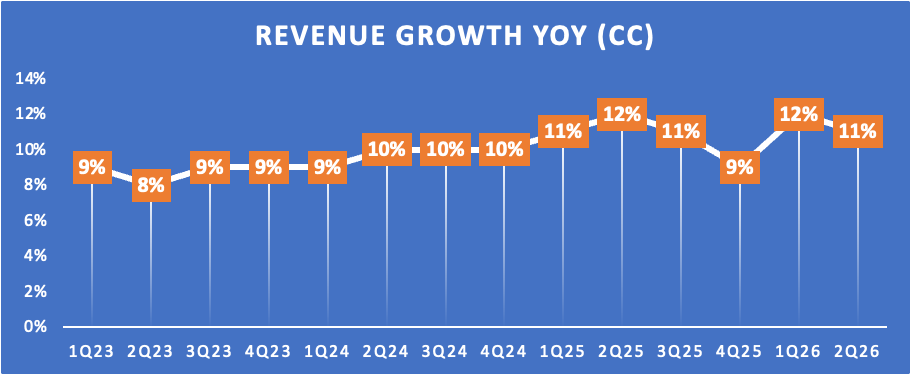
SAP reported total Q2 revenue of €9.9 billion, in line with expectations and up 11% YoY in constant currency (9% reported). This reflects a slight slowdown from 12% growth in Q2, but still solid and not unexpected, given a tough and complex operating environment, with the ongoing conflict in the Middle East weighing on customer sentiment – customers in the Middle East but also outside of it are less eager to sign a multi-year contract in the face of uncertainty.
Considering this headwind, SAP delivered a good quarter in terms of headline growth, largely in line with the last two years.
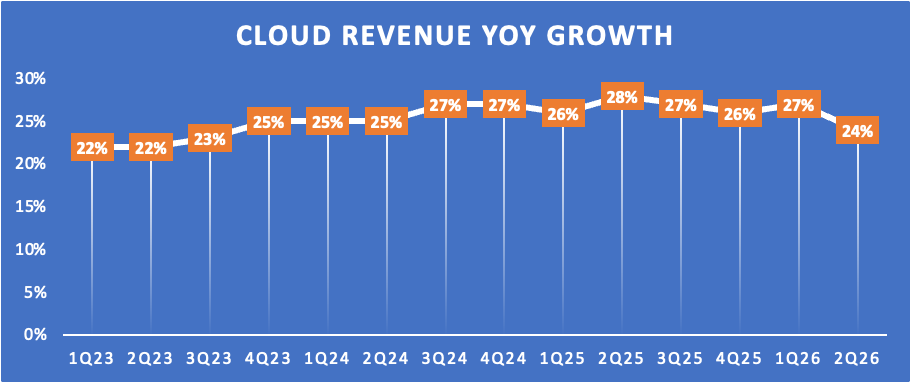
Cloud revenue continues to be the primary driver of growth for SAP, up 24% YoY to €6.3 billion, with cloud ERP growth of 27%, driven by a continued migration of existing customers from legacy software licenses to the cloud. Crucially, a customer that fully migrates its on-prem estate to the cloud ends up paying roughly twice what it was paying in pure maintenance, so this shift alone is nearly a 2x opportunity for SAP within its existing base, hence the rapid growth.
The reason is that the old model separated a one-time perpetual license from a maintenance fee (roughly ~20% of license value per year). The subscription model folds license + maintenance + hosting infrastructure + some services into one recurring number, so the conversion isn’t just a wrapper change; it’s a genuine expansion of wallet share. On top of that, it gives SAP a huge cross-sell opportunity for more cloud products, growing value per customer even further.
Nonetheless, this 24% cloud revenue growth in Q2 was a notable slowdown from recent quarters and the slowest growth since Q3 2023, but this was pre-announced. For one, it is lapping a very strong Q2 last year, and Q1 2026 saw some one-off tailwinds that wouldn’t last, hence the sudden drop in growth. Furthermore, it reflects softness in demand in the Middle East, with some governments and enterprise customers delaying planned technology spending and deal-signing amid the ongoing conflict.
So, most importantly, it doesn’t reflect real underlying issues. Also, the forward-looking current cloud backlog number is trending in the other direction, so I wouldn’t worry about this short-term slowdown, mainly the result of outside factors.
Of course, this strong cloud growth was offset by a steep decline in software licenses revenue, down 32% YoY, reflecting the shift from legacy licensing to the cloud. Additionally, services revenue was down due to SAP temporarily reallocating consultants to build agents and foster AI adoption, leading to a 2% drop in service revenue.
However, the much more important number for investors to watch is the current cloud backlog, the best forward-looking indicator and the main focus for Wall Street.
For perspective, the current cloud backlog (CCB) is the contractually committed cloud revenue SAP expects to recognize over the next 12 months, based on cloud subscription contracts already signed as of the reporting date. So, it is a bit like RPO but exclusively for cloud and only the next 12-month value, giving a sense of what is coming and of deal momentum (new contracts signed, renewals, expansions, minus churn and losses).
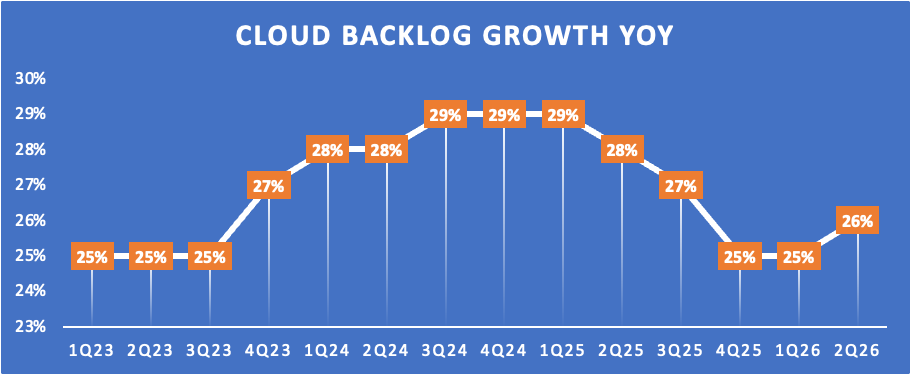
Crucially, SAP delivered solid CCB numbers. This was up 26% in Q2 to nearly €23 billion, accelerating from Q1, although this does include a nearly 1 percentage point tailwind from the Reltio acquisition, so on a comparable basis it is mostly stable. Still, that does reflect good bookings momentum, maintaining a strong growth rate despite lapping a very strong quarter last year and working from a large base. Also, CCB is now outgrowing cloud revenue again, which is a promising signal for growth in the year ahead, likely accelerating cloud growth.
Especially operating in a challenging macro and with deal-closing headwinds in the Middle East, this cloud backlog momentum is impressive, better than I expected.
On that note, let’s move to the P&L. SAP reported a Q2 gross margin of 73.4%, down 20 bps YoY, driven by a 60 bps decline in the cloud gross margin to 74.6% amid margin pressure that has been going on for a few quarters now, following strong margin expansion in recent years.
The primary driver of this pressure is SAP’s roll-out of AI and data products, which are driving rapid growth in infrastructure and token costs (the cost of high compute usage), as well as spend tied to rolling out AI internally, which together are driving strong growth in the cost of sales. Positively, management claims this is only temporary, with costs very high during the ramp phase, but this should ease over time as the cost per action goes down quite quickly, leaving room for a recovery later on. On top of this, the recent acquisitions of Reltio, Dremio, and Prior Labs are all dilutive to margins in the near term due to high data/AI costs, which will be monetized over time.
So, this gross margin pressure should ease over time, but will probably remain a drag in the near future, likely through at least early 2028.
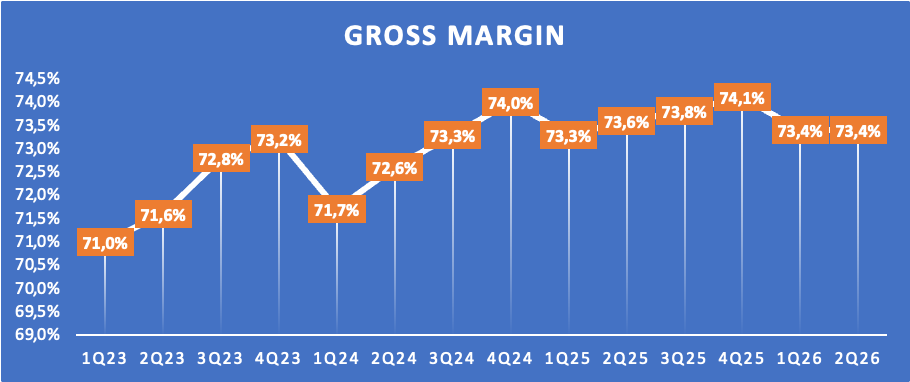
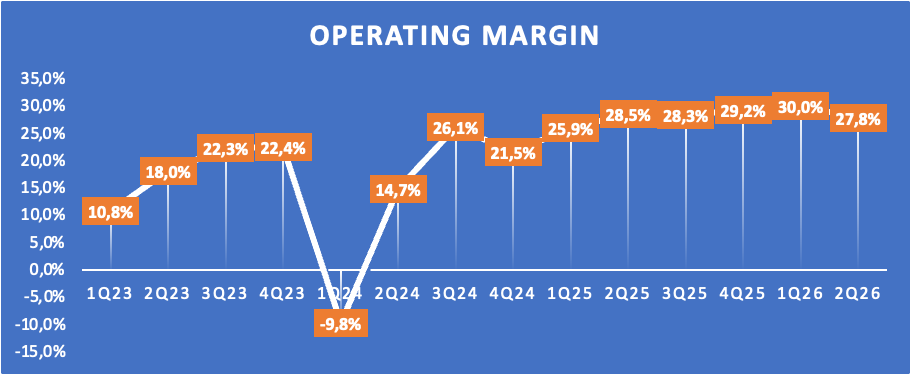
Moving down the P&L, SAP reported a Q2 operating profit of €2.7 billion, up 9% YoY and reflecting an operating margin of 27.8%, down 70 bps YoY or 40 bps in constant currency. This reflects gross margin pressure, a slight drop in cloud and total revenue, accelerated investments in R&D, higher marketing expenses due to the launch of the Autonomous Enterprise, and a dilutive impact from acquisitions.
Headcount was up 3% YoY in Q2, driving a 14% increase in G&A expenses, reflecting the aggressive hiring of data scientists, data engineers, and full-stack developers for industry AI, which come with a high price tag.
Positively, management indicated that it will now slow hiring significantly, so we should see pressure ease in this department. Additionally, during its investor event earlier this year, management reaffirmed its guidance for expenses to grow at 80% of revenue in 2026 and 90% in 2027, suggesting continued operating leverage to offset some of the gross margin pressure, especially through a lower S&M and R&D expense ratio.
I remain quite bullish on SAP’s ability to deliver solid margin expansion through 2030.
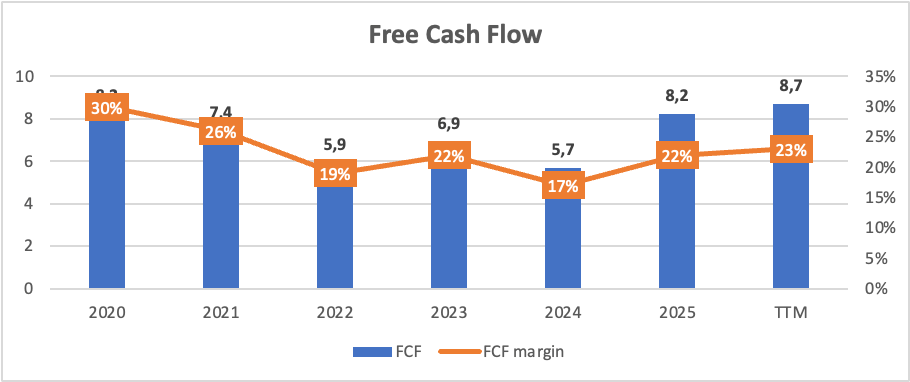
Eventually, the deceleration in revenue growth and margin pressure translated to an EPS of €1.59, up 6% YoY. Finally, SAP reported an excellent Q2 FCF of €3 billion, up 27% YoY and reflecting a FCF margin of 30%. This brings the TTM FCF to €8.7 billion at a 23% FCF margin, showing continued expansion from recent years.
Thanks to these healthy cash flows, SAP continued to strengthen its balance sheet, ending the quarter with €11.6 billion in total cash (up €2 billion from the start of the year) and a total debt of €9.9 billion, leaving it in a healthy net cash position.
Finally, it is worth highlighting SAP’s excellent reinvestment metrics, which have continuously improved over recent years. Its TTM ROIC now sits at 19.8%, and its TTM ROE is 18.3%, both excellent numbers trending in the right direction and comfortably ahead of the costs of capital. SAP is showing a good ability to generate shareholder value.
Ultimately, I think SAP delivered a solid quarter. It wasn’t a standout in any way, but it was a resilient performance in challenging operating conditions, showing no signs of any AI-related disruption and even accelerating CCB growth. Sure, there is some margin pressure, but this doesn’t worry me given the cause and room for expansion over time. Meanwhile, SAP remains in excellent financial health and shows it knows how to deploy cash with good ROI.
And on top of all of that, SAP shares offer a pretty sweet dividend. Shares currently yield 1.84% based on a 38% payout ratio, the highest yield and lowest payout in years. That is a pretty sweet bonus.
The AI Disruption Narrative. Real or Overblown?
While SAP delivered solid Q2 numbers and showed no signs of AI disruption in its backlog momentum, the primary reason SAP shares are down 34% YTD and 44% over the last twelve months, even after last Friday’s 9% pop, is the broader fear that SAP’s SaaS model might be under pressure from Agentic AI. So, this is definitely worth delving into in detail again, as it defines whether SAP is worth owning long-term and whether current levels actually represent great value or justified concerns.
First, it’s important to understand what the threat actually is. SAP’s system of record — the data, process logic, and governance running a company’s financial, supply chain, and HR backbone — gives it a moat that AI can’t simply route around. Therefore, the real threat isn’t disintermediation of that core and disruption of the business model (which is the broader fear driving the SaaS sell-off); SAP’s core offering will remain critical to any business, with or without AI. No, for SAP, it’s about which layer of the AI stack captures the value.
You see, SAP’s moat has always been owning the system of record (the data, the process logic, governance). But agentic AI introduces new layers on top, such as orchestration, integration, and workflow automation, which move the customer interaction elsewhere, and other players are aggressively contesting those, including ServiceNow, Salesforce, Google, and Claude, which all want to own the orchestration layer that sits between the data and the end user, the layer that decides which agent does what, when, and across which systems.
And this is where I think the bear case actually has some teeth, because owning the system of record was sufficient in a world where humans logged in and clicked through SAP’s own UI, but agentic AI doesn’t care whose interface it’s using; it cares about which agent gets to orchestrate the workflow across a company’s entire tech stack, SAP’s ERP included.
The problem is that SAP has to open its data to make the agentic story work, but that same openness is what lets orchestration-layer competitors plug in around it. If ServiceNow’s agents become the default place enterprises route their automated processes through, or if Salesforce’s Agentforce becomes the connective tissue between sales, service, and operations, SAP risks being reduced to a very well-defended data warehouse that other companies’ agents simply call into, letting SAP capture less of the economic value even if its core revenue holds up.
In other words, the fear isn’t “nobody needs a system of record anymore”, but it’s “SAP gets relegated to a commoditized data plumbing layer while someone else’s agents sit on top to capture the premium economics of owning the full customer interaction.”
So, really, there are two ways this can go for SAP, and in this early stage, I am struggling to determine where this is going.
The bullish scenario is that SAP successfully extends its moat upward, and its Business AI Platform, Joule Studio, and the governance layer become good enough and embedded enough that large enterprises run their agent orchestration natively inside SAP rather than bolting layers on top. In this world, SAP keeps capturing a growing share of the AI budget line, not just the ERP line, making AI a huge opportunity.
However, the other option is that SAP retains the data/governance layer (which is sticky, regulated, and hard to displace, hence 98% renewal rates persisting. This piece won’t be disrupted) but the actual orchestration and interaction layer, the thing employees use daily, the thing that captures the “AI budget” line item, migrates to Microsoft 365 Copilot, Google Workspace agents, or Salesforce/ServiceNow control planes calling into SAP’s data via API. In this world, SAP doesn’t disappear or even necessarily shrink in absolute revenue, but it becomes more of a utility/infrastructure business with capped growth potential, still essential, still cash-generative, but commanding lower strategic centrality and probably a lower multiple than the market has historically paid for an “applications” company that owns the full customer relationship.
I am confident in SAP’s future as a system of record and its ERP moat, but I am unsure whether AI will be a huge opportunity or a technology shift that forces SAP to the background, losing the customer interaction value.
Positively, SAP is innovating at a high rate and aggressively positioning itself as the orchestration layer, operating from a position of serious strength.
You see, SAP’s bet is that raw business data isn’t enough; you need understanding. A generic AI model can read a purchase order, but it doesn’t inherently know the difference between a one-off purchase order and a long-term blanket agreement, or how a sales invoice connects to accounts receivable aging. SAP’s argument is that it can encode that deep, specific business knowledge, which involves thousands of processes and 7 million+ data fields, into AI agents in a way no outside AI vendor can, because that knowledge only exists inside SAP’s own systems and decades of configuration.
Crucially, what’s actually proprietary isn’t the data itself but the interpretive layer on top of it: SAP’s Knowledge Graph, its domain models trained on its own codebase, and, critically, the encoded understanding of each individual customer’s specific configuration. That configuration-specific knowledge doesn’t live in the data records themselves, but in SAP’s own system metadata and code, which an outside party reading the data through an API will never get access to.
And that is a strong argument in SAP’s favor, especially as we can increasingly see that the key to AI working and generating ROI inside the enterprise isn’t about the models but about the data and the thorough understanding of what it means.
So, yes, SAP is building the open protocols (MCP, A2A support) and APIs that let third-party agents call into its data for commercial reasons — it wants Microsoft, Google, and Anthropic-hosted agents to be able to reach SAP data, because refusing that access would be commercially indefensible in an interoperable-agent world, but the argument toward customers is that these third-party’s lack the deeper understanding SAP has built over decades. And given its deep integration, that is a strong argument.
Of course, once third-party models have access to SAP data, they could plausibly infer or replicate over time by observing enough of a customer’s configuration and business logic, so this isn’t a wall, but more a head start for SAP.
Another edge SAP has over many competitors is the sovereignty argument. Amid rising distrust of US hyperscalers among European governments and regulated industries, tightening EU regulation (the AI Act, GDPR enforcement, national certifications), and general geopolitical nervousness about depending on foreign infrastructure for critical national and corporate data, SAP’s unique European-centered position is interesting.
This means SAP isn’t trying to out-build AWS, Azure, or Google Cloud on raw infrastructure sovereignty, as those hyperscalers all offer their own “sovereign” variants too. SAP’s edge is that it controls the application layer, so the business processes, data models, and compliance logic where sovereignty actually gets operationalized, not just the infrastructure underneath, giving it a much stronger sovereignty argument than its larger U.S. counterparts.
It lets SAP frame sovereignty as an operating model for how AI runs in production (governed, auditable, jurisdictionally controlled at the point where business decisions get made), rather than just a checkbox about which data center a server sits in. This gives it a genuine edge.
Overall, SAP genuinely seems well positioned to capture at least part of the customer AI interaction. For the ERP part of the business at least, its edge in offering deep, governed reasoning over the transactional core of the business is hard to replicate, likely giving the best ROI. So, for deploying agents in this core part of the business, doing so through SAP itself seems to make sense. But I doubt SAP can expand this to become the broader orchestration layer, where ServiceNow is looking like the better alternative. But it isn’t a winner-takes-all market!
So, basically, what SAP now tries to sell to its customers is three layers stacked together, now sold as one thing: a place to store and connect trusted business data (Business Data Cloud), a place to build and run AI agents on top of that data (Business AI Platform / Joule Studio), and a growing library of ready-made agents that actually do the work.
Ultimately, what it targets is that instead of an employee logging into SAP to manually process an invoice, an agent does it automatically, checks it against the rules and permissions it’s allowed to operate within, and only pings a human when something needs judgment. SAP’s long-term bet is that it can turn itself from a company that sells you software to run your business into a company that sells you a workforce of AI agents that already understand your business, because they were built on top of decades of your own company’s data and rules already sitting inside SAP.
Makes sense, right?
Ultimately, whatever way the pendulum swings, this is where SAP’s primary long-term opportunity sits. And momentum here looks genuinely promising, with AI and SAP Business Data Cloud included in 90% of its top 50 deals in Q2, showing promising adoption of exactly these new products.
For reference, SAP Business Data Cloud (BDC), announced in early 2025 and rolling out through 2026, is the data layer. It consolidates what used to be three separate products into one governed platform, and it now connects out to Databricks and (arriving through 2026) BigQuery, Snowflake, and Microsoft Fabric. The pitch is that it gives AI a single trusted “business context” layer spanning SAP and non-SAP data, rather than agents reasoning over fragmented, ungoverned data.
SAP Business AI Platform, unveiled at Sapphire in May 2026, is the newest umbrella, packaging everything together with SAP’s AI Foundation. This includes Joule Studio, which lets customers create and extend agents using any LLM, including Anthropic, Cohere, Google, Mistral AI, OpenAI, and other open-weight models. The models created with Joule Studio have full access to SAP’s data and knowledge, as well as non-SAP data through BDC, allowing them to run fully autonomously. Finally, SAP provides governance, managing the agents across the complete agent life cycle, including SAP, partner, and customer build agents to meet compliance frameworks and data privacy requirements from over 130 countries.
And SAP is innovating rapidly on the AI agent front. It now ships 40+ specialized agents and 2,400+ “skills” across roughly 35 solutions, up from essentially nothing 18 months ago. Furthermore, it will release close to 50 assistants by the end of Q3, underpinned by more than 400 Autonomous suite agents by the end of the year, rapidly bringing new AI functionality to market.
What kind of agents should you think of? An example is a Cash Management Agent that reads daily bank statements and automates reconciliation, driving 70-80% time savings. Or a Dispute Resolution Agent that matches invoices to purchase orders and resolves simple discrepancies end-to-end.
In terms of pricing, SAP uses “AI Units”, so a usage-based structure for its Agentic AI solutions, though we are very early in this ramp, so it’s not really contributing to the top line numbers yet, unlike what we see from ServiceNow.
Finally, regarding the threat of seat erosion, SAP generates just 35% of its cloud revenue through seat-based pricing, and this is expected to fall below 30% by 2030. The remainder comes from value-based and consumption-based pricing. Today, consumption is just 10% of cloud revenue, but amid AI adoption of new modules, this is expected to grow to over 30% of revenue by 2030. So, honestly, seat erosion isn’t a huge threat to SAP.
So, what really is the conclusion here?
I don’t think this is a coin flip, but it isn’t a clean bull case either. My best estimate is that SAP captures a meaningful, durable slice of the AI value, specifically the agents that operate inside its own transactional core: cash management, invoice matching, dispute resolution, the deep-in-the-weeds ERP work where understanding a customer’s exact configuration is worth more than raw model horsepower. That’s real, it’s monetizable through AI Units and rising consumption revenue, and it’s defensible for the reasons laid out above: the interpretive layer, the sovereignty argument, the sheer weight of decades of encoded process logic.
What I don’t buy is SAP winning the broader orchestration layer, the place where an employee’s daily AI interaction actually happens across sales, service, IT, and everything else outside SAP’s four walls. ServiceNow, and to some extent Microsoft and Google, simply look further along and more natively built for that horizontal role, and I don’t see SAP closing that gap from a standing start, however fast Joule is shipping features.
The good news is that SAP doesn’t need to win that broader fight for this to be a sound long-term holding. Even in the more conservative scenario, SAP keeps its core untouched, keeps growing consumption revenue as agent adoption ramps inside ERP, and keeps its renewal rates intact, just without the full re-rating a “SAP owns the entire AI stack” outcome would justify. That’s a business that still compounds at a good rate with a very reliable core.
On that note, let’s get to the outlook!
More content like this? Consider InvestInsights Premium
InvestInsights Premium is designed to help you find best-in-class compounders, identify deep-value opportunities, avoid costly mistakes, and stay focused on fundamentals when markets get noisy, with full transparency into how I make decisions over time.
In practice, this gets you:
6–8 Research Reports per month, 2x more than free subs do, which includes 3-4 Deep Dives!
Full visibility into my personal portfolio, including allocations, transactions, and conviction levels
An overview of target prices and ratings, updated weekly, all available in a web-based Hub.
Price tag? Only $95 per year or $9.50 a month. That comes to just $1 per analysis, with the rest provided at no cost.
Sound useful? You can upgrade to Premium today using the button below!
Outlook & Valuation
As always, let’s start with management’s guidance, which it largely reaffirmed following the solid first half results. Management still guides for total cloud and software revenue of €36.3 – 36.8 billion, up 12-13% YoY at constant currency, so solid and accelerating growth in the core business.
This includes cloud revenue of €25.8 – 26.2 billion, up 23-25% YoY, which does seem a bit cautious amid some near-term dealmaking uncertainty due to the Middle East conflict. This remains the key drag on SAP’s near-term growth and visibility, weighing on customer decision-making, simply delaying deal completions, so I understand management’s caution, especially with the conflict escalating again in recent weeks.
On the bottom line, management has lowered its operating profit outlook by €100 million to a range of €11.8 billion to €12.2 billion, up 13-17% YoY. The reason for the outlook cut is the dilutive impact of the recent Dremio and Prior Labs acquisitions, which will create a very low triple-digit million drag on H2 operating income not included in the previous guidance. Nonetheless, management still targets an 80-90% expense-to-revenue ratio despite the increase in M&A-related costs, thanks to the impact of AI-driven productivity and operating leverage.
So, management continues to guide for healthy margin expansion. On top of that, it expects a FCF of roughly €10 billion, up 21% YoY, and a FCF margin likely approaching 25%, reflecting great improvements in cash flows.
Overall, management’s guidance looks solid, although I had hoped for a small raise. But considering the impact from acquisitions on the bottom line and the Middle East uncertainty, I get the conservative approach.
With regard to the current cloud backlog, management also reaffirmed its expectation of a slight deceleration in growth over the course of the year, despite the slight uptick we saw in Q2. Of course, this also reflects the ongoing Middle East conflict, to which SAP has more exposure than other SaaS names, but is also the reality of changes in the dynamic driving this explosive cloud growth.
You see, the bulk of this CCB growth is still substantially a base-conversion story rather than pure net-new demand. Every ECC customer that signs a RISE/S4 Cloud deal counts as new cloud bookings even though it’s the same customer just changing how they consume software they already had. Yes, the 2x revenue conversion rate is excellent, but the runway is very clearly capped. At some point, the migration slows and reaches maturity – the “migration tailwind” portion of growth is a bounded pool that depletes over time, removing the primary driver of today’s cloud revenue growth.
Positively, this migration still has some legs. According to SAP, over 60% of its legacy ECC customer base has not moved to the cloud in any form, and SAPinsider’s 2026 benchmark found 55% of organizations have deployed S/4HANA or S/4HANA Cloud in some form, but only 34% have fully completed the transition. This tells us we are not anywhere near a cliff, with this likely remaining a tailwind into the early 2030s, although to a lesser extent due to the larger base. And we’ll already see some moderation in momentum in the second half of this year.
Cross-selling its newer products – its Business Technology Platform (BTP), Business Data Cloud, and now the Business AI Platform – does add a new growth layer, as does potential AI monetization, which is a huge incremental, usage-driven opportunity. But this is much more unpredictable, not an area where SAP can leverage its existing dominance.
In other words, cloud revenue and CCB growth are very strong in the low-to-mid twenties today, but we should see this decelerate as early as the second half of this year for CCB, with cloud revenue likely following in late 2027 and 2028. Of course, the negative impact of lost licensing revenue will evaporate at a similar rate, which I think likely means growth will remain in the low-teens through 2030 and ease toward the high-single digits beyond under base-case assumptions, assuming SAP can at least in part prevent becoming no more than an underlying data layer.
Unless we see strong data cloud and AI adoption and real monetization on that front, I don’t see this as a high-growth story, with cloud growth moderating as the licensing headwind disappears. Nonetheless, that makes SAP a pretty interesting prospect to own long-term. Yet, the risk of it being pushed to the background by better AI orchestration layers does exist, which could significantly reduce its value and growth runway – that is a risk to keep in mind.
Let me delve into my own financial framework. Despite strong H1 results, I have significantly cut my medium-term expectations to reflect management’s clear guidance for moderating CCB growth (earlier than I anticipated before), the uncertainty regarding cross-sell success as migration-driven growth eases, and significant competition in the AI orchestration layer SAP is targeting. Really, I am just less confident SAP can capture value outside of ERP and on top of migration-driven upside, now assuming more limited upside from newer products compared to before. I do believe SAP can capture some value with its Data Cloud and AI products, but I am cautious in my assumptions given few proof points and serious competition.
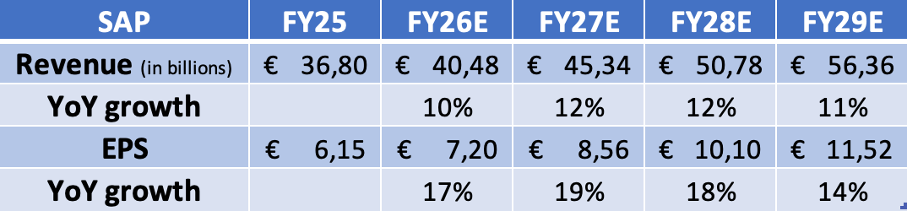
Therefore, I now expect 2026 growth of roughly 10% to €40.5 billion, accelerating to 12% in 2027 and 2028, as SAP continues to deliver strong cloud revenue growth currently visible in the CCB. I expect cloud growth to remain in the low-20s in these years. Compare that with a smaller licensing headwind, and you get an improvement in total growth. I do expect this growth to moderate again beyond 2028 due to the aforementioned reasons, with the big upside potential hinging on SAP’s ability to cross-sell its Data and AI products. However, I think a low-teens growth rate is realistic through 2030 based on the migration runway still ahead.
On the bottom line, the outlook for SAP is quite strong. I expect healthy operating margin expansion in 2026 to drive up EPS 17% YoY, and this trend to persist through the end of the decade. SAP is now exiting a period of elevated costs to set itself up to capture the cloud and AI opportunity, and while higher compute and AI costs will be a drag in the early stages, I do expect SAP to deliver solid operating margin expansion in 2026-2029, driven by healthy top-line growth and strong operating leverage. This should allow for profits and cash flows to grow ahead of revenue in the mid-to-high double digits. Although trimmed a bit from previous expectations, it creates a pretty compelling medium-term outlook for SAP.
These assumptions are reflected in my updated financial framework below!
That brings me to valuation, and with SAP shares still down 23% YTD and 37% over the past year, even after a 15% run since releasing its Q2 results, SAP shares continue to be priced pretty attractively, very much reflecting the market’s disruption concerns. At a current price of €156, shares trade at:
21.7x 2026 earnings, about in line with the 10-year median but at a 6% discount to the post-COVID median, which is when SAP’s growth accelerated amid its cloud transformation.
A PEG of 1.25x
18x 2026 FCF (consensus), a 33% discount to the 10-year median
Clearly, SAP shares are quite attractively priced; there is no denying it. Paying a sub-22x earnings and 18x FCF for a business forecasted to grow its revenue by low-double digits and its FCF and EPS at a high-teens rate isn’t a bad proposition, especially when the product is extremely sticky, deeply integrated in the IT stack of over 400,000 customers – AI won’t change that.
Sure, 22x earnings is only about in line with the 10-year average, but let’s not forget that for most of that period SAP was a legacy software provider and a mid-single-digit grower, simply trading at a premium reflecting its resilient, anti-cyclical nature. Today, we are looking at a fundamentally different business, still formidably resilient but now cloud-based and growing by double digits consistently. That one absolutely deserves a higher multiple based on the core business. And then we aren’t even addressing a 33% lower FCF multiple, which just reaffirms we are looking at a fundamentally more attractive business that hasn’t repriced accordingly.
And the only reason it hasn’t is the AI disruption narrative hanging over the entire sector. So, let me reaffirm again: in my eyes, SAP isn’t at risk of being replaced or disrupted; its core business is safe. The real risk for SAP is losing the customer interaction and turning into a utility/infrastructure business with capped growth potential, still essential, still cash-generative, but commanding lower strategic centrality and, therefore, lower value. And that risk is very real, justifying somewhat of a conservative stance, in my opinion.
I simply don’t think SAP is as well positioned as, say, ServiceNow or Datadog, to capture the rapidly growing AI budget, and that creates uncertainty the market doesn’t like.
So, taking a cautious approach, let’s apply a 22x earnings 2028 exit multiple to the shares, in line with the 10-year median and applying plenty of downside protection on top of already conservative financial forecasts. Using this multiple and my current 2028 EPS forecast, I calculate an end-of-2028 target price of €222, implying annualized returns of about 17%, including dividends.
That clears my 15% threshold and actually reflects a pretty attractive risk-reward, with plenty of upside to my current financial forecasts if SAP can monetize its AI and Data products, at which point a higher multiple is also very much justified. At the same time, current numbers are pretty de-risked, so I deem downside protection very solid – if SAP can’t capture the AI budget, you can still expect pretty decent returns from this ERP giant.
Therefore, I don’t think today’s price levels are a bad place to pick up some SAP shares. Ideally, I would like to buy below €145 to further improve the risk-reward, but I can’t deny SAP shares look like very good value at €156 today.
Rating + fair value: Buy — Accumulate below €156
2028 Target Price: €222
Implied CAGR from current price: ~17%
Please leave a like if you enjoyed this post and found it valuable!
