

Last week, French industrial giant Schneider Electric released its second-quarter results and delivered very strong numbers that exceeded my expectations by a good margin and allowed management to raise FY26 guidance quite significantly. The company is fully benefiting from strong broad-based electrification-related demand, as highlighted by healthy growth in all regions, all markets, and all product categories, but, above all, it is benefiting hugely from the data center build-out.
Ultimately, every data center built to support AI workloads and cloud computing requires a substantial portion of Schneider’s core product portfolio – everything a data center needs in electrical components and systems on the power and cooling side – making Schneider another direct beneficiary of growing hyperscaler CapEx. For a data center campus costing several billion dollars to build, the electrical infrastructure alone can represent hundreds of millions of dollars in equipment spend. And this is very clearly showing up in Schneider’s Q2 results, being one of the primary suppliers.
But first, for those of you not quite familiar with Schneider Electric (you should absolutely check out my Deep Dive from March, found here), Schneider is a French multinational energy technology company, one of the world’s foremost players at the intersection of electrification, digitalization, and industrial automation.
To make that more concrete, the company ensures that the world’s electricity reaches where it needs to go safely, efficiently, and intelligently. Think of it this way. Every building, factory, hospital, and data center needs electricity to function. But grid electricity is not automatically usable. It needs to be received, stepped down to the appropriate voltage, distributed throughout the facility, protected against surges and outages, and increasingly monitored and optimized in real time. Schneider makes the equipment and software that does all of that.
So, if you walk into a hospital, Schneider likely made the switchgear that distributes power through the building, the backup systems that keep the lights on if the grid fails, and the software that monitors energy consumption across every floor. If you use a cloud service powered by a hyperscale data center, Schneider probably built the power and cooling infrastructure to keep those servers running. If you work in a factory, Schneider’s automation systems are likely controlling parts of the production line.
For perspective, its products are found in over 95% of the world’s data centers, 40% of the world’s hospitals, and four out of ten U.S. homes. Yes, Schneider is quite dominant, one of the few giants in this fragmented market.
And it is a hugely promising business for decades to come, with very clear compounder potential. Being a deeply embedded infrastructure company with a 190-year operating history that dominates in low- and medium-voltage electrical equipment and the software and services that come with that, Schneider sits at the intersection of three of the most powerful structural trends in the global economy right now — electrification, industrial automation, and the data center build-out.
As I already alluded to, it is one way to optimally benefit from the AI infrastructure boom outside of the usual hyperscaler, semiconductor, or energy stocks – you get none of the cyclicality, none of the CapEx, none of the hype, but all the benefit at a much more attractive risk profile and in a diversified giant. Additionally, global power demand, especially from renewable sources, is expected to boom over the next two decades, and global grid investments are expected to grow significantly to meet changing needs, altogether translating into a very promising outlook for this 190-year-old, large-moat industrial.
I would say that is a very compelling setup, and it’s why I initiated a position in Schneider Electric earlier this year on weakness. This is the kind of business that lets me sleep well at night, knowing it faces practically no risk of disruption, thanks to decades of installed base, regulatory certification, and switching costs - it’s a physical, code-mandated, deeply embedded layer of the built environment – and has perfect exposure to multi-decade secular growth opportunities that will drive excellent growth. That fits my framework beautifully.
Anyway, for a full breakdown of this business, I would recommend checking out my March Deep Dive. Today, I want to revisit my investment thesis following plenty of developments over the last 5 months, including the first half results, which were genuinely impressive. So, let’s break down the numbers and details, after which I will update my financial framework and view of the stock.
Without further ado, let’s delve in!
Welcome to InvestInsights — an independent equity research publication rooted in long-term, buy-and-hold investing, publishing actionable stock/equity research reports weekly!
📈 You’re reading my latest [FREE] stock analysis. If you like this analysis, make sure to like & subscribe to receive much more like this, weekly!
Financial & Performance Review
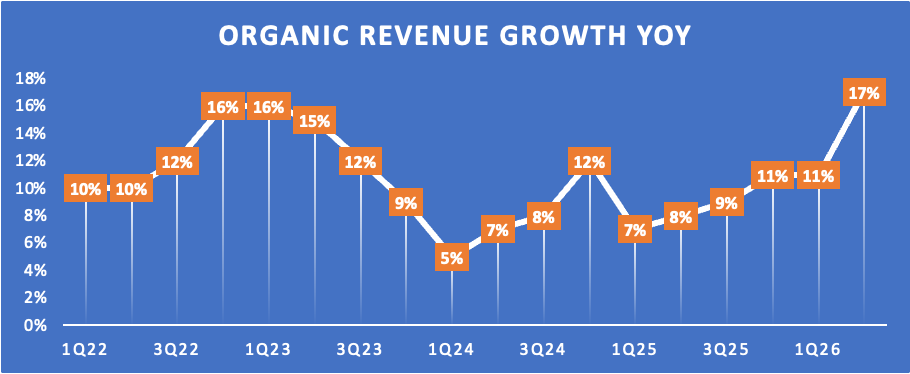
Delving straight into last week’s Q2/H2 results, Schneider reported a record Q2 revenue of €11.2 billion, up 17% organically, which is the strongest growth in over 5 years and a much stronger performance than I anticipated, with organic growth accelerating by nearly 6 percentage points sequentially.
This reflects much stronger demand than broadly anticipated, likely suggesting Wall Street (and I) still underestimate Schneider’s medium-term growth opportunity as hyperscaler CapEx explodes.
Notably, this was driven by good momentum in all regions, particularly in North America and China & East Asia, delivering 23% and 20% YoY growth, respectively. India, Schneider’s third largest market, also saw growth of roughly 20%, while Europe was up 8% and South Asia & International was up 12% YoY, so a really strong performance across the board, with Schneider’s largest markets as the standout.
This brought first-half revenue to a total of €21.2 billion, up 14% organically and a record high, despite a €750 million FX headwind, driven by the weaker dollar and Indian Rupee against the Euro.
Breaking down revenue further, Schneider also saw both its operating segments contribute to the strong Q2 performance. First, there is the Energy Management segment, which covers everything related to the distribution, monitoring, and optimization of electrical power, from medium- and low-voltage switchgear and UPS systems to building management software and grid automation. This is Schneider’s bread-and-butter.
Energy Management revenue was up a remarkable 18% organically in Q2 to €9.6 billion (86% of group revenue). The primary driver of this is exceptional momentum in North America, with Energy Management sales up 25% YoY, mainly thanks to the U.S., where huge data center investments are driving record growth in cooling, prefabricated modular solutions, and 3-phase UPS. And with North America accounting for 44% of revenue, this strong performance here is a strong growth driver for Schneider.
On top of this, demand in China & East Asia was also strong, with organic sales up 20% YoY, driven by double-digit growth in China, led by semiconductor applications (mostly new manufacturing facilities) and renewable power. Meanwhile, East Asia was up more than 20%, driven by data center investments.
In Europe, growth was more moderate at 8% organically, driven by grid investments and infrastructure projects. Data center also contributed but to a lesser extent than North America and East Asia. Also, Europe had a tough comparison against a number of large projects last year, dragging down its growth rate.
Overall, the performance in Energy Management was exceptionally strong, in large part thanks to explosive data center-related demand.
Moving on to Industrial Automation, this segment accounts for just 14% of revenue and covers the hardware and software used to automate and control industrial processes, PLCs, drives, sensors, SCADA systems, and the AVEVA industrial software platform.
This segment delivered Q2 revenue of €1.9 billion, up 11% organically. The strongest growth driver here was China & East Asia, with very strong organic growth of 20% YoY, with double-digit growth in discrete markets and encouraging signs in process markets.
For reference, discrete automation covers manufacturing where distinct, countable units are produced. Think individual products coming off an assembly line, including sectors like semiconductor manufacturing, packaging, material handling, electronics, and industrial OEMs. This vertical experienced weakness in recent years due to cyclical headwinds but is now recovering – it remains a longer-cycle business, so the ramp is gradual. In East Asia specifically, investments in semiconductor fabs are a great tailwind for Schneider.
Meanwhile, Process automation covers continuous or batch-based production, where materials flow rather than discrete units are counted, including sectors like energy and chemicals, metals, and mining and minerals.
Apart from China & East Asia, North America was up 8% YoY, with mid-single-digit growth in the U.S., led by discrete and a recovery in process. Europe was also up 8% YoY, with strong discrete growth. The recovery in process was still a bit slow. Finally, South Asia & International was up 9% YoY, driven by India and Australia.
Across both segments, the strongest driver of growth was clearly the data center end market, which now delivers over 30% of group revenue. For perspective, Schneider sells essentially everything a data center needs on the power and cooling side, medium-voltage switchgear to step down incoming utility power, UPS systems and PDUs to condition and distribute it reliably to servers, busway systems to connect it all, and increasingly liquid cooling solutions through its recently acquired Motivair business to manage the extraordinary heat generated by AI accelerator chips. Schneider also provides the software layer to monitor and optimize data center energy efficiency and uptime.
Schneider is the leader in this end market, already present in 95% of the world’s data centers. In Q2, this end market delivered huge triple-digit growth amid exceptional demand. Simply, as more cash flows to compute architecture and new data centers, Schneider massively benefits.
Besides data center, the Industry end market was fairly strong thanks to strength in semiconductors, and Infrastructure was a solid contributor thanks to continued grid investment in Europe.
The only mild drag in Q2 came from the Buildings end market, which covers commercial offices, retail, healthcare facilities, hotels, educational institutions, public buildings, and residential construction. Here, growth was more subdued, though positive, due to some weakness in residential. Positively, the long-term drivers remain in place, with regulatory pressure across Europe and, increasingly, in North America forcing building owners to upgrade their electrical infrastructure, install smart energy management systems, and electrify their heating and cooling. This creates a multi-decade renovation cycle that should sustain demand regardless of new construction activity, a meaningful buffer against residential cyclicality.
Finally, let me quickly break down Q2 revenue by product type, starting with Product, which simply covers physical equipment sales. Here, sales accelerated to 13% organically, accounting for just under 50% of revenue. Pricing was a strong lever of growth here, about four points compared to Q1.
Second up is System sales. This refers to full system sales instead of individual products, such as a fully configured data center power and cooling system, or an end-to-end building management system for a commercial real estate portfolio. These are higher-value sales for Schneider because they involve engineering expertise and project management.
Systems account for about a third of group revenue and was up 28% in Q2, driven by very strong data center demand, where complete system sales are already becoming the standard.
Finally, there is software and services. Once Schneider’s hardware is installed, customers pay for ongoing software subscriptions to monitor and optimize their energy use via EcoStruxure or AVEVA, and they pay for field service engineers to maintain and upgrade the equipment. This recurring revenue stream is the most valuable part of the business because it continues regardless of whether customers buy new hardware, and it deepens the relationship each year. This brings in just 18% of revenue but is 80% recurring.
In Q2, this grew 6% YoY, which is a bit muted for the segment that tends to deliver the fastest growth. Within this, AVEVA ARR was up double digits, but total software grew only single digits organically. Positively, we should see improved growth in H2.
In close relation to this, let’s round up the top line breakdown by discussing the most important number to track within Schneider’s financials – its digital flywheel, which focuses on connected products, software, and services. Schneider defines the digital flywheel as revenues generated from products and solutions that are either connected, software-enabled, or service-based, which generated €25 billion in revenue in 2025, growing 15% organically and accounting for 62% of total company revenue, up from 53% in 2022. In Q2, this remained around 62%, up 200 bps YoY and flat from the start of the year, well on track for its 70%+ ambition.
Why is this important? The intelligence these devices generate, and the software layer that connects to them, deepens the customer relationship, raises switching costs, and pulls through higher-margin software and services revenue. So, as this trends up, Schneider’s revenue profile becomes more stable and reliable, while strengthening its moat as it gets more deeply integrated. The progress here looks good!
With that, let’s move to the P&L (these are H1 numbers given Schneider only discloses profitability semi-annually)
Schneider delivered an H1 gross margin of 42.5%, up 10 bps YoY, which was surprisingly strong, given management’s guidance for this to likely be down YoY. Net pricing continued to be a negative 120 bps YoY due to input cost inflation and tariffs, despite proactive pricing actions taken at the start of the year. On top of that, mix was also a 70 bps headwind due to strong system sales, which are higher-value projects but also lower-margin.
Positively, management delivered very strong productivity gains, realizing a €500 million cost improvement, driven by technical productivity, supplier negotiation, and leveraging capacity investments in recent years, driving a 240 bps tailwind, offsetting both net pricing and mix.
Moving down the P&L, operating costs grew 8% YoY (organic) in H1, well under top-line growth of 14% YoY, therefore delivering significant operating leverage, with costs as a percentage of revenue down 110 bps YoY.
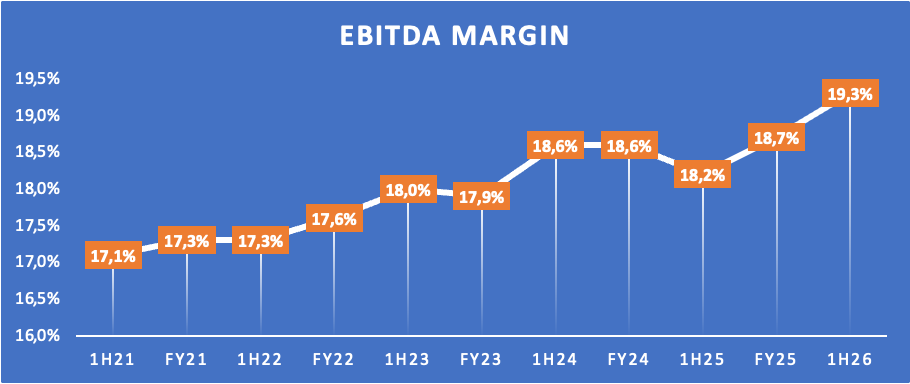
This translated to an EBITA of €4.1 billion, up 22% YoY and reflecting a margin of 19.3% in H1, up 120 bps YoY. Those are both new record highs. As shown below, Schneider has been delivering very solid margin expansion for years now, growing its EBITA margin very consistently to new highs. And as growth only continues to accelerate and management seems to have costs well under control, I am very bullish on the room for further expansion in the coming years.
And management can realize this without sacrificing innovation. R&D costs were stable at 6% of sales in H1, with Schneider deploying €1.2 billion into R&D, which is also a new high.
Ultimately, this translated to an adjusted net income (which removes some one-time charges from last year) of €2.7 billion, up 21% YoY or 29% in constant currency.
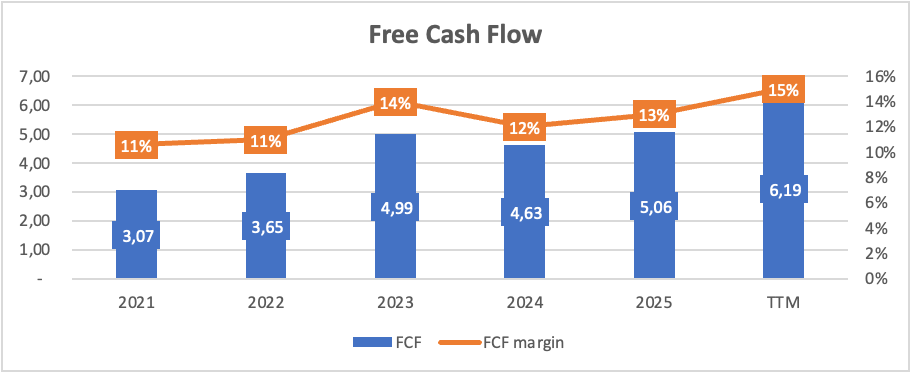
Additionally, H1 FCF totaled €1.6 billion, up 244% YoY and a record high, driven by 28% growth in operating cash flow. It is worth noting that Schneider realizes the majority of FCF in the second half of the year due to the usual buildup of working capital in H1. Nonetheless, the strong H1 performance brings TTM FCF to a total of $6.2 billion, reflecting a very solid 15% FCF margin, which is among the highest in Schneider’s history.
15% might not seem impressive, but for a large industrial like Schneider, which generates the far majority of revenue from physical product sales, that is really quite impressive, especially its ability to deliver healthy FCF in any given year.
Driven by these strong cash flows, Schneider maintained a very healthy balance sheet. Its net debt/adj. EBITA ratio ticked up slightly from the start of the year to 1.64x due to a €2.4 billion dividend payment and €600 million in buybacks outpacing a €1.6 billion FCF. Nonetheless, sitting on €4.5 billion in cash and a manageable €20.8 billion in debt, Schneider still deserves an A-grade credit rating from S&P, in part driven by its healthy and consistent cash flows – financial health absolutely isn’t a concern here.
This also allows it to maintain a solid dividend, with shares now yielding 1.4% based on a 58% payout ratio. Schneider has grown its dividend for 10 straight years and has done so at a 10% CAGR over the last 5 years. Not too bad!
More content like this? Consider InvestInsights Premium
InvestInsights Premium is designed to help you find best-in-class compounders, identify deep-value opportunities, avoid costly mistakes, and stay focused on fundamentals when markets get noisy, with full transparency into how I make decisions over time.
In practice, this gets you:
6–8 Research Reports per month, 2x more than free subs do, which includes 3-4 Deep Dives!
Full visibility into my personal portfolio, including allocations, transactions, and conviction levels
An overview of target prices and ratings, updated weekly, all available in a web-based Hub.
Price tag? Only $95 per year or $9.50 a month. That comes to just $1 per analysis, with the rest provided at no cost.
Sound useful? You can upgrade to Premium today using the button below!
Outlook & Valuation
Looking at the second half of the year, management is quite bullish, expecting positive contributions from all end markets, all business models, and all regions. Of course, data center in particular should remain a big growth driver, with demand turning out much stronger than expected before, thanks to growing hyperscaler budgets. Meanwhile, management does not expect the Middle East conflict to pose a huge headwind.
As a result of this healthy demand dynamic, management significantly raised its FY26 guidance, now expecting organic revenue growth of between 10% and 13%, up from 7% to 10% before. And driven by this stronger top-line growth and great efficiency gains, management now also expects the adj. EBITA margin to expand by 70-100 bps in 2026, up from 50-80 bps prior, pointing to an EBITA margin between 19.4% and 19.7% based on today’s exchange rate. This should allow for EBITA dollar growth between 14% and 19% organically.
That is extremely promising guidance, a big step up from before, and pointing to growth significantly ahead of my prior expectations.
Meanwhile, the long-term setup for Schneider remains sublime.
Global power demand is expected to rise by 60% over the next 15 years, while renewables such as solar and wind are projected to triple their share by 2030. That’s a staggering scale of infrastructure buildout, and it doesn’t happen without the kind of low- and medium-voltage electrical equipment, automation systems, and energy management software that Schneider specializes in.
Global electricity demand is expected to grow at least 2.8% per year through 2030, driven by electric transit, economic growth, industrialization, greater cooling demand in developing countries, and the rapid growth of data centers, which has upended years of flat or near-flat demand in developed markets.
Alongside raw demand growth, the grid itself needs to be rebuilt. Global grid investment is expected to exceed $410 billion in 2025, but to meet climate and energy goals, annual investment will need to increase to around $600 billion by 2030. The European Commission alone estimates that €584 billion in grid capital expenditure is needed by 2030, rising to €1.2 trillion by 2040. Schneider’s infrastructure end-market, grid modernization, smart switchgear, and digital grid software are direct beneficiaries of this spending cycle.
Driven by these structural, multi-decade trends, growth forecasts for Schneider’s underlying markets look brilliant. Take the energy management systems market, which is forecasted to compound at a 13-16% CAGR over the next decade. Meanwhile, the industrial automation market is projected to grow at a 9-11% CAGR, and the grid automation market, directly linked to Schneider’s infrastructure segment, is projected to deliver a 7% CAGR.
And I expect rapid growth in data center compute and the dramatic increase of power intensity in each of these to add several percentage points to each of those CAGRs. Management itself is more cautious, guiding for organic revenue growth of 7-10% through 2030, but honestly, looking at current demand dynamics and the growing size of the current data center build-out, I believe this can easily exceed the high end.
I deem low-teens growth through 2030 quite realistic.
Meanwhile, on the bottom line, management continues to target 50 bps of EBITA margin expansion per year or 250 bps of cumulative expansion through 2030, which is now already trailing well ahead of target. Yes, some gross margin pressure due to rapid growth in lower-margin system sales will likely persist, but I expect operating cost leverage to offset this and allow for gradual margin expansion of 50-70 bps YoY or closer to 300-350 bps through 2030.
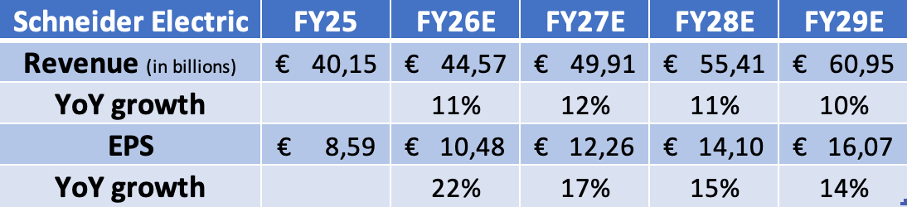
Jumping to my own updated financial framework, I have meaningfully lifted my medium-term expectations for Schneider, in large part thanks to energy demand and data center investments trending ahead of my previous assumptions. For 2026, I now expect Schneider to deliver a second half in line with the first half in terms of growth, translating to an organic growth expectation around 14%, sitting at the high end of guidance. However, I now assume a currency headwind similar to H1, which will result in reported revenue growth of only 11% YoY (up from 10% prior).
On the bottom line, management’s positive gross margin in H1 gives me confidence in stronger 2026 margins. I now expect the gross margin to be slightly negative in H2, but operating cost leverage to allow for healthy EBITA margin expansion of close to 100 bps, supporting EPS growth of nearly 30% organically or 22% reported.
Looking further ahead, I now expect organic growth to sit in the low-double digits, up from high-single digits previously, simply due to better-than-expected demand, especially from the data center end market and the semiconductor industry (with fab construction accelerating). This should allow for 2029 revenue to exceed €60 billion. The big uncertainty here is FX, especially as the U.S. should continue to grow as a percentage of total sales due to outsized data center growth.
On the bottom line, I expect Schneider to keep delivering healthy margin expansion, as explained before. This should allow for mid-teens EPS growth in 2027-2029.
These assumptions are all reflected in the updated financial model below!
That brings me to valuation, and this highlights that Schneider’s strengthening outlook is no secret, with shares up 26% YTD and 35% over the last year, leaving shares trading far from bargain multiples. At a current price of €299, shares trade at:
28.5x 2026 earnings
24x 2026 FCF
There really is no way around the fact that these are premium multiples to pay for a large French industrial. I mean, Schneider’s own 10-year median earnings multiple sits at 19.4x, leaving it trading at a 47% premium today. However, historical averages are an unfair comparison given the very different growth profile. For reference, Schneider delivered a revenue and EPS CAGR of just around 4% between 2011 and 2021, a growth profile that deserves a significantly lower multiple than what we are seeing today.
I mean, a large industrial with incredible revenue reliability and a large moat/little to no risk of disruption, now forecasted to grow revenue at a low-double-digit rate through 2030 and a mid-teens EPS rate, driven by multi-decade structural growth drivers, is quite a compelling proposition, absolutely earning a premium multiple.
And given the increasingly large portion of Schneider’s growth coming from recurring software sales and the multi-decade nature of the energy transition and grid modernization, I don’t expect Schneider’s growth to fall off a cliff beyond 2030, even if data center CapEx moderates. This company simply has more than one structural trend supporting its growth, and while growth will moderate without the huge data center tailwind it’s seeing today, I think mid-to-high single-digit growth is still a well-supported assumption beyond 2030, so I don’t mind paying a premium for this business that quite nearly ensures long-term compounding for decades to come, with near zero risk of disruption – a moat getting stronger, if anything.
Say we apply a 25x earnings 2028 exit multiple, which reflects some multiple contraction from current peak levels to reflect moderating growth — I think that is a fair multiple to pay for this high-quality compounder given revenue durability and moat. Using this multiple and my current 2028 EPS forecast, I calculate an end-of-2028 target price of €353, implying an annualized return of roughly 8%, including dividends.
That is a forecasted CAGR well short of my 15% target, reflecting a mediocre risk-reward from a current share price of €299. So, while I am really bullish on Schneider’s long-term prospects and I view it as a top-quality compounder, the current price does reflect an awful lot of optimism, leaving little downside protection.
Therefore, I don’t view current price levels as an attractive place to buy. Schneider has proven to be a very successful investment over the last decade, with annualized shareholder returns of 17%, and that is without dividends. But to repeat this, we need a better entry point.
Personally, following the H1 results and my revised financial framework, I am targeting a share price of €260 to add to my position, down roughly 13% from current levels.
Rating + fair value: Hold — Accumulate below €260
2028 Target Price: €353
Implied CAGR from current price: ~8%
Please leave a like if you enjoyed this post and found it valuable!
