

Looking to do your own stock analysis? Consider using StocksGuide, my go-to stock and business analysis tool. Check it out! Most of its features are free.
Last Wednesday, enterprise software giant ServiceNow—the leader in ITSM and ITOM software—reported its Q1 earnings, and it’s safe to say they impressed investors, with shares jumping double digits in the following trading session.
The company surpassed the Q1 consensus, issued Q2 guidance above expectations, but most importantly, showed barely any weakness, which took away mounting fears over a slowdown in growth. You see, ServiceNow shares had been going through a rough patch since late January, losing as much as 38% of their value.
However, all this pressure missed any fundamental basis. The reason for this considerable decline was almost entirely fueled by mounting investor fears. Announced tariffs and a subsequent trade war cast a cloud over the economic outlook, and the DOGE government’s cost-cutting could impact ServiceNow (the government is a massive NOW customer).
Yet, these fears were quite misplaced, which is exactly why I had been aggressively buying $NOW shares over recent weeks as shares slumped. The Q1 results, RPO numbers, and management’s confidence showed that NOW is seeing absolutely no slowdown in demand or impact from DOGE measures, as its software is simply too crucial to its customers and actually leads to cost savings, especially amid the growing deployment of AI in enterprise software layers.
In other words, NOW is still firing on all cylinders and is seeing no demand weakness at all, taking away investor fears and making the sell-off completely unjustified. In response, shares gained 15.5% in the following session. Though, while great, shares still trade well below the price levels we saw after the post-earnings sell-off in early February, and these are still down 11% YTD.
So, with NOW showing no weakness and shares still down, trading below early February levels (which is when I initiated a position in NOW), is now still a good time to buy?
Let’s delve into the Q1 results and find out!
Q1 earnings + Highlights
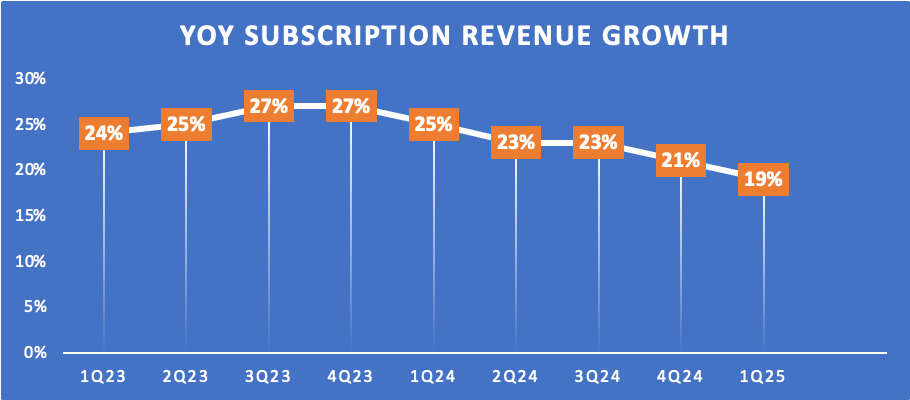
Q1 subscription revenue grew 19% YoY to $3 billion (20% in constant currency), sitting in line with consensus estimates.
Q1 renewal rate is stable at 98%.
Q1 RPO was $22 billion, up 26% YoY.
cRPO grew 22% in Q1, 150 bps ahead of guidance.
This quarter was pretty much all ServiceNow investors could wish for. The company nailed it across the board, showing no weakness and once again outperforming.
Yes, revenue growth slowed further and fell out of the 20s for the quarter, but this was still nicely above the high end of management’s guidance and in line with consensus estimates, despite a worsening macro background. This is also especially strong considering NOW faced some headwinds in Q1 from an unexpected shift in the U.S. federal budgets, which led to some timing changes in revenue recognition.
Therefore, I will happily argue that this is some really impressive growth, especially against very high expectations.
Meanwhile, possibly even more important, RPO numbers showed remarkable strength as well, with cRPO growth of 22%, 150 bps better than expected. Meanwhile, RPO sat at $22 billion, up 26% YoY, showing an acceleration from the previous quarter and absolutely no weakening in demand.
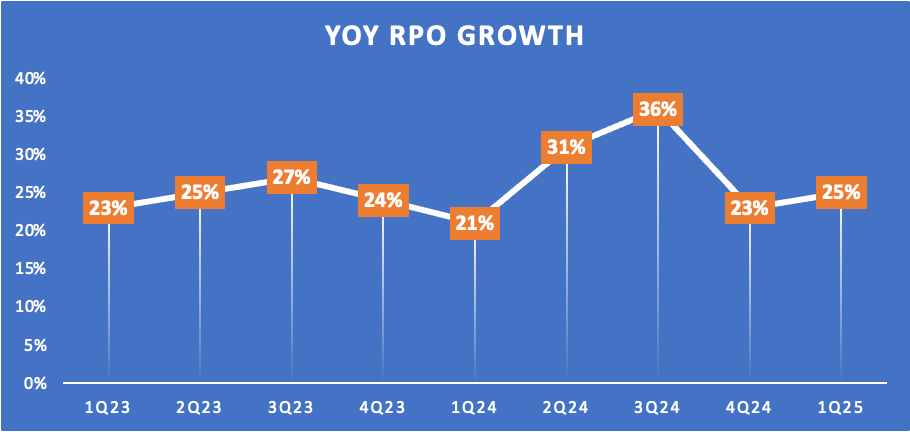
This is exactly what investors wanted to see to dispel any concerns about a weakening in demand amid a tariff-induced economic growth slowdown and DOGE U.S. government cost cuts, which led to the YTD sell-off. Positively, both the numbers and management’s commentary show none of this feared weakness, as the NOW platform once again stands out.
Simply put, when there is a lot of uncertainty around and businesses start looking for ways to cut costs, nerve spending, and optimize ROI, ServiceNow excels. The NOW platform “helps organizations drive greater efficiency from their existing tools and teams, increasing profitability,” to use management’s own words.
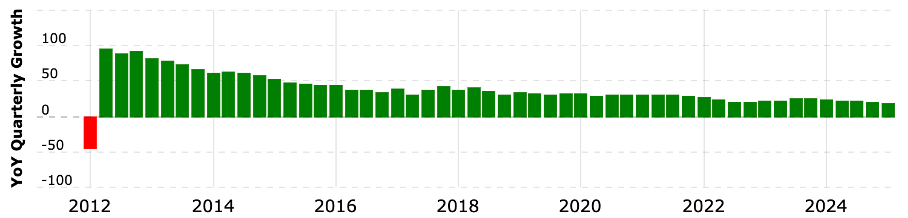
This is precisely why NOW showed no weakness in prior times of uncertainty, including during the COVID-19 pandemic and the following dip in economic growth amid record-high inflation and high interest rates. Just look at the graph below, ServiceNow shows no growth or demand weakness at all, and this time is no different.
Looking at demand in Q1, management acknowledged that uncertainty is heightened, and it is seeing a renewed focus among customers on “cost takeout by rooting out inefficiencies, modernizing outdated tech stacks, and restoring an integrated enterprise.” Yet, this isn’t reflected anywhere in NOW’s numbers, with retention stable and growth strong, showing no weakness.
The same can be said about the public sector or government contracts, with ServiceNow still reporting growth in government subscription revenue in Q1, despite some U.S. deals pushed out after the interference of DOGE. However, even amid significant cost-cutting, automation and modernization remain investment focus areas, which actually benefit NOW.
In Q1, U.S. public sector revenues grew 30% year over year, and six new contracts were signed.
Overall, as said before, demand was remarkably strong. NOW signed 72 deals greater than $1 million in ACV during the quarter, of which nine deals exceeded $5 million. This brought the total $5 million ACV club to over 500, up roughly 20% YoY, showing impressive demand.
This all just shows excellent and healthy underlying metrics.
A big driver of these large deals was ServiceNow’s push into AI. In Q1, Pro Plus deals, which include NOW Assist (AI), quadrupled YoY, including 39 deals with three or more NOW Assist products. These functionality additions are leading to rapid growth in deal sizes, with average ACV (Annual Contract Value) up by roughly 33% from Q4, showing very clear direct growth from rapid AI adoption, which remains in a very early phase.
For reference, Pro Plus products were included in 15 of the top 20 deals. ITSM Plus was included in 15 of the top 20 deals. ITOM Plus net new ACV grew roughly 70% sequentially.
This rapid adoption is no surprise considering the sheer benefits it offers NOW users. For reference, NOW is seeing a 16x improvement from lead to sale conversion with its NOW Assist, and an 86% deflection of service tickets. Furthermore, a NOW customer reported IT support decisions increased from 18% to 94% with NOW Assist and summarization features led to a 1.5-day reduction in incident resolution time.
These are incredible types of improvement. AI is a game changer for NOW, and strengthening its already massive moat further. Meanwhile, adoption and roll-out are still in a very early phase and are still gaining momentum. NOW remains perfectly positioned to benefit from AI adoption, with a massive IT presence and industry-leading integrated platform.
This will be a massive tailwind for NOW, which will take shape over the next decade. In my view, this is what will enable NOW to aintain growth of around the 20% mark for the next few years.
Meanwhile, NOW is also performing really well on the bottom line.
Q1 operating margin of 30.6%, up 20 bps YoY.
FCF margin of 48% in Q1, up 100 bps YoY.
The operating margin of 30.6% in Q1 was also roughly 100 bps above management’s guidance and shows continued margin expansion, although slowing a bit above 30%. Driving this margin expansion continues to be the implementation of AI, which leads to OpEx efficiencies. The timing of marketing spend also helped this performance in Q1.
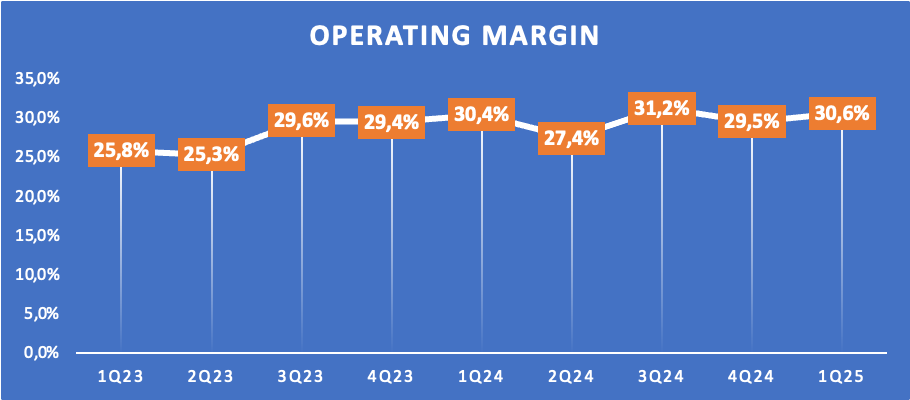
Further down the line, this strong performance resulted in an EPS of $4.04, up a solid 19% YoY and beating the consensus by $0.21. Furthermore, FCF amounted to $1.5 billion, reflecting a 48% FCF margin, also up a solid 100 bps YoY and putting NOW’s Q1 numbers solidly over the Rule of 50 benchmark.
Indeed, especially at this size, NOW is part of a very small and unique club of ultra-high-quality companies.
This strong cash flow performance allowed NOW to further strengthen its balance sheet. The company now holds a great $10.9 billion in cash and investments against just $2.4 billion in debt, leaving it in an extremely healthy financial position.
Q1 acquisitions
To strengthen the NOW platform further, especially as the age of AI and automation takes form, ServiceNow acquired Moveworks in Q1 for $2.85 billion in a cash and stock deal. Moveworks offers an agentic AI Assistant that automates support across the entire enterprise operations. It is used by over 350 large enterprises, including Palo Alto Networks, Siemens, Toyota, and Unilever.
This makes it a great addition to the NOW platform. In the words of management, “Moveworks’ user-centric product combined with ServiceNow's complementary AI-driven workflow automation will augment employee self-service, driving significant cost savings and increases to overall employee productivity. This is going to bring together requesters, where Moveworks excels, and fulfillers, ServiceNow's bread and butter, at an unprecedented scale.”
Back in September, Moveworks surpassed the $100 million annual recurring revenue mark and was valued at $2.1 billion in the latest funding round. So, the deal won’t be a massive revenue addition, but more so a strengthening of the NOW platform, which should pay off in the long haul.
I quite like this acquisition.
Furthermore, ServiceNow also acquired Logik.AI, a company with a modern AI-configured price and quote solution, which should strengthen NOW’s position in CRM sales and order management. This is also an interesting deal, which is still in a very early stage, with not too many deals yet released.
Before we move on, just a quick word…
Rijnberk InvestInsights is a reader-supported publication. I try to keep most of my content free for everyone, but I can’t do this without your support!
So please subscribe if you like our content! Want to receive even more of our investment insights and show even more appreciation? Please consider upgrading to our paid tier (only $7.50 monthly or just $70 annually).
In addition to all the free stuff, this also gets you access to even more premium analyses (a total of 3 per month), full access to my own (outperforming) portfolio, immediate trade alerts in the subscriber chat, and a full overview of all my price targets and rating, and even more!
Outlook & Valuation
Q2 revenue to be between $3.030 billion and $3.035 billion, representing 19% to 19.5% growth, stable from Q1.
Q2 cRPO growth of 19.5%
Q2 operating margin to be roughly 27%.
FY25 revenue to be between $12.64 billion and $12.68 billion, reflecting YoY growth of 18.5% and 19% (19.5% on an FX-neutral basis)
FY25 operating margin to be 30.5%.
FY25 FCF margin to be 32%.
Indeed, NOW raised its FY25 guidance after a better-than-expected Q1 performance, despite headwinds. If investors needed any more proof that concerns and fears are well overblown, here it is. Management is confident enough to slightly raise FY25 guidance as it expects a stable performance throughout the year. And, for the record, NOW management tends to be quite conservative with its guidance.
This guidance now also accounts for the weakening of the U.S. dollar in Q1, which is providing a mild tailwind for NOW. Also, this guidance factors in some risks with regard to the geopolitical environment. Meanwhile, changing tariff dynamics and changes in government spending are only expected to provide tailwinds for ServiceNow.
Ultimately, this guidance reflects management’s confidence and the strength of the NOW platform, with current projections still pointing to NOW being a Rule of 50 business in 2025, which is rather remarkable at this size.
Following this strong quarter, I have left my medium-term projections mostly unchanged, with only minor tweaks.
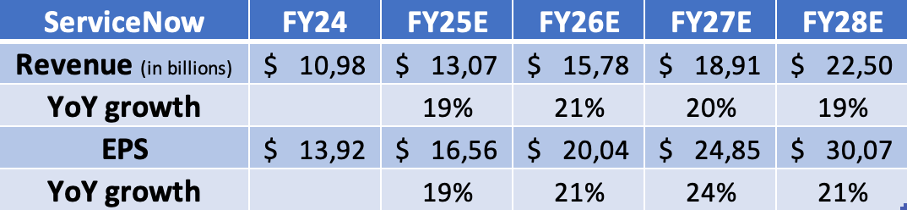
Based on these projections and after the big share price jump for NOW shares last week, they now trade at roughly 57x this year’s EPS, down from 61x in early February, still reflecting the incredible premium we have gotten used to for NOW shares over recent years, no matter what type of valuation metrics we look at.
Just like last time, I will continue to argue that NOW more than deserves this insane premium. It is a true rule-of-50 business with a pristine balance sheet and terrific outlook. Meanwhile, its growth drivers are still firing on all cylinders, and growth remains healthy and well-supported. With the upcoming push from AI, this will likely result in growth barely slowing at all through 2028, which explains why the company still trades at such high multiples. Its pure resilience only adds to this, especially amid the high uncertainty we are facing right now.
This is still one of the best businesses you will find, and it once more proved itself last quarter, showing not a single sign of weakness and maintaining rapid growth. I see no reason for concern for NOW shareholders amid the current global trade and economic headwinds.
This company is built to outperform. Management is likely guiding cautiously at this time, leaving room for upside in 2025, while I expect medium-term growth to remain around the 20% mark for several more years.
All things considered, I believe NOW’s premium remains justified. Nevertheless, to account for growing global uncertainty, I have slightly lowered my end-of-2027 price target to $1,243 per share, which still reflects decent upside from current levels of around $945. This translates into potential upside of roughly 10.5% annually (CAGR).
Ultimately, below $950 per share, I still believe NOW is a good buy, especially considering the upside to current projections, with the AI revenue trajectory highly uncertain. However, ideally, I would like a bit more downside protection, making a price below $900 much more appealing.
At this time, I am on the sidelines but I will continue to DCA if we see more price weakness.

am interested in pros/cons on the following thesis :
a significant number of mid-large size companies in the TAM have, or believe they may have, a pool of valuable proprietary data.
servicenow would be the fastest, possibly highest payback, route for them to unleash AI on the data. especially if they are potential or partial servicenow clients.
Thank you for sharing the thesis update. However, I have a question: could you explain why you decided to lower the target price if, according to what was stated, the thesis strengthened after the first quarter?