

ServiceNow did exactly what it had to do to prove the bears wrong and confirm once more that AI disruption fears are entirely unfounded when it delivered Q2 results after hours Wednesday.
For one, deal momentum was sensational, accelerating and coming in well above expectations, with larger and longer-duration deals. This confirms that ServiceNow is not seeing any disruption from AI, with customers still prioritizing ServiceNow. This really is the strongest datapoint investors should be watching. I mean, how can the disruption narrative hold up if ServiceNow sees deal momentum improve and customers sign even longer contracts?
Seat-based pricing disruption is another often named concern, which is also proving overblown. ServiceNow reported that it is still seeing its seats grow, and over 50% of deal value is already tied to usage-based metrics, completely removing this disruption narrative as well.
And not only that, but ServiceNow’s AI products are seeing incredible adoption, trending above already raised expectations.
What more proof that ServiceNow is an AI beneficiary and not getting disrupted by the technology can we ask for? ServiceNow delivered on every metric. I will repeat what I have said on multiple occasions so far in 2026: the SaaS apocalypse isn’t unfounded in itself; it is real, and plenty of software vendors will be hit, but ServiceNow isn’t one of them – ServiceNow is in one of the best positions to hugely benefit from Agentic AI.
As a result, the company delivered numbers above the high-end of the guided range across every top-line and profitability metric and accelerated revenue growth. Furthermore, margins held up relatively well, cash flows remain strong, and management raised its FY26 guidance.
At the same time, NOW didn’t deliver a spotless quarter across the board, with the results missing my expectations and slightly disappointing in some areas, so I am not surprised a positive reaction stayed out in Thursday’s trading session, with shares losing 3% of their value and closing in on recent lows again.
As a result of AI adoption, the company is experiencing some margin pressure due to hyperscaler contracts and rapid growth in token usage. Also, ServiceNow didn’t deliver a blowout quarter when it comes to headline numbers, and its guidance hike was minimal, tracking below my expectations.
Nonetheless, with shares down nearly 50% over the last 12 months and trading at a low-twenties earnings and high-teens FCF multiple, I think the quarter deserved significantly more investor appreciation, as the disconnect between what NOW’s results are showing us and what the market seems to be pricing in is huge.
That lasting disconnect between the share price and fundamentals/performance is exactly what creates a huge opportunity today for long-term-oriented investors – poor sentiment and false fears are putting this best-in-class software compounder on sale.
The market is selling the narrative. The results are telling a very different story. The two don’t rhyme.
Today, I will break down the Q2 results and developments to ultimately update my financial framework and thesis.
Let’s break it down!
Welcome to InvestInsights — an independent equity research publication rooted in long-term, buy-and-hold investing, publishing actionable stock/equity research reports weekly!
📈 You’re reading my latest [FREE] stock analysis. If you like this analysis, make sure to like & subscribe to receive much more like this, weekly!
Financial & Performance Review
Delving straight into the numbers, ServiceNow reported Q2 subscription revenue of $3.88 billion, up 23% YoY (FX-neutral), exceeding guidance by 150 bps and accelerating strongly from 19% growth in Q1, a 400 bps acceleration and the best growth since Q3 2024, which is remarkable given the size NOW is operating at.
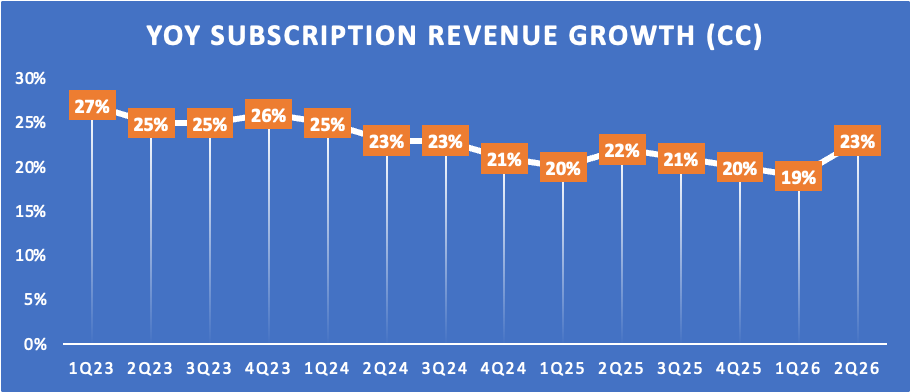
This acceleration is driven by two factors. Most importantly, it reflects sensational deal momentum, with net new ACV (which I’ll delve into later) accelerating, driven by significant growth across the product portfolio, most notably AI, security, and CRM. While revenue was decelerating gradually in recent years due to its core products maturing and size headwinds kicking in, very strong adoption of its AI features and rapid growth in its expanded security portfolio are creating a new leg of growth, significantly increasing NOW’s TAM, and this is now translating into accelerating growth, an inflection I expect is here to stay.
On top of that, NOW saw some – about half the beat – come from U.S. federal on-premise revenue that got pulled forward from Q3 into Q2 and some delayed Middle East on-prem deal closings, so this largely reflects timing. Correcting for this, growth would probably be closer to 21% YoY, still reflecting a promising acceleration in growth. For reference, management guides for 20% constant currency growth for Q3, reflecting some of this pulled-forward federal demand, but an acceleration in growth, nonetheless.
This clear uptick in growth, driven by new growth drivers, is a huge positive. As a result, total revenue was $3.98 billion, up 24% YoY and surpassing the consensus by $50 million.
However, even more important for investors to monitor closely is the underlying deal momentum, and this is where it really shone.
NOW reported RPO growth of 21% YoY (22% FX-neutral) to $29 billion, or current RPO growth of 21.5% to $13.2 billion, 200 bps above what management guided for.
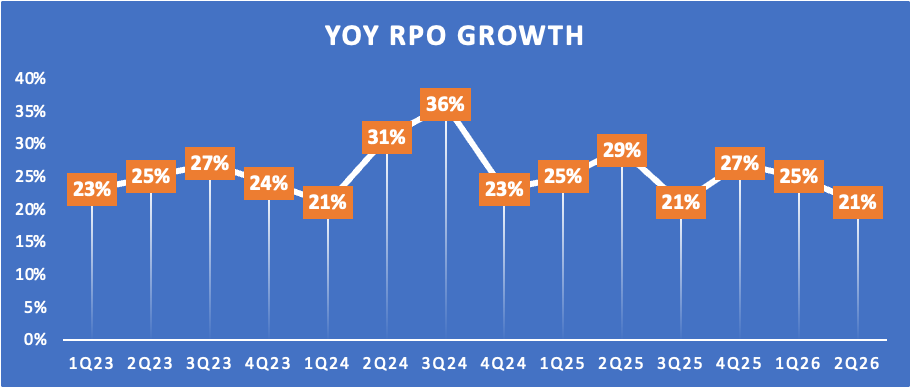
This was driven by strong demand across the product portfolio and excellent deal momentum. Most importantly, management reported that seat growth is still positive and that the average contract duration grew, confirming that NOW is not seeing a drop in demand in the slightest – to the contrary.
The company signed 123 deals greater than $1 million in net new ACV, up 40% YoY, helped by strong federal demand, which did not slow as expected. Furthermore, NOW ended the quarter with 658 customers generating over $5 million in ACV, up 23% YoY, driven by customers signing longer and larger contracts, including more and more products, integrating NOW even deeper into the IT stack. For reference, in 2025, 91% of net new ACV came from deals with at least 5 products, up from 86% the year before. And the number of customers generating $20+ million in ACV is up 3x since 2021.
Best highlighting the growth in deal sizes, the average ACV (annual contract value) of the $5+ million customer cohort was $15.2 million in Q2, a notable increase from $14.4 million one year ago. That is a 6% increase in average contract value, a good acceleration from 4% in Q1, highlighting improved deal momentum once more.
At the same time, NOW’s Q2 renewal rate remained sublime at 98%, ticking up from 97% in Q1, showing no uptick in customer churn.
Regarding the concern around seat compression, management reaffirmed that over 50% of net new business is already non-seat-based, using a hybrid pricing model, which completely erases that threat. In fact, the gradual shift to a usage-based model hugely grows NOW’s long-term opportunity. Here is an example of this from the recent Investor Day:
“If you had a team of 20 support analysts today, the team would cost over $1 million annually. About 90% of that is labor, 2% is ServiceNow. Now, what happens when you move into an agentic AI world? As enterprises look for efficiency, they’ll naturally target their largest cost center, labor. ServiceNow’s autonomous AI agents can resolve 75% of the team’s work, reducing the necessary headcount to just 5.
Let’s look at IT incident management, just one use case within ITSM. We see over 100 million incidents per month on the ServiceNow platform today. If 75% of those incidents can be processed by an autonomous workforce, this translates into a $3.5 billion ACV opportunity net of any seat licenses that go away.”
So, fewer seats but greater value under this hybrid model. Net of the reduction in seat-based revenue, ServiceNow spend is 5x higher for the same actions as before under the seat-only model, while the cost to get that work done for the customer also drops by 65%. In other words, Agentic AI running the same tasks under the new usage-based model grows NOW’s revenue potential by 5x while keeping the same customers and usage. Of course, scaling that will be gradual and slow initially, but that is an incredible long-term opportunity within the existing customer base.
Meanwhile, NOW’s AI features continue to see impressive adoption, driving growth. AI ACV exceeded expectations in Q2, now surpassing $1 billion and well on track to exceed the $1.5 billion target before the end of the year, driven by accelerating AI NNACV growth, up 40% sequentially.
Furthermore, the percentage of renewal customers purchasing Agentic AI for the first time doubled sequentially and YoY to 45%. In other words, while under 25% of renewals in Q1 added AI products for a first time, 45% of renewals added AI products for a first time in Q2, which is a really impressive rate of adoption.
That is a huge proof point that enterprises do see NOW as one of the best ways to deploy Agentic AI.
As a result, deals including 5 or more NOW AI products were up 5.5x YoY, driving a tripling in $1+ million AI deals, and the number of customers with Agentic AI in production has increased 9x over the last 9 months. And the higher AI attach rate also drives good growth in NOW’s data and analytics business, with RaptorDB Pro deal volume up 80% YoY in Q2, with the Workflow Data Fabric included in 17 of the top 20 deals. Those are huge numbers, and it isn’t from a very low base either.
I continue to be really impressed with the AI numbers NOW is able to report.
Meanwhile, NOW’s security business is performing similarly strongly. This is already a $1+ billion ACV business and, according to management, it is the fastest growing of the top 10 cyber companies in the enterprise.
The logic is straightforward: every single AI Agent deployed is another identity growing the attack surface, significantly growing the cybersecurity TAM, and as customers are deploying their Agents through ServiceNow, the step to also use its cybersecurity module is extremely small, driving rapid growth. Its security and risk solutions were included in 16 of the top 20 deals in Q2, with 24 deals over $1 million in security ACV. When deploying agents through ServiceNow, it simply makes sense to let security run through it as well.
This is a really good long-term growth lever for NOW, especially as customers are eager to consolidate. It directly grows the potential revenue per customer.
Finally, CRM also really deserves highlighting. This is now a $2 billion ACV business for NOW, with CRM NNACV accelerating further in Q2, both sequentially and YoY, with the average CRM deal size doubling YoY. CRM was included in 16 of the top 20 deals and closed 15 deals worth over $1 million.
This means NOW is outgrowing the competition quite meaningfully and rapidly gaining market share, as customers are consolidating their software and NOW has proven itself as a great ROI driver within the enterprise IT stack.
Honestly, I believe this deal momentum and the stable, best-in-class retention totally debunks any concerns over AI disruption, actually proving ServiceNow is hugely benefiting. These numbers only strengthen my conviction in NOW’s long-term runway.
As a reminder, ServiceNow is specifically positioning itself as the orchestration layer of Agentic AI, and there is no denying it is working, with the company delivering by far the best results of any enterprise software giant out there. And I am not talking about headline numbers; it is the underlying deal momentum across the portfolio and rapid AI adoption that impress the most.
By 2029, AI agents are expected to resolve 80% of common customer service issues without human involvement, according to Gartner. 93% of IT leaders plan to introduce autonomous agents within the next two years, and 89% of CIOs consider Agentic AI a strategic priority.
Without a doubt, Agentic AI is the future.
However, there is an ROI bottleneck. Every software vendor has built their own AI. Microsoft has Copilot, Salesforce has Agentforce, SAP has Joule, and Google has Gemini. And that’s before you account for the dozens of point-solution AI tools that individual departments are buying independently, such as AI for legal contract review, AI for financial forecasting, AI for HR screening, and AI for customer support.
Within three to five years, a typical Fortune 500 company will have dozens of AI agents running across its organization, built by different vendors, trained on different models, with different governance policies and different data access rights. And that creates an acute coordination problem, as each one is smart in its own domain but blind the moment work crosses into another system.
In other words, AI still needs a neutral orchestration layer to coordinate among them, prevent conflicts, and ensure they operate within the rules.
That is where ServiceNow comes in. NOW is positioning itself not as a model provider, not as a point solution, but as the platform that tells all the AI agents what to do and connects intelligence to execution across every business workflow, not that different from what it has always done.
And already sitting inside 85% of the S&P 500 and 90% of the Fortune 500 IT stacks as an orchestration platform in the most critical and cross-functional processes in the enterprise, it is perfectly positioned to be exactly that. The level of existing integration, trust, and interoperability gives it a massive edge.
Basically, the idea is that enterprises used to need ServiceNow to coordinate humans across systems. Now they need ServiceNow to coordinate AI agents across systems. The problem grew bigger, the platform became more valuable, and the revenue opportunity grew multiple times over as AI agents operate 24/7, work much faster, and execute many more tasks, as highlighted in the example before.
And the more autonomous AI becomes, the more critical the control layer becomes. This is a self-reinforcing dynamic: AI capability growth increases the value of ServiceNow’s governance layer, rather than threatening it. ServiceNow is once again the ROI driver, which is exactly why it is seeing longer and larger deals, not the opposite.
ServiceNow does not need to win the AI model race. It just needs to remain the infrastructure layer that every winner runs through, a position it already controls with decades of workflow data, 90% Fortune 500 penetration, and the only neutral orchestration platform operating at enterprise scale.
The Q2 revenue acceleration, the deal momentum (larger and longer), the unabated retention rate, and the rapid AI adoption confirm this thesis and strengthen my conviction. This isn’t business being disrupted by AI, but one benefiting from it – the numbers don’t lie.
On that note, let’s move to the bottom-line results!
NOW reported a Q2 gross margin of 80.5%, down from 83% one year ago but a slight improvement from 79.5% in Q1. The lower gross margin YoY does not come as a surprise, as this is driven by rapid AI adoption and, subsequently, higher hyperscaler and token costs. Positively, this drag is only expected to be short-term. As usage ramps, the cost per action comes down, which should improve the margins again quite quickly. So, it’s really just this ramping phase where it should be a margin drag.
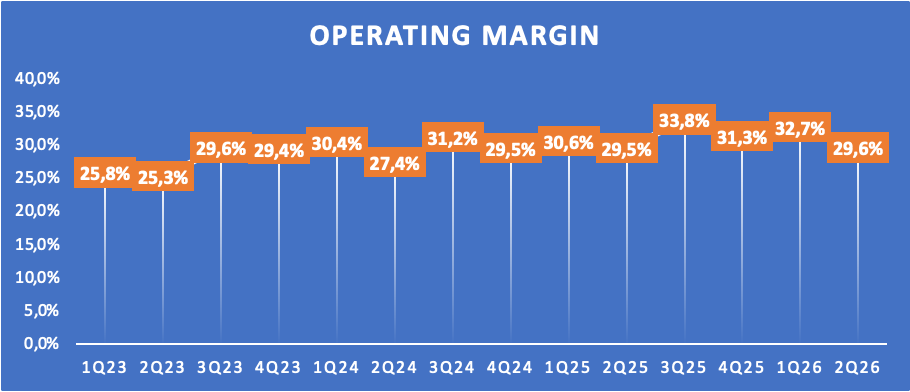
Moving down the P&L, NOW reported a non-GAAP operating margin of 29.6%, 300 bps above guidance, but still a step down from recent quarters and roughly flat YoY, also reflecting the higher AI-related costs, offset by quite impressive operating leverage. Operating expenses were up just 17% YoY, growing well below reported revenue growth of 25%, driving good operating leverage and offsetting the lower gross margin.
The guidance beat was mainly the result of the revenue outperformance and timing of spend, primarily in marketing.
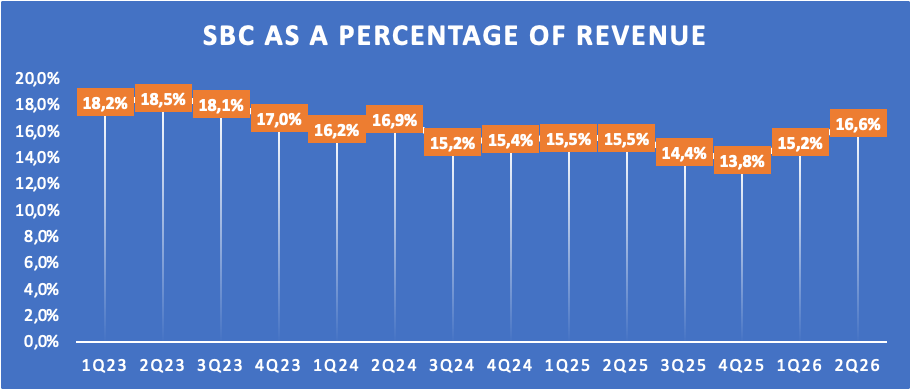
Regarding GAAP performance, Q2 operating margin was roughly 4%, still dragged down by elevated SBC spend. Q2 SBC as a percentage of revenue rose to 16.6%, up 140 bps sequentially and 110 bps YoY, which is disappointing at first glance. However, it is worth noting that SBC in Q1 and Q2 was elevated due to recent acquisitions, which drove a significant increase in personnel and temporarily increased SBC spend. So, these numbers look a bit worse than they really are.
Over recent years, NOW has made good progress in bringing down SBC from over 18% in 2023 to under 14% by the end of 2025. And for 2029, it targets reducing this to below 10%, another significant improvement driven by revenue scaling and disciplined equity practices, while also slowing headcount growth.
While I am still no fan of the excessive SBC (and it is excessive right now), I do appreciate management addressing the issue. Sub-10% by 2029 is a solid target, so I expect SBC to trend down strongly again in 2027. It is worth monitoring closely.
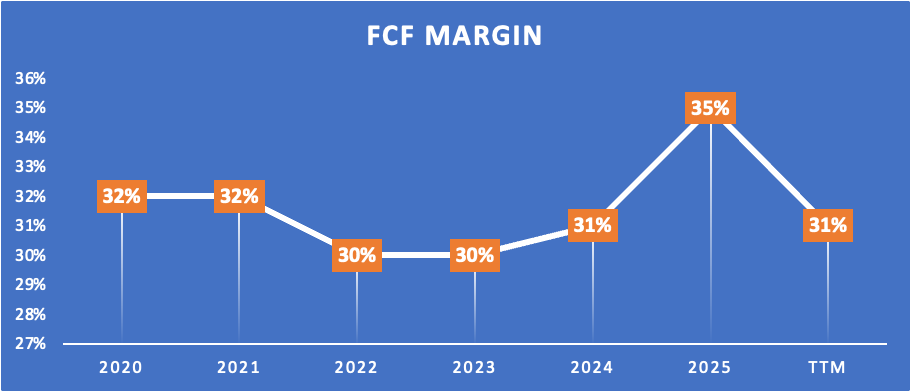
Ultimately, NOW reported a GAAP EPS of $0.29 and non-GAAP EPS of $0.90, beating the consensus by $0.04. Q2 FCF totaled $634 million, reflecting a 16% FCF margin, but FCF tends to fluctuate highly from quarter to quarter due to timing. Therefore, it is better to follow the TTM margin, and this looks solid at 31%, down a bit from 35% in 2025, but guided to improve in H2.
Ultimately, NOW continues to be a FCF machine, consistently delivering FCF margins in excess of 30%.
And these excellent cash flows allow it to maintain a healthy balance sheet, although this has worsened quite a bit since recent quarters due to a number of acquisitions, mostly the Armis acquisition closing, all paid fully in cash. Therefore, NOW issued $5.5 billion in debt in Q2, lifting its long-term debt load from $1.5 billion at the end of Q1 to $5.4 billion at the end of Q2. And sitting on $4.7 billion in cash, this translates into a net debt position. Obviously, that isn’t ideal, but given NOW’s excellent cash flows, now generating over $5 billion in FCF a year, I am not worried in the slightest.
With that, let’s delve into the outlook!
More content like this? Consider InvestInsights Premium
InvestInsights Premium is designed to help you find best-in-class compounders, identify deep-value opportunities, avoid costly mistakes, and stay focused on fundamentals when markets get noisy, with full transparency into how I make decisions over time.
In practice, this gets you:
6–8 Research Reports per month, 2x more than free subs do, which includes 3-4 Deep Dives!
Full visibility into my personal portfolio, including allocations, transactions, and conviction levels
An overview of target prices and ratings, updated weekly, all available in a web-based Hub.
Price tag? Only $95 per year or $9.50 a month. That comes to just $1 per analysis, with the rest provided at no cost.
Sound useful? You can upgrade to Premium today using the button below!
Outlook & Valuation
Following the better-than-expected Q2 results and the sizeable guidance beat, management raised its FY26 guidance, although only marginally. It now guides for 2026 subscription revenue of $15.755 billion to $15.770 billion, up $15 million at the midpoint from the prior guidance and reflecting 21% YoY growth (constant currency). Additionally, it guided for a 2026 gross margin of 81%, indicating a gross margin improvement in H2; an operating margin of 31.5%, still up 50 bps YoY; and a FCF margin of 35%, roughly flat YoY and signaling a strong H2 FCF.
Overall, to be honest, this guidance hike was a bit disappointing. Of course, part of this Q2 outperformance was the result of some pulled-forward demand, but the underlying trends do point to a better full-year result, so I had counted on a bigger raise. Positively, management confirmed during the earnings call Q&A that it continues to guide conservatively in this unpredictable market environment, stating there is clear upside to this updated guidance. So, that does leave some room for optimism.
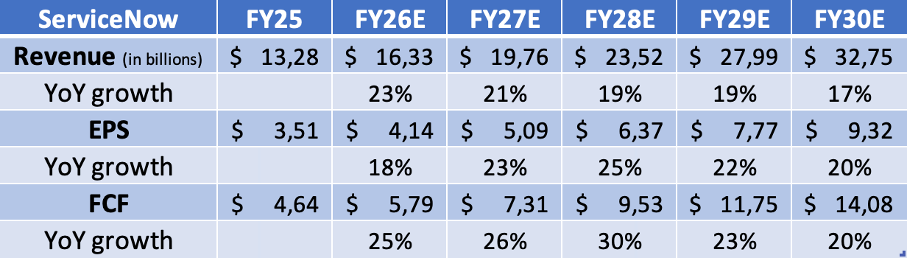
Moving to my own financial forecast, based on current deal momentum and growth, I have marginally raised my revenue forecast, now expecting revenue growth of 23% YoY in 2026, based on subscription revenue growth closer to 22%, above management’s 21% midpoint. On the bottom line, we will likely see some mild operating margin expansion but subdued EPS growth as a result of recent acquisitions, whose impact I now estimate to be a bit higher than expected previously, therefore slightly lowering my EPS expectation. Finally, I have maintained my FCF margin of 35.5%, translating to a 2026 FCF of nearly $6 billion.
Looking further ahead, I remain very bullish, even more so looking at the uptick in underlying momentum in Q2, which is really promising. As a reminder, management issued 2030 guidance during its investor day earlier in the year, guiding for 2030 revenue of $32 billion, driven primarily by its cybersecurity, data, and AI workflows, and assuming a deceleration in mature workflows. Additionally, it targets 100 bps of operating margin expansion and 100 bps of FCF margin expansion in 2027, and a Rule of 60+ status by 2030 or 50+ net of dilution.
Looking at AI adoption and its operational numbers, I think that guidance doesn’t assume any heroics. Q2 only strengthened my confidence that NOW can exceed these targets by 2030, with a good chance to well outperform them if AI momentum persists, and management indicated it is trending ahead of its 2030 AI revenue target.
As for my own forecast, I expect growth to moderate over the years due to core products maturing and size headwinds, offset by strong growth in AI and security. By my current assumptions, growth should slow into the high-teens in 2028 and moderate closer to the mid-teens by 2030, which should allow for a 2030 revenue nearing $33 billion, comfortably ahead of management’s target. Under more optimistic assumptions, I think NOW could maintain a 20%+ growth rate through 2030, but given the uncertainty of adoption and ROI, I think it’s good to be slightly more conservative.
On the bottom line, I expect NOW to keep delivering good operating leverage and margin expansion. I now assume gross margin pressure will ease but still exist in 2027, limiting the rate of margin gains, but this should improve from 2028 onward, which should allow EPS to maintain a 20%+ growth rate through 2030, driven by a lower share count and operating margin expansion. Finally, I expect the FCF margins to gradually expand, hitting 42-43% in 2030, also ramping more aggressively from 2028 onward.
These assumptions are reflected in my updated and extended financial model below!
That brings me to valuation, and this is where NOW has rarely looked better, with the market still pricing in a load of disruption risk, despite NOW proving the contrary, creating a huge disconnect. With NOW shares down 37% YTD and 51% over the past 12 months to $97 per share, shares now trade at:
23.5x non-GAAP 2026 earnings (or 63x depressed 2026 GAAP earnings and 40x 2027 earnings)
16.5x 2026 FCF.
In my view, these multiples still reflect peak skepticism and completely misprice this business. I mean, NOW is a SaaS giant growing its top line at 20%+ with a 98% renewal rate, a mid-thirties FCF margin, and a very strong outlook with a credible path to doubling revenue over the next 5 years and nearly tripling annual FCF. Moreover, I think we have clearly established that the AI disruption narrative does not apply to ServiceNow, with retention unabated and deals actually becoming larger and longer, and nearly 50% of renewals adopting AI features – NOW is actually showing the strongest AI adoption numbers of any SaaS business out there and increasingly looks like a clear top beneficiary of Agentic AI adoption.
Against that backdrop, a business of this quality absolutely deserves to trade at a premium – not at 16-17x FCF. This highlights that NOW continues to suffer from poor sentiment and investor fear. Once that sentiment improves, I think NOW can revalue strongly.
Looking ahead to 2029, I am comfortable applying a 25x non-GAAP earnings multiple, taking into account elevated but moderating SBC, and a 20x FCF multiple, which I deem absolutely fair, likely still very conservative if NOW is able to deliver results in line with my current forecast, let alone outperform it. Taking these multiples and my current 2029 forecast, I calculate an end-of-2029 target price of $218, implying an annualized return of 26%, comfortably clearing my 15-20% hurdle rate.
In other words, I believe the current risk-reward is sublime, with the margin of safety huge and potential upside significant. Honestly, I believe that NOW can deliver 30%+ annualized returns from here under less conservative assumptions, making it one of the most attractively priced stocks out there right now, in my opinion.
At any price below $115, I deem NOW shares buy-worthy – I am a buyer at these levels and happy to keep this a top 3 position in my portfolio.
Rating + fair value: Buy — Accumulate below $115
2028 Target Price: $218
Implied CAGR from current price: ~26%
Please leave a like if you enjoyed this post and found it valuable!

Thanks for the analysis. Totally agree. Couple weeks ago I did a reverse DCF analysis to see what the market implied FCFF rate is, and the number came out at around 11% vs 25% historical rate. This is clearly driven by negative narrative, fear of AI implications on SaaS.
I personally believe that recent results (although its only one Quarter) show the opposite of the deceleration that the market is pricing in.