

I think it is easy to argue that the medical technology industry is structurally one of the most attractive markets to invest in.
For one, regulatory barriers function as a moat that doesn’t expire the way patents do. A 510(k) clearance represents 6-18 months of effort and $50,000-$400,000 in direct costs, while a full PMA (premarket approval, required for higher-risk devices) represents 3-7 years and $10-75 million. These barriers discourage new entrants and protect incumbent market positions in ways patents alone cannot, and critically, unlike patents, which expire after 20 years, regulatory clearances have no fixed expiration.
Second, there is the razor-and-blade recurring revenue model. Many medical device businesses generate revenue that is partially or substantially recurring, directly translating into predictable cash flows and higher valuation multiples. A capital equipment placement, a surgical robot, a diagnostic analyzer, and an infusion pump create an installed base that consumes proprietary disposables for years, sometimes with the equipment itself placed at break-even specifically to capture the higher-margin annuity that follows. Moreover, demand is largely non-discretionary and demographically underpinned, meaning spending continues regardless of economic cycles, and an aging global population remains a powerful, long-term tailwind, ensuring sustained demand for medical devices.
Additionally, MedTech is an industry that continues to expand the TAM through new techniques. This gives well-capitalized incumbents a repeatable playbook for sustaining above-GDP growth rates indefinitely, rather than facing an eventual ceiling.
In the end, this is just an incredibly attractive market to invest in, with huge moats, excellent competitive advantages, high-quality revenue streams, and a strong outlook underpinned by structural trends.
Without a doubt, Stryker Corporation is a top pick in this industry, and as the sector has fallen out of favor, the company now trades at a solid discount to its historical valuation. Therefore, this seemed like the perfect time to take a real close look at this MedTech giant.
This is my Stryker Corporation Deep Dive! Let’s delve in.
Welcome to InvestInsights — an independent equity research publication rooted in long-term, buy-and-hold investing, publishing actionable stock/equity research reports weekly!
📈 You’re reading my latest [FREE] stock analysis. If you like this analysis, make sure to like & subscribe to receive much more like this, weekly!
This is Stryker Corporation!
Headquartered in Kalamazoo, Michigan, Stryker was founded in 1941 by Dr. Homer Stryker, an orthopedic surgeon in Kalamazoo who invented devices such as the Turning Frame bed and oscillating cast cutter because existing hospital equipment wasn’t adequate for his patients. More than 80 years later, Stryker Corporation is one of the world’s largest and most diversified medical technology companies, directly impacting more than 150 million patients annually across 75+ countries, generating just over $25 billion in revenue, earning a $125 billion market cap.
Specifically, Stryker is focused on designing, manufacturing, and selling the physical hardware, implants, and increasingly the robotics and software that hospitals and surgeons use to perform procedures – it doesn’t make drugs or diagnostics; its business is surgical and hospital equipment, competing with Zimmer Biomet, J&J, and Medtronic, although few can match Stryker’s dominant position and portfolio breadth.
Breaking down the business, it organizes its operations into two reportable segments: MedSurg and Neurotechnology (M&N), and Orthopedics.
MedSurg and Neurotechnology is the larger of the two segments, generating around $15.6 billion in revenue as of 2025, or roughly 62% of group revenue. Really, the segment is a collection of several sub-businesses under one roof, spanning surgical equipment and navigation systems, endoscopic and communications technology, patient handling and emergency medical equipment, reprocessed medical devices, neurosurgical and neurovascular products, and, following the 2025 acquisition of Inari Medical, an expanded peripheral vascular business focused on venous thromboembolism treatment.
Delving deeper into the product lines to get a sense of what Stryker actually sells, let’s start with the largest revenue contributor within MedSurg and Neurotechnology – The Medical business. This one generates $4.2 billion in 2025 and includes patient handling equipment like hospital beds and stretchers, emergency medical equipment (like its flagship portable defibrillators), and reprocessed medical devices, meaning single-use devices that are cleaned, tested, and resold at lower cost. The common threat across these products is that they all sell to the same hospital operational and facilities-management buyers (materials management, EMS departments, sterile processing) rather than to surgeons or implant-purchasing committees, as the rest of Stryker’s portfolio does.
Notably, in these product lines, Stryker is generally considered the leader, especially in hospital stretchers.
Second up is the Endoscopy business, which covers imaging and communications systems used in minimally invasive procedures, essentially the cameras, light sources, and visualization equipment that let surgeons operate through small incisions rather than open surgery. This segment generated $3.8 billion in revenue in 2025. Here, Stryker is a strong player but not the leader. Olympus dominates this space, but Stryker finds itself in the top 5, which together hold nearly half the market.
Third is the Instruments line, which generated $3.18 billion in revenue in 2025. This one makes surgical equipment and navigation systems used in operating rooms, including powered surgical tools, surgical navigation platforms that help surgeons position implants and instruments with precision, and sterilization and infection-prevention products. This is a business line that grows with procedural growth, given that it largely involves single-use equipment. Stryker is once again a top-5 supplier for most of the products it sells here.
Fourth is the Neuro Cranial line, which covers neurosurgical and neurovascular products, the tools used in brain surgery, and to treat conditions like aneurysms and stroke, which generated $2.48 billion in revenue in 2025. This is one of Stryker’s strongest competitive positions. Stryker holds a leading position, driven by its broad product portfolio, global distribution network, and legacy of trust, especially in stroke and aneurysm treatment.
To round out the MedSurg and Neurotechnology segment, there is Vascular, the newest and fastest-growing piece, built around the 2025 acquisition of Inari Medical. It focuses on treating venous thromboembolism (blood clots), giving Stryker a real foothold in peripheral vascular disease treatment, an area it didn’t previously compete in at scale. Prior to the acquisition, Inari Medical had effectively created and dominated the mechanical thrombectomy category for venous thromboembolism, with its FlowTriever and ClotTriever systems driving the shift toward large-bore mechanical thrombectomy procedures away from drug-based thrombolysis. This gives Stryker a clear first-mover and category leader position in this fast-growing niche – quite a promising business line.
Then, onto the Orthopedics segment, which generated $9.5 billion, or 38%, of 2025 revenue. This one is more straightforward, focusing on implants and surgical systems for joint and spine procedures. This includes Knees and Hips, covering joint replacement systems and the implants and instrumentation used in total knee and total hip replacement surgery. It is also tightly linked to Stryker’s Mako robotic-assisted surgery platform, which uses 3D imaging and robotic arm assistance to help surgeons place implants more precisely.
In knee implants, Stryker is the #2 player, capturing 29% of the market, only trailing Zimmer Biomet’s 34% market share. In hip implants, Stryker holds the same #2 position with a 23% market share, again trailing Zimmer Biomet (26%). Across both knees and hips, the top four players claim 80% of the market, making this a highly consolidated oligopoly rather than a fragmented market, with Stryker as the strong #2.
Stryker also has solid exposure to the Trauma and Extremities market, with 2025 revenue of $3.94 billion, covering plates, screws, and fixation devices used to treat fractures and injuries to the arms, legs, hands, and feet. Stryker here is similarly dominant, and growth is strong.
Finally, there is the spine product line, which covers implants and instrumentation for spinal fusion and other spine procedures – a much smaller business than Trauma and Joints. Stryker is also less dominant here, not a top-3 player.
Critically, orthopedics also covers Mako, which is Stryker’s robotic-assisted surgery platform. Mako originated from technology Stryker acquired when it bought MAKO Surgical Corp in 2013. The system uses a haptic (surgeon-guided) robotic arm rather than an autonomous one, meaning the surgeon actively drives the procedure while the robot enforces a pre-planned boundary the surgeon can feel through haptic feedback, physical resistance that stops the surgeon’s tool from cutting outside the planned zone.
The platform today covers partial knee arthroplasty, total knee arthroplasty, total hip arthroplasty, certain spine cases as of 2024, and shoulder replacement as of 2026. As of 2025, Stryker’s fourth-generation platform unified all these applications – Total Hip, Total Knee, Partial Knee and Spine – into a single robotic system.
Nearly 2 million procedures have been performed using the Mako platform across 45 countries, which is absolutely market-leading. Across all specialties, Stryker holds the #2 position in surgical robotics, only trailing Intuitive Surgical, although by a huge margin. However, if we focus on orthopedic, for which Mako is designed, Stryker holds the #1 position, with a huge 75% market share in the U.S. – Mako systems are heavily integrated into hospitals, capturing over 50% of global knee implant procedures and more than 20% of global hip procedures.
Why is this huge? Because Mako is the mechanism that converts a one-time capital sale into a durable, recurring implant franchise: once a hospital invests in a Mako system and trains its surgeons on it, switching to a competitor means retraining staff, re-justifying the capital spend, and abandoning outcomes data built up on the platform, which locks in years of follow-on knee, hip, and spine implant purchases specifically from Stryker. Additionally, robotics is the fastest-growing sub-segment of orthopedics, making this single platform simultaneously Stryker’s strongest moat, its clearest market leadership position, and its primary growth engine.
With that, we have covered Stryker’s product portfolio and industry exposure pretty well without going into the technical details, giving a good sense of what Stryker sells.
Next up, there are two operational factors that are crucial to understand.
First is the organizational structure. Stryker runs a hybrid model common among the best-run scaled medtech companies: decentralized operational accountability paired with centralized oversight of quality, compliance, capital allocation, and corporate development. In practice, this means the company is organized into largely autonomous business units, historically Orthopedics, MedSurg, and Neurotechnology, each operating semi-autonomously with tailored strategies for product development, sales, and marketing within its own market segment.
This structure makes sense because Stryker’s different businesses face genuinely different customers, buying committees, and competitive dynamics, a spine surgeon and a hospital procurement team buying beds have almost nothing in common, so giving each business unit the autonomy to move fast and tailor its own product development, sales, and marketing lets it compete effectively on its own terms rather than being slowed down by a one-size-fits-all corporate process. At the same time, keeping quality, compliance, capital allocation, and corporate development centralized protects the parts of the business where consistency actually matters most: a regulatory or quality failure in one division can damage trust across the entire company, and centralizing capital allocation and M&A lets Stryker deploy its balance sheet toward the best opportunities company-wide rather than each unit competing internally for funding. The real benefit is that this combination gives Stryker the speed and specialized focus of a collection of smaller, nimble competitors, while still maintaining the financial discipline, risk control, and dealmaking firepower of a $25 billion diversified giant.
Stryker did implement a small restructuring in Q1 2026, combining the orthopedic instruments portfolio with the Mako and enabling technologies portfolio into a new “Ortho Tech” business, bringing Mako, power tools, cutting accessories, and enabling technologies together under one business specifically to simplify the customer experience and increase speed to market through focused innovation.
The second operational factor worth understanding for Stryker is the importance of M&A to the business model.
Generally, high M&A activity isn’t particularly well viewed by investors. Frequent dealmaking is often read as a sign that a company can’t generate enough growth organically and has to buy it instead, and it introduces real risks: overpaying for targets, culture clashes, messy integrations, and management attention getting pulled away from the core business.
Stryker is an exception, partly due to the industry’s unique dynamics. You see, in medtech, innovation happens outside the big companies first, coming from venture-backed startups, not inside the R&D labs of Stryker, Medtronic, or J&J. Those startups take on the early clinical trial risk, FDA pathway risk, and initial commercialization risk with a small, focused team. Once a technology clears that gauntlet and shows real clinical and commercial traction, the large companies buy proven scale rather than bet years of internal R&D on something that might fail in trials. This is a much lower-risk way to access innovation than building it in-house from scratch.
On top of that, distribution and hospital relationships are the scarce asset, not the product idea. A startup can build a great device, but it can’t easily build a 1,000-person hospital sales force with decades of surgeon relationships and existing purchasing contracts. The large medtech companies’ core competitive advantage isn’t necessarily better engineering; it’s the ability to get a proven product in front of every relevant hospital and surgeon almost immediately. Buying the innovation and plugging it into existing distribution is simply faster and more valuable than either party doing it alone.
Hence, loads of M&A is an industry-specific characteristic, and Stryker is no exception. For reference, Stryker has completed over 60 M&A deals since 2016, spending roughly $20 billion on M&A alone.
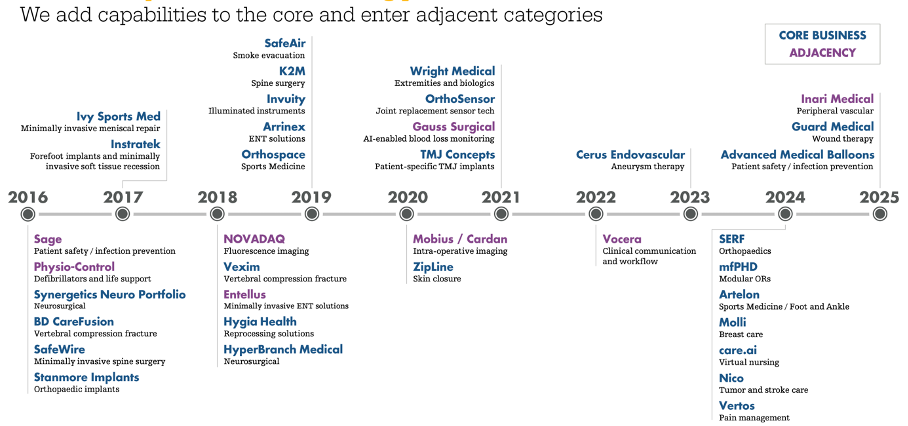
Stryker runs M&A almost like a product pipeline. It completes dozens of small, fast-integrating bets each year that extend existing ecosystems, with the discipline to occasionally write a much bigger check (Inari) when a category shift is big enough to justify buying leadership outright rather than building it. But big-ticket purchases are an exception – most deals don’t cross $1 billion.
Simply put, Stryker looks for tuck-ins that expand its leadership and capabilities within existing platforms, while also using them to enter new affiliated categories, with a focus on higher-growth areas like robotics, endoscopy, neurovascular, and ASC ecosystems, under a disciplined IRR hurdle and synergy capture, typically within 24-36 months.
This way, Stryker fills gaps faster than internal R&D could – rather than spending years developing, say, a vascular thrombectomy platform from scratch, buying Inari got Stryker into that category with an established product and clinical evidence immediately.
So, it isn’t making acquisitions to hide a weak core and add inorganic growth – most often these deals barely add to revenue. The goal is to strengthen the category position, bring in new and promising technologies or IP to build on, and grow exposure to higher-growth opportunities. Take Mako, which it acquired in 2013. It didn’t buy it for the revenue, which was minimal, but it bought the robotic-arm technology and used it to transform the economics of its existing, much larger implant business, now strengthening its lead.
This way, Stryker has grown from 14 business units in 2015 to 22 today, and massively diversified its business, with hips and knees now just 18% of revenue, down from 27% in 2015. This is largely the result of a very effective M&A engine, targeting ecosystem expansion into high-growth areas.
It is an incredibly important and effective piece of the Stryker growth engine. And it consistently compounds its moat while eliminating early-stage competition and strengthening its competitive position.
With that established, let’s answer one of the most important fundamental questions: How does Stryker generate revenue?
Basically, Stryker sells physical medical equipment and implants to hospitals, and it makes money in three main ways.
One, it sells implants and disposables. This is the largest and most stable chunk of revenue. Every time a surgeon replaces a knee or hip, fixes a fracture, or performs a spine procedure, Stryker sells the actual implant that goes into the patient’s body. These are used once per patient and need to be replaced for each new procedure, so this is a recurring, high-volume revenue stream tied directly to the number of surgeries performed globally each year.
Second, Stryker sells capital equipment. Hospitals also buy big-ticket hardware from Stryker upfront, like the Mako robotic surgery systems, endoscopy imaging towers, hospital beds and stretchers, and surgical navigation systems. These are less frequent, higher-dollar purchases. A hospital doesn’t buy a new Mako system every year, but once they buy in, it often becomes the anchor product that other sales get built around.
Finally, there are recurring services and consumables. In addition to equipment sales, Stryker earns ongoing revenue from maintenance and service contracts; reprocessing (cleaning and reselling single-use devices at a lower cost); instruments and disposables consumed and repurchased with every procedure; powered tool attachments; blades; and other items that wear out or are single-use.
The simplest way to picture it: a hospital first pays Stryker a large sum for the capital equipment (say, a Mako robot or an endoscopy system), then keeps paying Stryker smaller, recurring amounts for every single procedure performed on that equipment (the implant itself, the disposable instruments, the servicing). That combination, big upfront equipment sales plus a steady drip of per-procedure and per-patient revenue, is what makes Stryker’s revenue both substantial and fairly predictable, since the underlying demand (aging populations needing joint replacements, ongoing surgical volume) doesn’t fluctuate much year to year.
By recent estimates, Stryker likely generates roughly 20% of total revenue from capital equipment – large one-ticket purchases – with the remainder coming from implants, disposables, instruments, and services that recur with procedure volume, which is kind of recurring in nature and tied to repeat per-procedure or per-patient purchases.
That makes for a very high-quality, relatively reliable revenue stream across economic cycles.
Take 2008/2009. Yes, it saw a drop in capital equipment sales as hospital budgets tightened, but the service and consumables business held up really well. The underlying medical need genuinely doesn’t disappear in a recession. A failing hip, a fracture, a stroke, these don’t become optional because GDP contracts. That’s the real structural advantage healthcare has over, say, consumer discretionary spending.
At the same time, we do have to acknowledge that hip, knee, and spine procedures are more deferrable than some of the other procedures across medtech, so other areas will hold up better. Yet, deferred isn’t canceled: no order is being canceled, just being delayed a little bit until elective surgeries resume, and they will — a patient with a failing hip or knee doesn’t stop needing the replacement; they just wait. This is what we saw during COVID: procedures dipped at the pandemic peak as hospitals had no capacity, but they quickly bounced back as COVID pressures eased.
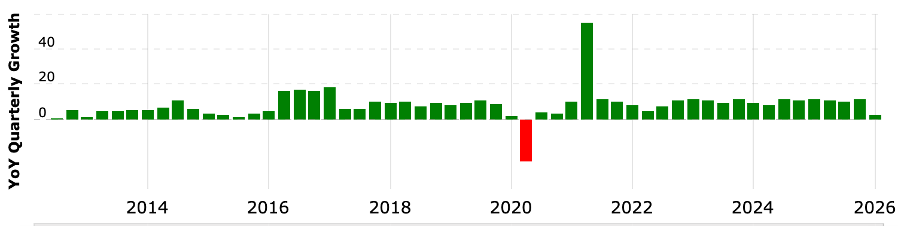
So, ultimately, while Stryker may see a slowdown amid tough economic conditions, the business is far from cyclical and will hold up relatively well, supported by a strong consumables and services business and a diversified portfolio. For reference, Stryker has reported just one quarter of negative growth since 2013, which was the first COVID quarter. That is some incredible consistency from a business with an 80-year operating history.
With that, I think we have a good idea of what Stryker is, does, and how it generates revenue. Let’s break down the moat next!
Does Stryker have a Moat?
The simple answer is yes, and quite a big one, driven by several factors.
First of all, it is worth pointing out a Stryker-specific advantage: its broad portfolio and industry exposure. Truly, Stryker’s breadth is quite impressive: 22 separate business units generate over $1 billion in annual revenue, meaning Stryker isn’t dependent on any one product category. Because Stryker spans orthopedics, MedSurg equipment, neurotechnology, and now vascular, it isn’t as exposed to a single reimbursement change, single competitor breakthrough, or single product recall the way a narrower competitor would be. That diversification, itself a product of decades of the M&A strategy above, gives Stryker more resilience and more cross-selling surface area than most pure-play competitors, and significantly less risk of disruption.
Closely related to this, Stryker’s distribution and the depth of its hospital relationships are huge advantages. A single-category competitor (Zimmer, Smith+Nephew) has one relationship thread into a hospital. Stryker has surgeons and procurement teams simultaneously engaging its reps across orthopedics, MedSurg, neuro, and now vascular. That breadth means Stryker’s sales force has more reasons to be in the building, more data on the account, and more cross-sell surface area than a narrower competitor could ever build without becoming Stryker.
On top of that, there is another size advantage, being financial firepower. A $25 billion revenue, investment-grade balance-sheet company can write a $4.9 billion cash check to Inari without blinking. A mid-size competitor either can’t do that deal at all or has to lever up meaningfully to try. That’s a size-driven moat that compounds: a bigger balance sheet enables bigger, better-timed acquisitions, which drive greater diversification and growth, which in turn supports an even bigger balance sheet, while eliminating early-stage competition.
This dynamic is why these healthcare giants practically can’t be disrupted.
Totally different but equally important factors regarding the moat are regulatory and clinical-evidence barriers. Getting a new implant, robotic system, or navigation platform through FDA clearance and building the clinical evidence base hospitals require takes years and real capital. That’s a genuine disruption-blocker: a well-funded startup can build one great product, but building the regulatory infrastructure to get a full portfolio through global approval processes repeatedly is a different order of difficulty.
And then there are the switching costs. Once a surgeon becomes trained and comfortable with a specific implant system, switching manufacturers requires retraining, revised instrumentation familiarity, and altered workflow patterns, and this procedural lock-in extends beyond the implant hardware itself into the instrument trays, cutting guides, and alignment systems tailored to a manufacturer’s proprietary designs, which integrate into a hospital’s sterilization and inventory systems.
This gets reinforced commercially through structure, not just goodwill. Stryker uses bundled account-level contracts that package implants, robotics, disposables, and service into multi-year deals, securing predictable spend and upgrade paths, plus cross-portfolio discounts that reward standardization across departments. And because roughly 85% of US hospitals participate in group purchasing organizations, a meaningful share of that relationship depth actually runs through GPO contract structures and Value Analysis Committees, hospital purchasing committees that can include a dozen or more stakeholders across procurement, clinical, and finance, rather than being purely surgeon-to-sales-rep. That matters for how durable the relationship is: it’s not one loyal surgeon, it’s an institutionalized, multi-stakeholder contract relationship that’s harder to dislodge but also harder to win in the first place.
This combination of procedural lock-in creating switching costs, regulatory scale creating entry barriers, GPO contracts institutionalizing it at the purchasing level, and the balance sheet lets Stryker acquire emerging threats before they mature, translating into very low disruption risk.
Really, you won’t find businesses much more secure than this.
But there are risks to acknowledge. The clearest vulnerability is the shift in the site of care toward ambulatory surgery centers, which favor lower-cost, more portable equipment. A genuinely disruptive, much-cheaper robotics or navigation entrant, purpose-built for the ASC setting, could erode share faster than the traditional hospital-based moat would suggest, precisely because ASC purchasing committees are smaller, faster-moving, and less encumbered by legacy GPO contracts than those of large hospital systems.
Digital-native or AI-native entrants building software-first surgical planning tools, rather than hardware-first platforms, are a second, less mature but worth-watching threat, since Stryker’s moat is built around physical instrumentation lock-in, and that logic is weaker if the differentiating layer shifts toward software and data rather than hardware.
And finally, Stryker itself notes that reputation and clinical data matter enormously, and that recalls or litigation related to implant failure can shift loyalty quickly in a market where reputation carries real weight.
These aren’t factors that break the moat – it remains incredibly strong – but it isn’t unconditional. Nonetheless, Stryker’s moat remains durable and strong today.
Growth drivers
So, what kind of growth can we expect from this MedTech giant? Safe to say, the backdrop looks good, with the healthcare/MedTech sector structurally quite attractive, thanks to the secular drivers underpinning it.
For one, there is the aging population. People older than 65 represented around 13% of the total US population, expected to reach 20% by 2030, and the global geriatric population is anticipated to reach 1.5 billion by 2050. Since osteoarthritis, spinal disorders, and cardiovascular/neurovascular conditions all scale directly with age, this alone underpins mid-single-digit organic growth across nearly every Stryker category without requiring any gains in competitive share.
Second, there is a growing burden of chronic disease, with cardiovascular disease, diabetes, and musculoskeletal conditions all becoming more prevalent as populations both age and see rising obesity rates. Eight of ten surgical patients are projected to have a BMI above normal by 2030, and diabetes prevalence is projected to rise to 15.6% over the next decade, both of which historically drive more joint replacement and vascular procedure volume (obesity accelerates osteoarthritis and cardiovascular/venous disease).
Additionally, healthcare is becoming more accessible in emerging markets, a genuine long-run driver. As of 2023, only 45 countries (36.6% of those reporting) had achieved the Lancet Commission’s target of a minimum annual surgical volume of 5,000 surgeries per 100,000 population, a global health benchmark for adequate surgical access. That means a majority of the world’s population still lacks access to even a baseline level of surgical care, which represents a much longer-duration growth opportunity than anything in the mature US/European markets, as healthcare infrastructure and insurance coverage expand across Asia, Latin America, and parts of Africa over the coming decades.
Driven by these overarching secular drivers alone, the number of surgical procedures globally should continue to grow at roughly 3% annually through 2030, and likely well beyond. In dollar terms, thanks to pricing and mix effects, the total market is forecasted to grow at 5-6% annually, creating a compelling growth baseline.
On top of that, there is also a broader, multi-decade shift toward minimally invasive techniques across nearly every category Stryker touches – endoscopy, spine, vascular, and neurovascular - which tend to command premium pricing and drive faster category growth than open-surgery equivalents, putting Stryker in a very promising position.
Looking at Stryker’s actual markets, orthopedics is projected to grow in the mid-single digits, roughly 4-7%, through 2030. However, Robotic-assisted and navigation systems, where Stryker is strong, are projected to post a 9.84% CAGR through 2030, roughly double the broader market rate. The outlook for the endoscopy market is similarly strong, with growth forecast at a 7% CAGR through 2034.
The neurovascular market is forecasted to deliver a 5-7% CAGR through 2035, which is also a reasonably attractive growth rate. Next up, the global venous thromboembolism treatment market is forecast to grow at a 5% CAGR, although the mechanical thrombectomy sub-segment (Inari’s actual product category) is generally cited as growing meaningfully faster than the category average, since it’s displacing older thrombolytic drug approaches.
Then onto medical, which includes beds, stretchers, and patient handling; this has historically been Stryker’s slower-growing piece, with most verticals in this portfolio projected to grow in low- to mid-single digits, reflecting a more mature, replacement-driven category rather than one benefiting from procedure volume growth or new indications. Furthermore, the powered surgical instruments market is forecasted to grow at a 4-7% CAGR through 2030-2035.
These growth rates from market research firms are mostly in line with Stryker’s own forecasts from its 2025 investor day:
Endoscopy, Medical, and Neuro to grow by mid-single digits
Vascular and Instruments to grow by high-single digits.
Joint replacement and Trauma and extremities to grow by mid-single digits.
So, across the full portfolio, the “base” hardware and implant categories mostly sit in the mid-single digits, say 4-7%, while the technology-forward layers stacked on top, navigation, robotics, digital/software, are the genuine high-growth pockets, generally running at roughly double the rate of the underlying implant or instrument market they’re attached to.
Yet critically, Stryker has proven over recent decades that it consistently outpaces the underlying market by several percentage points on average, driven by market share gains, positioning in higher-growth verticals, and efficient M&A. And I don’t see this changing over the next decade.
A critical reason for this is Stryker’s dominant position in robotics, which will drive share gains. Mako’s installed base and procedure count give Stryker disproportionate exposure to the fastest-growing sub-segment of orthopedics. Especially platform expansion into new anatomies and formats is a huge opportunity here. Mako has moved from knee and hip (its original base) into spine (2024) and shoulder (2024-2025), and Stryker plans to bring a shoulder feature to the Mako 4 system in the first half of 2026. Each new anatomy effectively creates a new addressable robotics market, from which Stryker starts as a first mover. This leading position and exposure to robotics mean Stryker should grow faster than the orthopedic market itself, not just in line with it.
On top of that, Stryker’s M&A engine is firing on all cylinders. This is the single biggest quantitative driver of the gap between Stryker’s reported growth and the organic market CAGR. Buying into faster-growing adjacent categories, like thrombectomy through Inari, directly adds growth points that don’t show up in any single underlying market’s CAGR, because Stryker is importing growth from categories it didn’t previously participate in at all. As long as Stryker maintains its deal pace and targets genuinely high-growth niches, this driver should persist.
Finally, Stryker’s clearest leadership positions — neurovascular, orthopedic robotics, and increasingly vascular via Inari — happen to sit in some of the higher-growth sub-markets, while its weaker #2 positions (knee/hip implants, endoscopy) sit in the slower-growing, more mature 4-6% categories. That’s not coincidental; it reflects deliberate portfolio-shaping through the M&A strategy, continuously rotating capital and attention toward the categories growing fastest.
Really, I see no reason why Stryker wouldn’t maintain its pace of outperformance – I deem it more likely to grow the gap to industry averages given its positioning.
So, all things considered, what can we realistically expect from Stryker in terms of growth over the next 5-10 years?
Looking at the expected industry growth rates, Stryker’s positioning in faster-growing verticals, and its potential for market share gains, I think a base-case organic growth rate is likely in the 7-9% range, pretty consistently. Add to that continued strategic M&A, which has historically added about 1-3 percentage points, and I get a reasonable 5-10-year growth rate of 9-11%. This is very much in line with recent years, with little pointing to this changing.
Financial & Performance Review
In recent years, Stryker has delivered excellent growth well ahead of the market. Over the past 5 years, Stryker has grown its top line at a 10% CAGR, roughly 400 bps ahead of the underlying market. And this isn’t a standout – in the 2016-2019 period (pre-COVID), it grew revenue at an 8% CAGR, roughly 300 bps ahead of the market. That is an excellent track record over the past decade, and Stryker has delivered that growth consistently, as highlighted below: in 2023-2025, organic quarterly growth was in the 9-12% range. That is what a reliable MedTech compounder looks like.
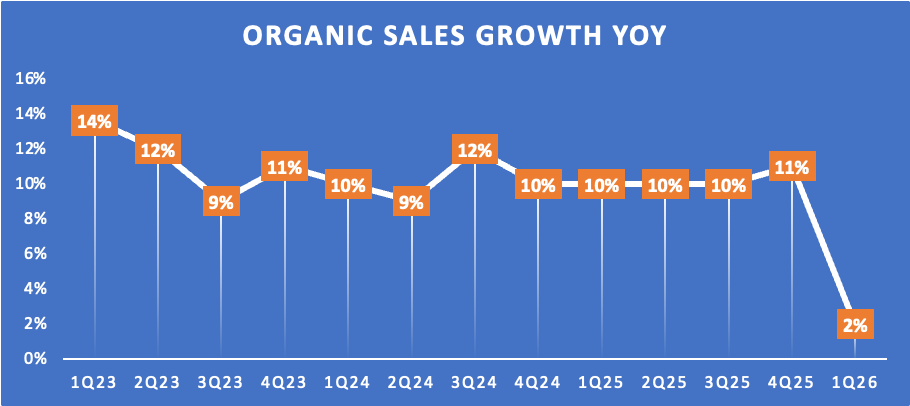
Yet you can also immediately see the huge drop in growth that Stryker reported in the most recent quarter – Q1 2026 – which it released in late April. Stryker reported Q1 organic sales growth of 2.4% (2.6% reported), driven by 1.9% growth in the U.S. and 3.9% internationally. Furthermore, M&N was up 1% YoY organically, and orthopedics up 4%, both also significantly down from recent quarters.
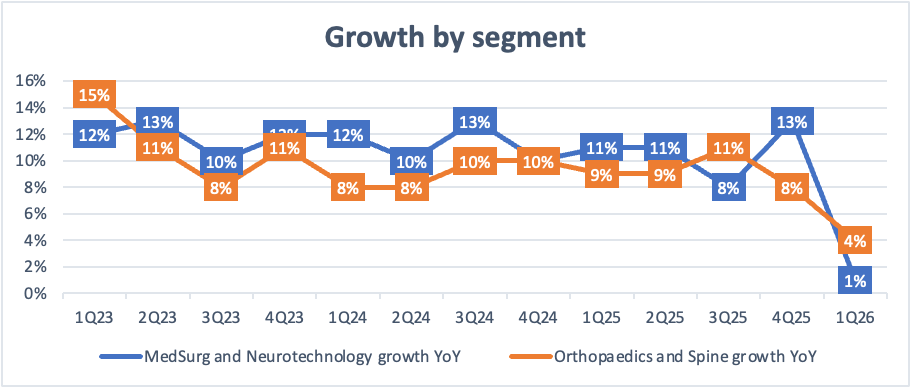
Crucially, this much weaker performance across the board is just a one-off, as it has a unique cause. You see, Stryker was hit by a cyberattack (a wiper attack, not ransomware) on March 11, carried out by an Iran-linked hacktivist group, permanently deleting data from 40,000 laptops. Furthermore, the attack disrupted patient scheduling, delayed shipments, even affected revenue recognition, and, more broadly, paralyzed order processing, manufacturing, and shipping. This is entirely why these Q1 numbers look so poor.
Yet, most importantly, management made it very clear that this does not reflect a loss in demand or orders. Here is a quote from management:
“We’ve come out of this very strong. There isn’t really any business I could think of that we’ve lost.”
So, demand is deferred rather than destroyed – the orders and procedures missed out on in Q1 due to the attack didn’t disappear; they got pushed later in the year, and management still expects all of these to be realized in 2026. In fact, management left its pre-attack guidance unchanged, perfectly highlighting exactly this.
So, what the Q1 numbers reflect is not a demand slowdown, but an inability to process orders, ship products, and complete the administrative steps needed to recognize revenue within the quarter, even though the underlying customer need and hospital orders were still there.
Much more importantly, management indicated that underlying demand across its portfolio remained healthy in Q1; procedural volumes were solid (supported by favorable demographics and the continued adoption of robotic-assisted surgery); hospital CapEx was steady; and Stryker’s order book remains elevated. Additionally, Mako installation in both the U.S. and abroad hit record highs in Q1, as well as rising utilization, despite the late-quarter disruptions, which is a very strong signal.
Moving to the P&L, Stryker’s Q1 results are similarly affected by the cyberattack, but the underlying trend remains excellent.
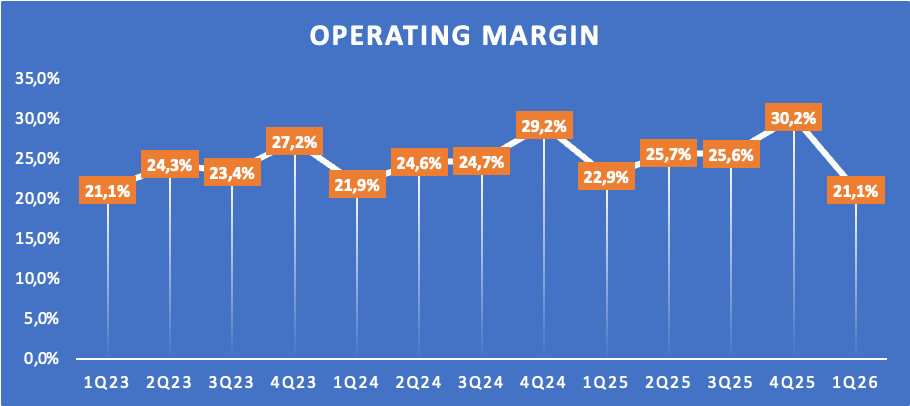
Stryker delivered a 63.6% gross margin, down 190 bps YoY, primarily reflecting reduced manufacturing absorption due to production shutdowns resulting from the cyber incident. Simply put, costs were as expected, but revenue was significantly lower due to the attack, leaving less revenue to cover costs and thus driving down margins. On top of that, Stryker also saw a slight headwind from tariffs.
Further down the line, this resulted in an operating margin of 21.1%, down 180 bps YoY, driven by the gross margin pressure and the deleveraging impact of lower sales growth on operating expenses, partially offset by underlying operating leverage and cost discipline, which is key. Q1 was an exception due to a one-off incident, but looking at the results in recent years, Stryker has been delivering fairly consistent margin expansion. It is in no way mind-blowing, but from a steady and mature compounder like Stryker, 50-100 bps of margin expansion is excellent, and that is what it delivers.
60 bps of expansion in 2023
200 bps of expansion in 2024
100 bps of expansion in 2025
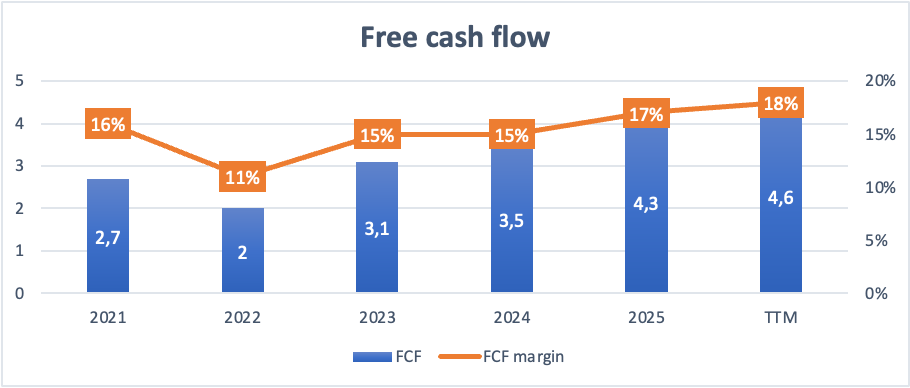
Finally, Q1 EPS was $2.60, down 9% YoY, reflecting lower sales, reduced manufacturing absorption, and higher interest expense. And Q1 FCF totaled $415 million, bringing the TTM total to $4.6 billion, reflecting an excellent 18% FCF margin, the best in years, and reflecting very healthy levels, despite Q1 disruptions.
This allowed Stryker to maintain a healthy balance sheet, ending Q1 2026 with $3 billion in cash and $15.2 billion in debt, leaving the company with a net debt of $12.3 billion. Obviously, it isn’t the most pristine balance sheet, but compared to peers and industry standards, it is absolutely solid, especially given the excellent cash flows and revenue reliability.
This allows management to remain opportunistic in M&A while returning substantial cash to shareholders. Over the last decade, roughly 70% of deployed cash has gone to M&A, with the remainder returned to shareholders through buybacks and dividends.
Looking at the dividend, shares now yield 1.08% at a 26% payout ratio, a solid yield that remains well covered. Even more exciting, Stryker has raised the dividend for 32 consecutive years and maintains a high-single-digit growth rate, making it quite a compelling dividend growth stock.
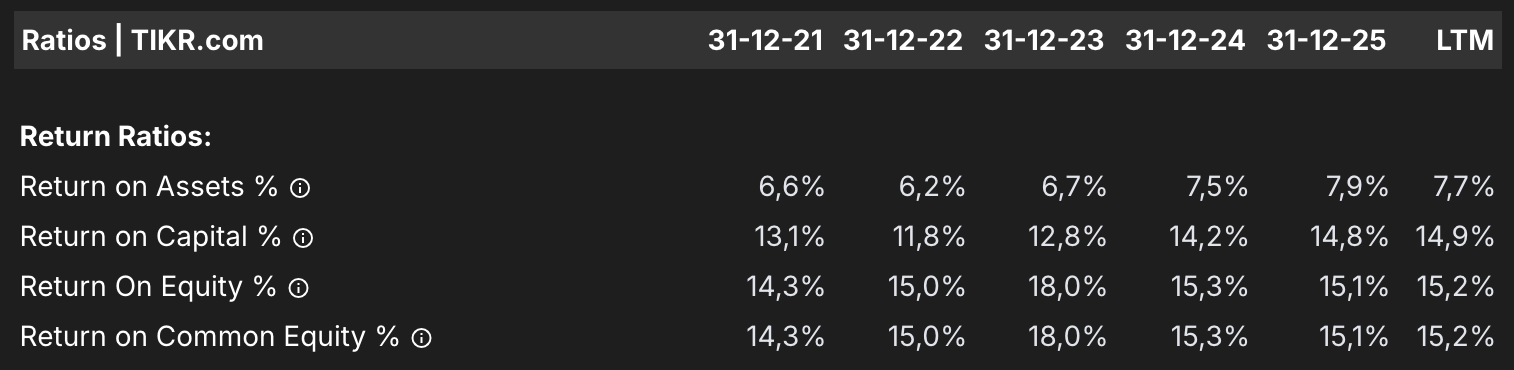
Finally, Stryker’s reinvestment metrics also look good. Its TTM ROIC and ROE both sit at 15%, with ROIC specifically having trended up nicely in recent years, which is perfect. A rising ROIC (return on invested capital) shows that the company is generating more profit from every dollar it has invested in the business, whether that capital comes from equity, debt, or retained earnings, meaning management is deploying capital into increasingly productive uses rather than just growing for growth’s sake. Especially with Stryker’s heavy M&A strategy, it suggests the acquisitions being funded aren’t just adding revenue; they’re adding profitable, well-integrated revenue that’s improving the overall efficiency of the capital base.
In short, this rising ROIC is evidence that growth is being bought and built well, not just bought at any cost.
Overall, excluding a one-off impacted quarter, Stryker’s financials look excellent and are moving in the right direction. In my view, there is a lot to like here and not that much to dislike. This is a business in excellent shape – stable and strong growth, gradually expanding margins, excellent cash flows, a solid balance sheet, top-notch reinvestment metrics, and a compelling dividend story.
With that, let’s finally delve into the outlook and valuation!
More content like this? Consider InvestInsights Premium
InvestInsights Premium is designed to help you find best-in-class compounders, identify deep-value opportunities, avoid costly mistakes, and stay focused on fundamentals when markets get noisy, with full transparency into how I make decisions over time.
In practice, this gets you:
6–8 Research Reports per month, 2x more than free subs do, which includes 3-4 Deep Dives like this one!
Full visibility into my personal portfolio, including allocations, transactions, and conviction levels
An overview of target prices and ratings, updated weekly
Price tag? Only $95 per year or $9.50 a month. That comes to just $1 per analysis, with the rest provided at no cost.
Sound useful? You can upgrade to Premium today using the button below!
Outlook & Valuation
As always, let’s start with management’s guidance. Crucially, despite the cyberattack disruption, management left the 2026 guidance unchanged, expecting missed revenue to be realized in the remainder of the year, helped by healthy procedural volumes and strong demand for capital products amid healthy hospital budgets.
So, for 2026, management still guides for organic sales growth to be in the range of 8% to 9.5%. Most of the first quarter’s lost sales will be realized in the second half of the year due to rescheduling of procedures.
On the bottom line, management expects some pressure on input costs from geopolitical conflicts around the world, but also expects some of that pressure to be mitigated by strong execution and operating leverage. Therefore, management still guides 2026 EPS to the range of $14.90 to $15.10, up an excellent 10% at the midpoint, reflecting some margin expansion.
Especially given the Q1 disruption, this is absolutely excellent guidance, with full-year growth in line with what we have come to expect from Stryker.
During the 2025 investor day, management also disclosed its targets through 2028. These are the following:
Revenue to grow at the high end of MedTech, similar to recent years, likely in the high single digits.
150 bps of cumulative operating margin expansion, including M&A dilution, through operating leverage, pricing discipline, and automation. This comes down to 50 bps a year.
Double-digit EPS growth, through a combination of healthy organic growth and expanding margins.
70-80% FCF conversion, in line with recent years.
Once again, that is excellent guidance, with management pointing to a growth trajectory similar to what we saw in recent years and in line with the base-case assumption I discussed earlier. As discussed, I think a base-case organic growth rate is likely in the 7-9% range, pretty consistently. Add to that continued strategic M&A, which has historically added about 1-3 percentage points, and I get a reasonable 5-10-year growth rate of 9-11%.
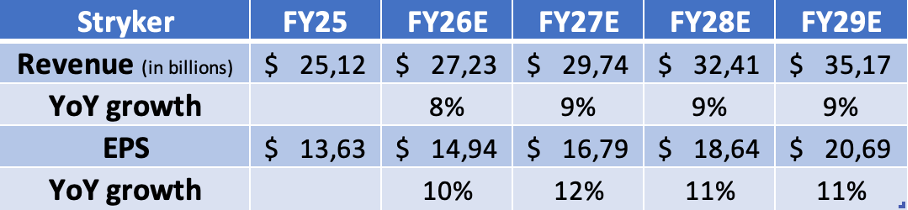
With that, let me jump to my own medium-term forecast. For 2026, I am a bit cautious, as I still see a risk that some Q1 procedures and deliveries may be delayed and pushed into 2027, contrary to management’s expectations. Therefore, I anticipate revenue at the low end of the guided range, growing just over 8% in 2026, with a minimal M&A contribution. On the bottom line, I have applied similar caution, with EPS at the low end of the guidance range.
Looking ahead, I expect a strong 2027, with some 2026 revenue potentially pushed out and a full normalization of operations otherwise. Not yet factoring in any M&A given the unpredictable nature of this, I expect Stryker to consistently deliver high-single-digit (8-9%) growth through 2029, with 1-2 percentage points of upside by M&A. I deem this pretty reliable given underlying growth rates and structural demand drivers.
On the bottom line, I expect Stryker to deliver margin expansion in line with its targets, so between 50-100 bps annually, driving slightly faster EPS growth in the low-teens.
These assumptions are reflected in the financial model below.
That brings me to valuation, and as Stryker shares have underperformed quite significantly over the past year (down 16%) and YTD (down 6%), they look quite attractively priced today, trading well below historical averages, despite Stryker clearly not slowing down. At a current price of $330, shares trade at:
22x 2026 earnings, a 12% discount to the 10-year average of 24.9x
34x 2026 FCF
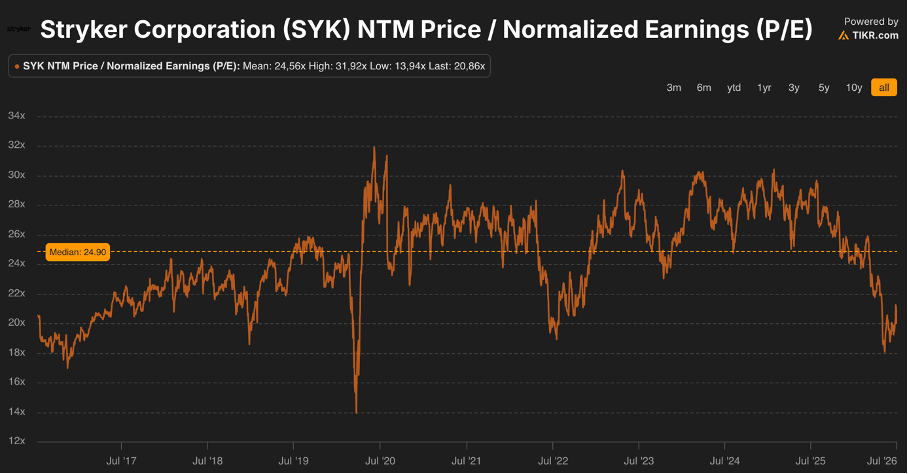
Clearly, Stryker isn’t cheap at 22x earnings for a business growing in the high single digits. But you aren’t just paying for growth; you are paying for consistency, reliability, and quality. Stryker has proven itself to be one of the most reliable compounders in healthcare, consistently delivering excellent growth and margin expansion through cycles. I mean, just one quarter of negative growth since 2013, consistently delivering growth several percentage points ahead of the market, and growing high-single digits to low double digits. That is a strong track record.
Meanwhile, Stryker has a strong moat, clear competitive advantages, and is leaning toward higher-growth vectors, particularly its robotics position, which is highly compelling and translates into a strong outlook. Furthermore, the business is in excellent financial health, sees room for continued margin expansion, delivers strong and improving reinvestment metrics, and has a healthy balance sheet supported by strong, reliable cash flows.
Really, this is just an excellent business and a very high-quality pick. I don’t mind paying a premium for a business I can count on to grow in the high single digits, at least, with low-double-digit EPS growth, without really having to worry about disruption, competition, or cyclicality.
This is a SWAN (sleep well at night) stock now trading at a discount to a justified historical multiple, as the sector has fallen out of favor and the cyberattack spooked investors. That creates opportunity.
Say we apply a 24x earnings exit multiple on the stock. That is still a slight discount to its 10-year average and the mid-to-high-twenties multiple Stryker traded at in the 2020-2024 period (a 5-year average of 27-28x), and it seems more than justified here. Using that multiple and my 2028 EPS forecast, I calculate an end-of-2028 target price of $447, which implies annualized returns of roughly 14%, including dividends.
While that does not quite meet my 15% target, I do believe this represents an excellent risk-reward for such a high-quality stock as Stryker. And let’s not forget that there is plenty of upside potential in my financial forecast, as it does not factor in M&A, which can easily contribute 1-2 percentage points to the top- and bottom-line numbers.
In my view, anywhere below $336, Stryker is a clear buy, with recent weakness offering up an excellent opportunity to pick up some shares. If shares drop below $315 again, I would be adding more aggressively.
Personally, I don’t own any shares yet, but I am compelled to initiate a position right here.
Rating + fair value: Buy — Accumulate below $336
2028 Target Price: $447
Implied CAGR from current price: ~14%
Please leave a like if you enjoyed this post and found it valuable!

Six weeks of frozen order processing looks identical to real demand loss on a chart, but they’re not the same thing. Worth flagging though, our own screener actually lands opposite your buy call as we score Stryker 66.5 with fair value near $254 versus a $330 price, and ROIC at 10.1% is softer than you’d expect given the moat (likely the M&A still proving itself out). Not a knock on the thesis, just shows how much a “buy” here depends on how far out you’re willing to underwrite the growth.