

Last week, semiconductor design giant Synopsys released its fiscal Q4 financial results, and it delivered. The results were well received by investors, with the company beating the top- and bottom-line Wall Street consensus, and issuing upbeat guidance on EDA demand strength.
After the 37% sell-off following its Q3 report, this was a welcome positive for Synopsys shareholders and a confirmation that the investment thesis for this brilliant business is anything but broken – while the business is facing its fair share of short-term headwinds, Synopsys still sits in a brilliant position to benefit from the technology inflection we are seeing in the semiconductor industry as a result of the AI boom.
Simply put, the AI boom is driving explosive demand for high-end chips for data center AI training and inference. These chips are orders of magnitude more complex than traditional CPUs or mobile SoCs, integrating massive parallelism, advanced packaging, cutting-edge process nodes, and increasingly heterogeneous architectures (GPUs, NPUs, chiplets, HBM, interconnect).
Designing such chips is no longer possible with legacy tools or incremental improvements. It requires best-in-class electronic design automation (EDA) software, deep semiconductor IP, and advanced verification capabilities. That is where Synopsys comes in.
Synopsys is the global leader in EDA software, operating in a duopoly with Cadence, and is one of the leaders in semiconductor IP, trailing only ARM in revenue. As a result, without it, modern semiconductor design would be impossible. Highlighting this, Nvidia CEO and founder Jensen Huang even calls Synopsys’ EDA and IP products “mission-critical” to the company’s business and design process.
As AI accelerators push the limits of physics at 3nm and below, design cycles are getting longer, verification costs are rising, and the risk of a single tape-out failure is enormous. This dramatically increases customers’ willingness to spend on Synopsys’ mission-critical, deeply embedded tools, which are effectively non-discretionary due to the simple necessity, and demand grows as semiconductors become more complex.
Crucially, Synopsys benefits regardless of which AI chip vendor wins. Whether it’s NVIDIA, AMD, hyperscalers designing custom silicon, or a new wave of AI-first startups, every advanced chip must be designed, verified, and validated using EDA tools, and Synopsys is one of two options. This makes Synopsys a classic “picks-and-shovels” play on the AI boom, with structural demand growth, strong pricing power, and exceptional long-term visibility.
Synopsys operates a subscription-based revenue model, has a non-cancellable backlog of over $11 billion, and enviable geographic diversification, with no single region accounting for over 50% of revenue and minimal exposure to China.
It is a brilliant buy-and-hold stock, especially amid technology inflections.
Today, I want to update my investment thesis by going over the fiscal Q4 results and further developments, ultimately updating my financial projections and fair value estimate.
Let’s delve right in!
Welcome to InvestInsights — an independent equity research publication rooted in long-term, buy-and-hold investing, publishing actionable stock/equity research reports weekly!
📈 You’re reading my latest exclusive stock analysis. If you like this analysis, make sure to like & subscribe to receive much more like this!
If you’d like full access to this post and all my other exclusive analysis & portfolio access (16% CAGR since 2022), consider becoming a paid subscriber!
Synopsys delivers a solid quarter
Jumping right into the numbers, Synopsys reported total Q4 revenue of $2.25 billion, which sat at the high end of the guided range and beat consensus estimates by $130 million. Furthermore, on a reported basis, this was up 38% YoY, yet it includes a $668 million contribution from Ansys, as the acquisition closed late last quarter.
If we exclude Ansys, we can see that the core Synopsys operations saw revenue decline 3% YoY, as the company continues to face headwinds in semiconductor IP.
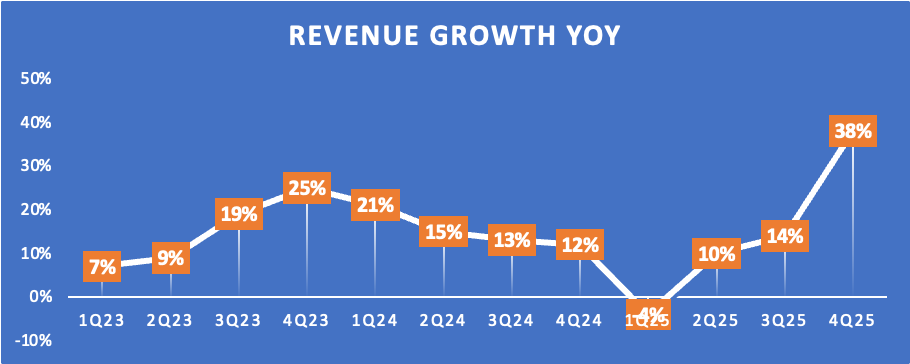
Following this strong fourth quarter, total fiscal FY25 revenue came in at $7.05 billion, bang on in line with my prior forecast. This reflects a 15% YoY increase, but again, this includes a $757 million contribution from Ansys.
Excluding the revenue contribution from Ansys, Synopsys grew revenue in fiscal 2025 by just 3% YoY due to these same IP headwinds in the second half of the year, as well as challenging conditions in China, where revenue was down 22% in fiscal 2025.
You see, earlier this year, Synopsys faced a 6-week export ban imposed by the U.S. government on its Chinese operations, and while this period in itself didn’t impact the business excessively, the effects continue to linger due to changed customer behavior. Here is how management put it last time out:
“Customers were questioning whether or not they will invest in a multiyear commitment with Synopsys, how broad will they make that investment? If they start an investment in a chip, can they finish it? Can they tape it out?”
Chinese customers are simply hesitant to sign a large contract with Synopsys, given their awareness of the risk of new restrictions that could significantly impact their chip development. The implications of losing access to Synopsys systems or IP halfway through chip development would be detrimental, so this caution makes sense.
This continued to be a drag in Q4, impacted the full-year results, and will likely continue into 2026. Positively, it is only short-term headwind, and China accounts for only a low-teens percentage of total revenue, so the impact is manageable.
On top of China headwinds, there was the considerable drop in momentum in Synopsys’ IP business in H2, which I already alluded to, that was an even larger drag on Q4 and fiscal FY25 results, with IP revenue in Q4 down 21% YoY, leading to fiscal FY25 revenue of $1.75 billion, down 8% YoY.
Apart from the fact that Synopsys’ IP operations are more exposed to the previously mentioned China-related headwinds, the segment faces two additional headwinds that have become a significant drag on performance in H2.
First of all, Synopsys’ IP business has been negatively impacted by ongoing execution issues at Intel, one of its largest and most strategically important customers. Synopsys had invested heavily in expanding its IP portfolio to support Intel’s foundry ambitions, expecting volumes to ramp meaningfully. However, continued delays and uncertainty in Intel’s manufacturing roadmap have pushed out that ramp, delaying revenue recognition and weighing on IP results in the near term.
Secondly, and more importantly, Synopsys is in the midst of a deliberate internal transition within its IP segment, shifting resources away from lower-value, standalone IP blocks toward more complex, higher-value offerings such as subsystems and chiplets. While strategically sound and well aligned with AI and data center demand, this portfolio realignment has created temporary friction, as legacy IP revenue declines faster than new offerings can scale, resulting in a short-term drag on growth.
Positively, both headwinds should ease throughout 2026, as Intel receives the necessary support from partners such as the U.S. government and Nvidia to become more competitive again, and Synopsys’ IP portfolio shift will better position it for outsized growth in the decade ahead.
So, while short-term growth is lackluster, this isn’t a structural issue, and I am expecting improvement in late 2026.
Nevertheless, the Q4 drag was significant, and this is what led to negative YoY growth in Synopsys’ core operations.
Positively, this weakness in IP revenue was largely offset by EDA strength. Excluding the contribution from Ansys, EDA revenue in fiscal FY25 was up 8% YoY, helped by the increasing engineering complexity of AI and high-performance computing, with EDA once again proving its role as the company’s structural growth engine.
This EDA strength is now being further amplified by the successful integration of Ansys. Following the completion of the planned divestitures of the Optical Solutions and PowerArtist businesses, management highlighted that the Ansys integration is progressing well, with restructuring actions already underway to drive efficiency and accelerate the realization of cost and revenue synergies. Strategically, Ansys significantly diversifies Synopsys’ revenue base, expands its customer footprint beyond traditional semiconductor customers, and materially broadens the company’s total addressable market.
The combination positions Synopsys as the clear leader not only in EDA, but also in simulation and analysis, enabling it to bridge digital chip design with real-world physical behavior, a capability that is becoming increasingly critical as AI, advanced packaging, and system-level complexity converge.
Taken together, while IP-related headwinds masked underlying strength in Q4, Synopsys’ core EDA franchise is not only resilient but strengthening. With Ansys solidifying Synopsys’ leadership across both digital and physical design, and AI-driven engineering complexity acting as a powerful secular tailwind, the company is increasingly well-positioned to compound value as short-term noise fades – it is critical to remain focused on the fundamentals here.
This strength and improving momentum are already visible in its backlog, with bookings strength in Q4. The company now has a non-cancellable backlog of $11.4 billion, up from $10.1 billion at the end of Q3.
On that note, let’s get to the bottom-line results.
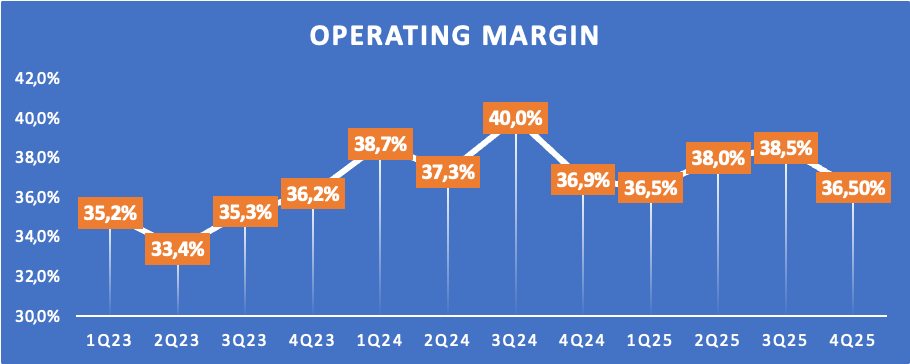
Q4 operating expenses were $1.43 billion, reflecting almost 50% growth in R&D expenses and an additional $150 million in amortization expenses, of course, also including a contribution from Ansys. Nevertheless, the operating margin held up relatively well at 36.5%, down 40 bps YoY, though this includes some non-recurring acquisition-related costs.
Therefore, I expect this number to trend upward in the coming quarters, also helped by planned efficiency gains, including a recently announced 10% workforce reduction following the completed acquisition.
Ultimately, this resulted in a Q4 EPS of $2.90, beating estimates by $0.02 and sitting above the high-end of guidance. For fiscal 2025, this then totaled $12.91, down 2% YoY due to a 6% higher share count following the Ansys acquisition, offsetting 4% growth in net income.
Obviously, the higher share count will continue to weigh on EPS in the coming quarters, likely resulting in subdued growth.
Additionally, the numbers above are non-GAAP and therefore don’t include SBC. Q4 SBC was 11% of revenue, and was up 44% YoY, in part due to the Ansys acquisition. As a result, FY25 SBC was also up 36% YoY, reaching 13% of revenue, up from 11% in 2024.
Personally, I find these numbers acceptable, especially since they should be up only temporarily, and the 10% headcount reduction is likely to also lead to a drop in SBC, so we should see this trend down toward the end of fiscal 2026.
Finally, Synopsys reported a fiscal 2025 FCF of $1.35 billion, ahead of expectations and reflecting a FCF margin of 19%, down from 21% in 2024 and 26% in 2023, driven by lower margins and slower revenue growth, as noted earlier.
Positively, these pressures are largely transitional in nature. Synopsys continues to generate strong operating cash flow, supported by its highly recurring revenue base, long-term customer contracts, and mission-critical positioning within semiconductor design workflows.
As growth reaccelerates and Ansys synergies are realized, management expects margin expansion to resume, positioning free cash flow to grow faster than revenue over the medium term. In that context, the current FCF margin compression should be viewed as a temporary reset rather than a structural change in Synopsys’ cash-generating capability.
I see its FCF margin gradually recover toward and over 30%, which, combined with strong double-digit revenue growth, should translate into excellent cash flows in the coming years.
Meanwhile, Synopsys maintains a solid balance sheet, nonetheless. It ended Q4 with $2.96 billion in cash, including approximately $600 million in proceeds from the sale of the Optical Solutions Group and Ansys PowerArtist business. Meanwhile, total debt did total $13.5 billion, but on top of $1.7 billion in debt repayment in Q4, management anticipates repaying another $2.55 billion in 1H26, in part fueled by the $2 billion from the Nvidia stake.
So, as Synopsys is rapidly bringing down this debt load and should see strong FCF growth in the coming quarters and years, I am not too worried about this.
On that, let’s get to (arguably) the most important part for investors: the outlook!
Want more out of your subscription? Even more content like this weekly? Consider InvestInsights PRO — $7.50/month ($70/annually)
PRO gets you:
A guaranteed minimum of 6-8 stock analyses every month (of which at least 3-4 are paid-exclusive).
Full insight into my own portfolio, including allocation, transactions, watchlist, and performance (16% annualized return since January 2022).
Instant transaction alerts anytime I buy or sell any shares (Fully transparent).
An overview of all my target prices and ratings (available online, updated weekly).
Access to the InvestInsights Hub, containing all of the above in a single online sheet, updated constantly!
Outlook & Valuation
Management was very upbeat during the earnings call regarding 2026 and issued bullish guidance that surprised positively, especially considering the short-term headwinds that it continues to face.
