

It’s been a tough stretch for The Trade Desk (TTD) in most of 2025, with shares down 64% YTD and 67% over the last twelve months.
After years of near-flawless execution, the company’s stock has come under heavy pressure this year as a mix of adverse developments sparked concerns about its long-term competitiveness in the increasingly crowded digital advertising industry.
For one, growth has slowed meaningfully. After years of 25%+ expansion, revenue growth has cooled to the high teens, and management expects this to persist in the near future. With shares trading at 50x earnings before the August sell-off, the combination of softer numbers and conservative guidance created a valuation mismatch. Simply put, the stock had been priced for perfection, and The Trade Desk finally stumbled. Its premium became increasingly hard to defend, and shares sold off accordingly.
At the same time, competitive intensity has picked up. For years, TTD held a leadership position in the open internet and CTV ad-tech stack, but that dominance has come under question. Amazon’s recent ramp-up of its DSP efforts, integrating Prime Video inventory and signing a major CTV ad deal with Netflix, has sparked fears that TTD’s opportunity set is shrinking.
There’s no denying that, at least at first glance, the TTD investment thesis has become more complicated.
Yet, at the same time, what Wall Street seems to overlook amid all these developments is that TTD remains structurally well-positioned and that its competitive/technological position hasn’t weakened – TTD’s technological stack and pace of innovation remains unmatched! The company remains in the prime position, being one of the leaders in programmatic advertising, to fully benefit from the eventual shift to the open internet.
For reference, a UK study found that ~60% of users’ time is spent on the open internet, while advertisers are still spending around 70% of their budgets inside walled gardens, indicating that there is still a long way to go. Ultimately, advertising dollars will shift to the most efficient channels - every industry eventually shifts to efficiency – and that is achieved on the open internet, with greater transparency, richer data interoperability, and true price discovery that aligns cost with performance.
As walled gardens like Meta, Google, and Amazon continue to limit transparency and take rates remain opaque, TTD stands out by offering neutrality, cross-channel access, and accountability, qualities that matter more than ever as ad buyers seek measurable ROI across CTV, mobile, web, and audio. Meanwhile, the secular migration of ad spend toward connected TV remains a generational shift in motion, and TTD remains at the center of it. Even if growth is temporarily lumpy, the fundamental direction of travel, from closed ecosystems toward open, data-driven platforms, still plays directly into TTD’s strengths.
Additionally, with a pristine balance sheet (with zero debt), a founder-led culture, and a platform that continues to innovate (Kokai, UID2, and beyond), TTD remains one of the few true long-term compounders in the ad tech industry and a business that checks many of the qualitative boxes I look for.
The stock may have lost some of its shine this year, but the business hasn’t lost its edge. This remains an exciting, founder-led business well-positioned to significantly benefit from secular shifts.
Nevertheless, despite having already sold off heavily in 2025 to date, shares are down another 12% since the company released its Q3 results, falling to a new 12-month low. In fact, shares now trade at their lowest level since November 2022, despite revenue and EBITDA having doubled since then.
The result? This programmatic advertising leader trades at its lowest multiples in over 5 years. Its valuation has dropped from 50x earnings in early August to 23x today, despite the company still projected to grow revenue and profits by mid-to-high teens.
So, were these Q3 results really that bad? Is the Trade Desk investment thesis really falling apart? Is it poised to be overtaken by big tech peers?
Let’s answer those questions by reviewing TTD’s Q3 results in detail, assessing its performance and underlying developments, before addressing competitive threats and making up the balance, updating my financial projection, and revising my fair value estimate.
Without further ado, let’s delve in!
Welcome to InvestInsights — an independent equity research publication rooted in long-term, buy-and-hold investing, publishing actionable stock/equity research reports weekly!
📈 You’re reading my latest [FREE] stock analysis. If you like this analysis, make sure to like & subscribe to receive much more like this!
If you’d like full portfolio access (16% CAGR since 2022) & additional exclusive analyses, consider becoming a paid subscriber!
Trade Desk’s Q3 deserves more credit!
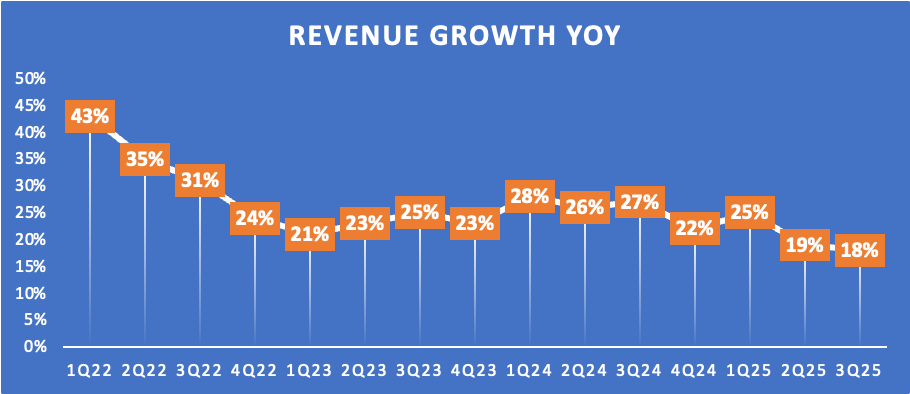
Jumping straight into the Q3 numbers, TTD reported Q3 revenue of $739 million, beating the consensus by $20 million and delivering 18% YoY growth. However, this would be up 22% YoY on a comparable basis, excluding political spend from last year’s U.S. elections.
Actually, I was positively surprised by this growth reported by TTD. Let’s not forget that management had initially guided for only 14% growth, and 18% excluding political spending, which turned out to be much better. Particularly, ex-political spend momentum, which I deem most representative, remains healthy, actually improving from last quarter’s 20% growth.
Especially with shares having reset as much as they have already, TTD still delivering 20%+ comparable growth should be cheered – this now comes at a price tag of just 20x next year’s earnings, remember?
My point is that we have shifted from being bullish on this business and accepting a 50x earnings valuation for mid-twenties growth to being cautious at 21x earnings when growing at a low-twenties rate. It makes no sense. What you see right here is irrational pessimism.
Anyway, yes, while the graph below isn’t a positive one, reflecting decelerating growth, comparable growth accelerated in Q3. It remained healthy at over 20%, driven by the company capturing incremental advertiser wallet share among large global brands, as well as a stable customer retention rate of 95%, which has remained consistent for the last 12 quarters.
This growth was in part driven by more substantial international efforts, where Trade Desk’s presence remains limited compared to the U.S. For reference, TTD still generates 87% of revenue from the U.S. and only 13% internationally, even as 60% of its TAM is outside the U.S.
However, TTD is now increasingly focused on these international markets, and in Q3, this resulted in improved momentum in both the EMEA and APAC regions, outpacing growth in North America.
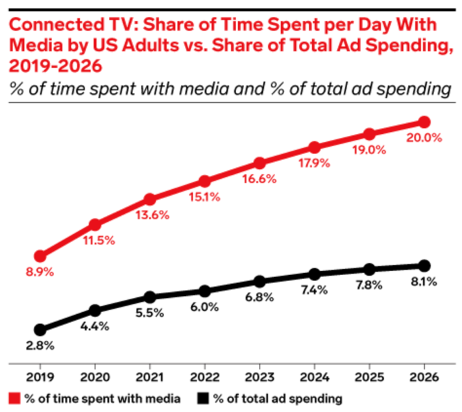
More critically, TTD indicated that CTV continues to be its largest (50% and growing) and fastest-growing channel, still outgrowing its overall business, driven by the continued shift of advertising dollars toward streaming. This shift continues to work very much in TTD’s favor.
CTV should continue to be a growth engine for TTD, as the gap viewed below closes over time, and advertising dollars follow the eyeballs to CTV. For TTD, this means a steadily expanding addressable market and a larger share of premium video budgets that were once locked inside traditional TV or walled-garden ecosystems. As brands reallocate spend toward streaming, they increasingly need a neutral, data-rich platform that allows them to buy inventory across multiple services and measure performance holistically, which is exactly what TTD enables.
And with its best-in-class capabilities, ranging from advanced AI-driven optimization and real-time bidding to identity solutions like UID2 to the Kokai platform, TTD is uniquely positioned to capture this flow of dollars. It offers advertisers precision targeting, transparent pricing, and unified frequency management across the fragmented streaming landscape.
In short, as the line between traditional and digital TV blurs, TTD stands to be one of the primary beneficiaries of this ongoing transformation, particularly with its strength in data-driven, real-time auctions over fixed pricing, which is the direction the industry is going in!
Meanwhile, technologically, TTD remains in a unique position due to its open internet and innovation-driven approach.
What many seem to overlook nowadays, in the face of competition and some operational struggles, is TTD’s unparalleled level of innovation, which often defines the direction of the entire industry. Technologically, TTD consistently remains miles ahead of the competition, and this remains unchanged today.
It was one of the first movers in this part of the advertising market and an early innovator with Unified ID and later UID2, in an effort to build an alternative to cookies. Today, UID2 is becoming the standard on the open internet.
In recent years, it has continued to maintain a high level of innovation by introducing features and additional platform layers that enhance advertiser capabilities, improve advertising ROI, and increase advertiser visibility and transparency. These combined efforts keep it at the top of its class.
Take Kokai. Kokai is The Trade Desk’s next-generation platform, launched in 2023, designed to make programmatic advertising smarter and more automated. It combines advanced AI and machine learning to help advertisers make better real-time bidding and targeting decisions across all channels, especially CTV.
Essentially, Kokai acts as an AI-powered decision engine, analyzing massive datasets to suggest optimal bids, audiences, and placements, thereby improving campaign performance and efficiency. It also introduces a more intuitive interface, enhanced measurement tools, and stronger integrations with partners using Unified ID 2.0, enabling improved identity and attribution in a privacy-first world.
Today, 85% of advertisers on its platform run on Kokai, driven by simply exceptional results. Since its launch, Kokai has delivered an average 26% lower cost per acquisition, a 58% lower cost per unique reach, and a 94% higher click-through rate compared to Solimar, its predecessor.
Before Kokai, Solimar was already recognized as the best-performing DSP globally, and Kokai blew it out of the water. And this performance by Kokai continues to improve as its AI models become more advanced.
In addition to Kokai, TTD also introduced OpenPath, which is another industry-changing innovation. This is The Trade Desk’s direct-supply initiative, designed to provide advertisers with direct access to premium publisher inventory, effectively eliminating unnecessary intermediaries in the digital ad supply chain.
Traditionally, digital ads passed through multiple “middlemen” (like supply-side platforms or exchanges), each taking a small cut and adding latency or opacity. OpenPath streamlines that process by allowing advertisers on TTD’s platform to buy directly from publishers such as Condé Nast, Reuters, or Gannett.
The goal is greater transparency, efficiency, and control: advertisers know exactly where their money goes, publishers keep a larger share of the spend, and The Trade Desk strengthens its position as the most transparent and efficient route to reach premium open-internet inventory.
In 2025, adoption of OpenPath has been significant, with usage growing by “many hundreds of percentage points,” as the need for greater visibility, transparency, and better targeting grows.
What I am trying to point out here is that The Trade Desk continues to define the industry and maintains its technological and subsequent performance lead. While much of the current market narrative focuses on short-term growth noise or competitive threats, the company continues to shape the direction of digital advertising itself. These aren’t incremental upgrades; they’re foundational shifts that redefine how advertisers operate across the open internet.
Kokai and OpenPath are perfect examples of this. One revolutionizes how advertisers make decisions (smarter, faster, and more data-driven), while the other transforms how those ads are delivered, stripping away inefficiencies and reinforcing transparency. Together, they push the industry closer to what TTD has always envisioned: an open, efficient, and accountable advertising ecosystem where every dollar can be traced, measured, and optimized.
As the world’s advertising dollars eventually shift to the open internet and the focus shifts to transparency and efficiency, TTD remains in the prime position to benefit through its better targeting and substantially higher advertising ROI.
It is still in the best position to lead the industry.
Research shows that the average consumer now spends over 60% of their time on the open internet, outside of the walled gardens, yet this is where the far majority of advertising budgets still flow. That results in fewer hours spent and lower ROI, which won’t last. To quote TTD CEO Jeff Green, “this imbalance will correct over time.”
On that note, let’s get to TTD’s bottom-line results.
TTD reported a Q3 EBITDA of $317 million, up 23% YoY and outpacing revenue amid healthy continued margin expansion. The Q3 EBITDA margin improved to 43%, up 200 bps YoY.
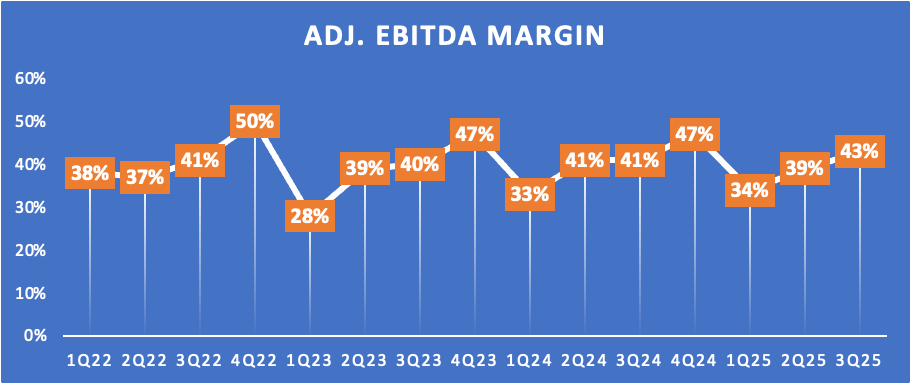
As highlighted above, TTD has consistently improved its margins, despite continued investments in technology and R&D, driven by growing operating leverage and effective cost control. Q3 operating expenses, excluding SBC, were $457 million, up just 17% YoY. On the one hand, platform operation costs were up 32% YoY amid continued investments, but this was offset by just 12% growth in sales and marketing expenses, technology and development expense growth of only 9%, and a decline in G&A expenses, in total leading to improved operating leverage.
Moving further down the line, this resulted in a net income of $221 million or $0.45 per share, up 10% YoY and beating the Wall Street consensus by $0.01.
Finally, FCF was $155 million, representing a 21% FCF margin. TTD maintained a pristine balance sheet, with $1.4 billion in available cash and no debt.
In Q3, management bought back $310 million worth of its shares, which FCF didn’t fully cover, as management is buying back shares opportunistically at depressed price levels. Luckily, management has a strong balance sheet to fall back on, so I like these opportunistic buybacks. In fact, management has approved another $500 million authorization.
Furthermore, since announcing this buyback program in 2023, it has already repurchased $2 billion worth of its own shares, which fully offsets dilution and has resulted in a reduction of outstanding shares over the last two quarters. Repurchases in Q3 brought the YoY share count back by 2%.
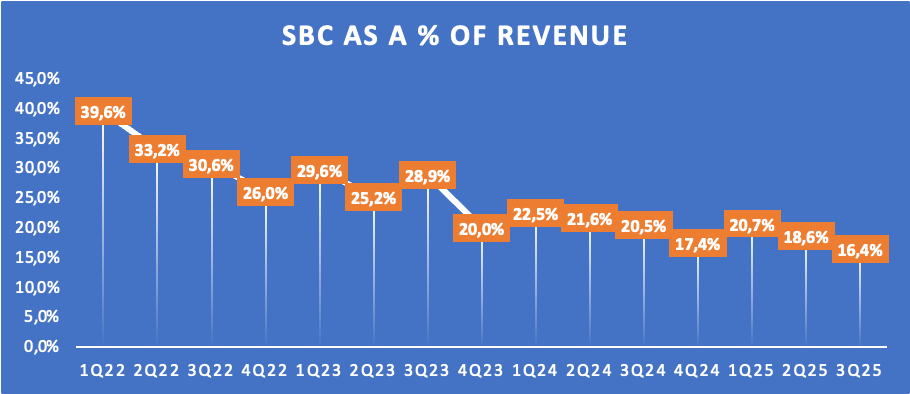
However, most importantly, these buybacks offset investor dilution from SBC, which has often been named as a concern and is now being mitigated. And not only by management offsetting this through repurchases, but also because SBC dollars are declining, at least as a percentage of revenue.
Yes, YTD SBC is still up, but only by 4%. Additionally, in Q3, SBC dollars were down 6% YoY, so we are seeing evident progress on this front. As visible below, SBC as a percentage of revenue has also been steadily declining, hitting a new low of 16.4% in Q3, down 410 bps YoY.
As a shareholder, I very much appreciate this downtrend!
Competitive threats are real, but overestimated
Besides decelerating growth and some operational struggles, another bear argument and developments that have put significant pressure on TTD shares YTD are the emerging competition in the DSP, CTV, and open internet advertising arena, particularly from Amazon.
The e-commerce giant has been ramping up its advertising efforts in recent years to what is now a business doing $70 billion in annual revenue. Initially, this was solely focused on its own e-commerce platform, benefiting from a wealth of user data for effective ad placement on Amazon.com itself. Yet, it has expanded in recent years, now operating its own DSP and entering the CTV market with ads on Prime, as well as on the broader internet.
The most notable move of all here was a deal with Netflix to become its DSP, giving Amazon access to Netflix’s premium ad inventory in multiple key markets starting in Q4 2025. By many, this is viewed as a significant power move by Amazon, as it expands its presence in the CTV/DSP space beyond its own platforms. This could attract additional advertising dollars from other parties, making Amazon a more comprehensive one-stop shop for advertising.
And as if this alone wasn’t enough of a threat to TTD, TTD’s deal with Walmart, its largest retail media customer, had also come under some pressure, reportedly. A report from The Information cited sources, stating that Walmart renegotiated its deal with TTD, which now includes the option to use other ad-buying platforms outside of TTD, once again pointing to competitive pressures.
Furthermore, the report once again highlighted Amazon as a potential second DSP partner to Walmart, primarily due to its significantly lower pricing compared to TTD. You see, reportedly, Walmart has become frustrated with TTD’s pricing, which is reportedly a double-digit fee. Meanwhile, Amazon, in an effort to lure customers away from other parties, such as TTD, has reduced its pricing from 5-7% to just 1%, making it a far cheaper option and adding more pressure on TTD.
With this, it appears Amazon is directly competing with TTD in its own market, and competitive pressure seems to be building, raising serious concerns. How is TTD supposed to compete with these giants in its own market, given their far lower pricing, which is enabled by their size and other cash flows?
In reality, the real situation is actually a bit more nuanced.
First of all, the Walmart partnership isn’t gone. TTD management announced both parties remain fully committed to the partnership. However, management hasn’t denied negotiations or a new non-exclusive deal, which likely means there is some truth to this reporting, indicating that TTD is facing more competition.
Yet, this is unlikely to come from Amazon or other big tech players, at least in this situation. Walmart, like most major retailers, fiercely protects its data, and for good reason. A Trade Desk employee recently noted that Walmart “jealously guards its shopping data” to ensure it never ends up in Amazon’s hands. In an era where user data has become the most valuable currency, especially with the rapid rise of AI and predictive analytics, companies are increasingly cautious about who they share it with.
For retailers like Walmart, data isn’t just a competitive advantage; it’s the foundation of their advertising and commerce ecosystems. Partnering with big tech platforms like Amazon, Google, or Meta would mean ceding visibility and potentially empowering direct competitors. That’s precisely why an independent, neutral platform like The Trade Desk remains an attractive partner. It provides the technology and demand access retailers need without compromising control over their data.
In other words, while competition in retail media and commerce data is intensifying, Walmart’s strategic interests are fundamentally aligned with TTD’s open internet model.
But, even more important than this one deal, the Amazon (or big tech) threat is well overstated. Apart from the argument above, TTD CEO Jeff Green made a good point during the earnings call.
You see, Amazon’s efforts in DSP are still minimal, not significantly impacting TTD. Amazon is expected to generate approximately $70 billion in advertising revenue in 2025, with roughly 95% of this estimated to come from sponsored listings on Amazon.com, competing with the likes of Google, not TTD.
Then there is Prime Video, which is likely to generate another few billion in advertising revenue, competing with Netflix, Disney, and Paramount. So, in other words, like 99% of Amazon’s advertising revenue comes from its owned and operated ad inventory, meaning its external DSP is very small.
Simply put, Amazon’s DSP efforts are focused on Prime Video or non-decision buying, like programmatic guaranteed, which, again, isn’t TTD’s market.
And, yes, driven by their massive size and huge cash flows from other operations, these big tech competitors can enter the market with extremely favorable pricing, with some pricing it at practically zero. Yet, pricing isn’t everything. Technologically, in this market, Amazon is nowhere near TTD, with a far lower ROI and less favorable conditions for advertisers in terms of transparency and control.
TTD is simply a better tool. When the conversation is about value and not straight-up pricing, TTD wins the argument every time. In pure dollars, yes, TTD is a more premium option for advertisers. However, when we also consider the value advertisers receive in return, this comparison is not valid.
To summarize, competitive threats are mounting, and TTD will need to nail execution going forward to avoid losing market share. However, the threat we see today, especially from big tech peers, isn’t as considerable as many fear it is.
TTD is still positioned to lead.
Want more out of your subscription? Even more content like this weekly?
Consider InvestInsights PRO - $7.50/month ($70/annually)
This gets you:
A guaranteed 6+ stock analyses every month (of which at least 2-4 are paid-exclusive).
Full insight into my own portfolio, including allocation, transactions, watchlist, performance, and relevant thoughts (16% return CAGR since January 2022).
Instant transaction alerts anytime I buy or sell any shares (Fully transparent).
A complete overview of all my target prices and ratings (online available).
Access to the InvestInsights Hub, containing all of the above in a single online sheet, updated instantly!
Outlook & Valuation
Following a weaker performance in the first half of 2025 and several operational mishaps that contributed to this growth deceleration, TTD has implemented significant changes to its leadership team. In recent months, the company has welcomed a new COO, CFO, and CRO. On the one hand, the change amid recent struggles makes sense. It is an effort to introduce new energy and a fresh vision as the operating environment evolves.
However, such a rigorous management change also carries risk. Leadership transitions can create uncertainty, especially in a company that has long benefited from a consistent, founder-led culture. Integrating new executives takes time, and alignment on strategy, priorities, and execution isn’t guaranteed overnight, so I am also a little cautious.
That said, The Trade Desk’s strong operational foundation and Jeff Green’s continued presence as CEO should help ensure stability during this transition. Yet, it is still something to be aware of.
On that note, let’s get to guidance.
For Q4, TTD now guides for revenue of at least $840 million, which suggests roughly 19% YoY growth excluding the 2024 benefit of political spend, which would be a slowdown compared to Q3. Yet, we should consider that TTD guides for a minimum, so there is considerable room for upside. Meanwhile, this still sat ahead of an $831 million consensus.
Additionally, management expects a Q4 EBITDA of approximately $375 million. Based on the minimum revenue guide, this reflects an expected EBITDA margin of 45%, which would be down 200 bps YoY.
For FY25, this results in guidance for at least $2.89 billion in revenue and an EBITDA of $1.17 billion, representing a 40% EBITDA margin. Although again, this is a minimum guide.
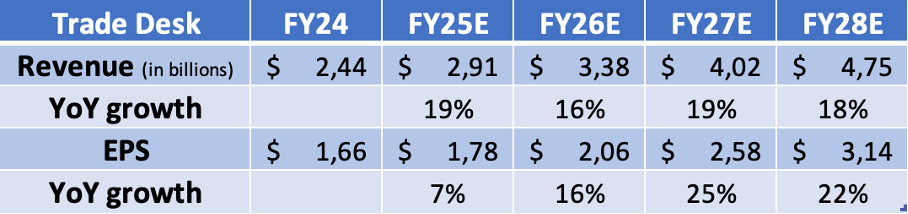
As for my own projections, the Q3 beat and better-than-expected Q4 guidance allow me to raise my revenue forecast, as even management’s minimum guide sits above my prior $2.85 billion estimate. Meanwhile, I expect slightly better growth in Q4, which will lead to a revised forecast of $2.91 billion in FY25 revenue. Additionally, I am also raising my FY25 EPS forecast to account for the Q3 beat. Nevertheless, this is still expected to increase by just 7% in FY25, due to a slightly lower net income margin.
Looking ahead to 2026 and beyond, management indicated it remains confident that it will grow its share of the advertising TAM, while once again improving margins.
Taking this into account, along with the competitive threats discussed, and TTD’s strong positioning and technological leadership, I remain optimistic. While I expect slower growth in 2026 to reflect increased competition and some economic pressure in the U.S., this is likely to reaccelerate in 2027 and 2028, and stabilize in the high teens, as TTD fully benefits from growth in open internet advertising dollars.
Meanwhile, I expect margins to expand again from 2027 onward, taking into account slower growth in 2026 and heightened investments in its platform through 2028. This should lead to some pressure on EPS in 2026, but an acceleration in the years that follow.
I've included my full projections below.
That then brings us to valuation. As I pointed out, TTD shares are being discounted by investors amid these overestimated competitive pressures and the deceleration in growth.
Once again, this sell-off has been well overdone, with pessimism now dominating. Positively, for us long-term investors, this creates opportunity. TTD shares still trade near their 12-month low and their lowest level since November 2022, despite revenue and EBITDA having doubled since then, and the company’s market share having grown substantially. As a result, TTD shares trade at bargain multiples.
At a current share price of 41.91, shares trade at just 23.5x this year’s earnings and 20x next year’s earnings. For a company with The Trade Desk’s competitive position, balance sheet strength, and long growth runway, these multiples look strikingly cheap. Even as TTD is still expected to grow revenue and EPS at a high-teens to potentially low-twenties rate, the stock now trades at valuations typically reserved for mature or cyclical businesses. In other words, the market is pricing TTD as if its best days are behind it, while fundamentals suggest the opposite.
Furthermore, this translates into a growth-adjusted PEG of roughly 1.1x, a 22% discount to the sector median despite TTD remaining one of the most innovative and dominant players in digital advertising. With double-digit revenue growth, strong free cash flow generation, and expanding adoption of its core platforms, such as Kokai and OpenPath, the current valuation appears disconnected from the company’s true earnings power.
Put simply, this is a market leader trading at a mid-tier multiple. The pessimism embedded in the current price offers long-term investors a compelling entry point into a business that still has years of structural growth ahead of it. At these levels, TTD is no longer priced for perfection; it’s priced for doubt, and that creates opportunity.
For reference, even assuming a cautious 25x (EPS) 2027 exit multiple, which is still relatively inexpensive for this kind of growth coming from an industry leader, I calculate an end-of-2027 target price of $65. Based on its current price, this suggests annualized returns exceeding 21%!
In other words, the current risk-reward here is brilliant. With high levels of pessimism now priced into the shares, TTD shares represent excellent value today. Anywhere below $48, TTD shares are a brilliant buy.
Rating: Buy - Accumulate below $48
FY27 Target Price: $65
Implied CAGR from the current price: ~21%
Please leave a like if you enjoyed this post and found it valuable!

TTD likes to say that the walled gardens offer a poor advertising alternative to the open internet - you've seen Meta's tremendous advertising numbers quarter after quarter. Walled gardens can't be as flawed in the experience of advertisers as Jeff Green continually says. Is it a coincidence that TTD's results have hit turbulence just as competitive intensity rises- also a coincidence that TTD has seen the significant senior management turnover you note? Doubtful. Seems to me there is structural pressure on TTD's model - need to really understand that obviously. Not clear to me that what I perceive to be 'stale' bull arguments grasp what's changing. I don't either really- but I don't pretend it's not there. As long as that pressure is there and Jeff Green & Co pretend it's business as usual, I think TTD likely keeps getting de-rated. Why shouldn't TTD trade at, say, 22x -25x GAAP earnings? If so, lots of downside still possible in my view. I'd like to get clarity that the bottom is in- but I don't see that in / from this piece.
Thanks for sharing the article. I have 5% of my portfolio invested in TTD at a cost basis of $56/share. I am very tempted to add to the position. But my feeling is to hold. Interesting times ahead with this one.