

The Trade Desk released its second-quarter results last Thursday, and even though the company delivered headline numbers mostly in line with consensus estimates, shares got absolutely hammered, losing 39% of their value in the following trading session.
Notably, it wasn’t apparent that the results were abysmal. Instead, these were just insufficient, with TTD performing in line, reporting slowing revenue growth, minimal profit growth, and issuing guidance that points to a further deceleration, all while trading at a hefty premium.
Crucially, this sell-off wasn’t about TTD having to match expectation; it has to comfortably beat it. That is what investors expect when they pay 50x earnings for this business, and TTD simply isn’t delivering enough to justify it, at least not when looking at the headline in isolation – it points to growth to drop to mid-teens while advertising peers like Meta and Google are firing on all cylinders.
Honestly, that didn’t look great.
Meanwhile, this is a decent-sized position in my portfolio. I have been very bullish on Trade Desk (which I will refer to as TTD) for years, as I have been fond of TTD’s fundamentally favored positioning, brilliant founder and CEO (Jeff Green), and its long-term prospects, with structural demand shifts working in its favor. Let me lay it out a bit more!
The core reason I'm bullish is that TTD operates in a structurally advantaged position within a massive, growing market. As the leading independent demand-side platform (DSP), it offers advertisers access to the open internet — which includes premium inventory across connected TV (CTV), web, mobile, and audio — rather than limiting them to walled gardens like Meta or Google. This independence is a competitive moat. It aligns TTD with the interests of advertisers, giving them transparency, flexibility, and cross-channel reach that closed ecosystems cannot offer. As ad buyers increasingly demand these qualities in a changing ad world where ROI becomes increasingly essential, TTD is likely to keep gaining share, as it has been doing for years.
The structural shift away from the walled gardens and toward the open internet is undeniable, and TTD is still the best way to benefit.
Second, specifically, the proliferation of CTV remains a key secular tailwind. Traditional TV advertising is rapidly shifting to streaming, and TTD is one of the few players with the infrastructure and publisher relationships to facilitate high-ROI, programmatic ad buying in that space. The company’s continued leadership in CTV — especially as more eyeballs and ad dollars move toward platforms like Netflix, Disney+, and YouTube TV — provides a long runway for growth. Even if the pace of that growth is lumpy quarter to quarter, the direction of travel is clear.
Nielsen recently reported that TV viewing via streaming has risen 71% over the last four years, while broadcast has declined 21% and cable has fallen 39% during the same period.
Streaming is the future of digital advertising, and TTD is leading the market.
Third, TTD's tech platform is genuinely differentiated. With years of investment in AI and machine learning, the company helps advertisers optimize campaigns in real-time and target audiences with precision. And with innovations like Kokai and its Unified ID 2.0 (UID2) initiative, TTD is proactively addressing the shifting privacy landscape — positioning itself as a long-term winner in a post-cookie world. This capacity to adapt and lead change (rather than react to it) is a hallmark of great businesses and brilliant vision.
Lastly, the business model itself is attractive. TTD has historically generated strong margins and free cash flow, with minimal capital intensity. While near-term profitability may look underwhelming due to ongoing investments, the underlying economics remain compelling — especially for a company still in growth mode.
With zero debt, a founder-led team, and a long-term vision, TTD checks many of the qualitative boxes I look for.
So, the objective today is relatively straightforward: determine whether the sell-off is justified, my long-term thesis remains intact, and whether this is an excellent ‘buy-the-dip’ opportunity or not.
Let’s delve right into the numbers and make up the balance!
Still not a paid subscriber? Here’s what you have missed out on these last 2 weeks alone:
American Express – Great Business, Good Quarter, Less Attractive Price
PayPal is a Bargain – A Rare Chance for 19% Annualized Returns
Join the InvestInsights paid community now and get many more high-quality stock analyses (at least six high-quality analyses per month) + all the other paid benefits!
Q2 was a mixed bag, but fundamentals remain strong
Like I said, at first glance, TTD’s second-quarter results didn’t look that bad at all, with its headline numbers sitting roughly in line with consensus estimates, and even guidance roughly matching it. However, the problem with the results was that investor expectations were for TTD to blow past these relatively cautious estimates with ease and keep delivering healthy growth. Yet, this is where TTD fell short, signaling slowing revenue growth and weakening business momentum.
In addition to that, there was the organizational change implemented by management and the sudden change in leadership with the departure of CFO Laura Schenkein, replaced by Alex Kayyal by year’s end, to put additional pressure on sentiment and grow investor concerns.
Starting at the top, TTD reported total revenue of $694 million, beating consensus estimates by $8 billion and reflecting YoY growth of 19%, which is the first quarter of sub-20% in the company’s public history (excluding the second quarter of 2020 due to Covid).
Excluding the political spend, which drove revenue growth for TTD one year ago, growth was up 20% from last year. However, while more positive and representative, this nonetheless signals a slowdown from recent quarters and its slowest ever YoY growth, indicating a loss in momentum and falling short of my expectations.
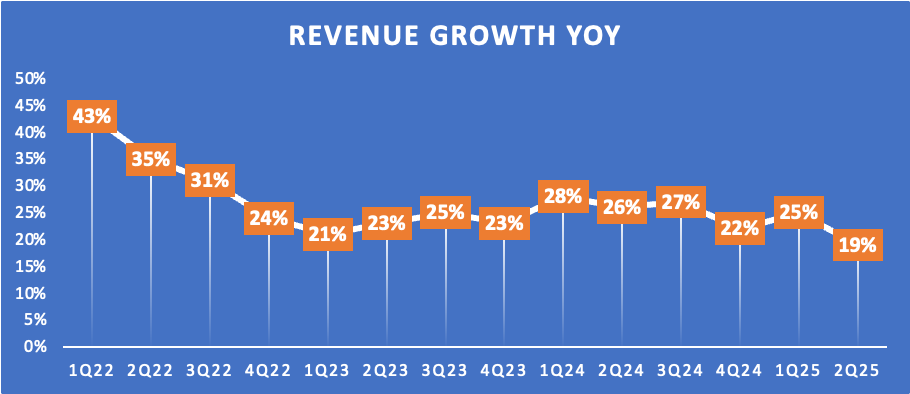
Now, while on the positive side, this growth signals TTD continues to outpace the market and gain market share, it also raises serious concerns over mounting headwinds, including growing competitive pressures and macro concerns.
And while the latter is only temporary in nature (I will get to macro pressures later on), competitive pressures could lead to longer-term headwinds and are a rightful investor concern.
Among the most significant competitive threats is Amazon’s expanding presence in the demand-side platform (DSP) space. As Amazon integrates more inventory from Prime Video and increases its direct advertising capabilities, it creates a robust closed-loop ecosystem that competes directly with the open-internet model TTD champions.
Critically, the threat from Amazon isn’t just hypothetical, but it is happening. And the more profound concern is not necessarily Amazon-specific, but it shows that there is a broader risk of major platforms going more vertically — controlling both inventory and demand — which could lead to pricing pressure and slower win rates for TTD. And if more streaming platforms follow suit, this could weigh on TTD’s growth in Connected TV, which has been a key engine of its expansion.
This is a serious concern that should be monitored, though we shouldn’t start acting as if TTD is already being disrupted, as its competitive and differentiated positioning remains excellent. As Green put it:
“We are playing in a very different sandbox. Ours is focused on decision media, precision, identity, and outcomes. They [Amazon] are still primarily focused on pre-negotiated deals that lack an open identity solution like UID2... None of their strategic decisions or investments suggest that they're trying to buy the open Internet objectively or even that that is a priority.”
This highlights the essence of TTD’s long-term thesis: it is building for the open internet — with a commitment to transparency, privacy-safe identity, and performance-driven outcomes. Innovations like UID2 and Kokai show that the company continues to invest heavily in maintaining its edge, even as the landscape gets tougher. That rate of innovation should help offset some of the mounting pressure from competitors.
Particularly, Kokai, which is the result of years of learning and innovation, gives Trade Desk a significant edge. This is the company’s latest version of its advertising platform. Think of it like a big upgrade that makes it easier and smarter for advertisers to run digital ad campaigns.
With Kokai, advertisers get better tools to help them decide where to show their ads, who to show them to, and how much to spend. It uses advanced artificial intelligence to analyze data and automatically improve performance — so advertisers can get more value out of their budgets without doing everything manually.
It also connects well with The Trade Desk’s identity solution (UID2), helping advertisers reach people in a privacy-safe way across websites, apps, and streaming services. In short, Kokai makes the platform faster, smarter, and more effective — especially as the online ad world becomes more complex.
By now, Trade Desk has 70% of its platform activity run through Kokai, and initial results are brilliant. For example, TTD indicates improvements of 43% in reaching the right target audience and a 73% improvement in cost per acquisition in certain use cases, and it sees an overall more than a 20-point improvement across key KPIs for campaigns running in Kokai compared to its previous system.
Ultimately, in the long run, this kind of technological innovation and differentiation gives me confidence in TTD’s business model – it’s already showing great results today. According to TTD, driven by the excellent performance of Kokai, advertisers using the platform spend 20% more on average, simply because they get a much higher ROI per investment, making it worth more to invest more.
And this is translating into growth for TTD!
Another such example is OpenPath. This is another recent big platform innovation. You see, traditionally, when advertisers use platforms like The Trade Desk to buy ad space, their ads go through several middlemen before reaching a publisher (like a news site or a streaming app). Each middleman can take a cut of the money, and the process can be slow and less transparent.
OpenPath changes that. It allows advertisers using The Trade Desk to buy ad space directly from publishers — cutting out many of the middlemen. This means faster transactions, more transparency, and more of the advertiser’s money going directly to the publisher instead of being lost along the way.
It also gives advertisers more control and better performance data, while helping publishers earn more. So in short, OpenPath is The Trade Desk’s way of simplifying and improving the digital ad buying process — making it more direct, efficient, and fair.
Once again, it improves advertiser ROI and differentiates the TTD platform. Technologically, TTD is far ahead of its peers, and these innovations prove it.
As a result, I believe competitive concerns are overestimated; however, they shouldn’t be neglected but instead monitored closely.
Moving to the bottom line results, TTD reported an adjusted EBITDA of $271 million, reflecting an EBITDA margin of 39% YoY, which is down roughly 200 bps YoY.
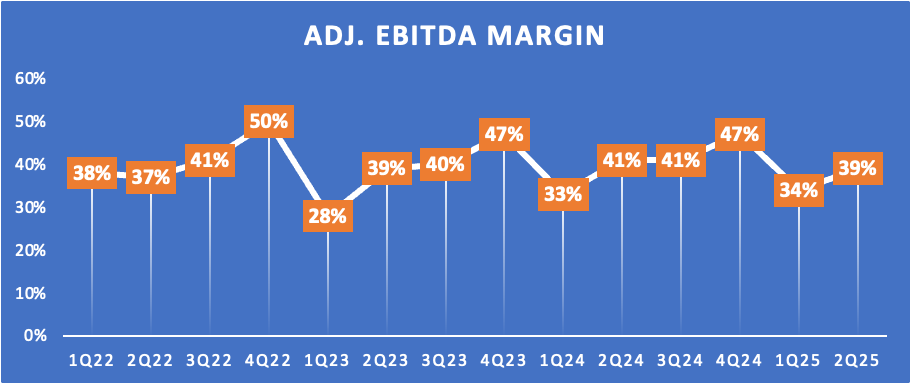
This YoY contraction is the result of slowing top-line growth and management keeping up its rate of investments, with Q2 operating expenses growing 23% YoY to $448 million, amid investments in workforce expansion and platform innovation. As this outgrew revenue, TTD’s margins have come under some pressure, though these are holding up relatively well – some margin volatility is acceptable, as long as it doesn’t become structural.
Further down the line, this resulted in a net income of $203 million, up only 3% YoY. This translated into an EPS of $0.41, which was in line with consensus estimates.
Ultimately, this led to an FCF of $117 million, reflecting a 17% FCF margin, up from 10% one year ago.
This healthy and growing FCF allowed TTD to maintain a healthy balance sheet, holding $1.7 billion in cash and practically no debt, leaving it in excellent financial health.
This allowed it to keep buying back shares. In Q2, TTD bought back $261 billion worth of its shares to offset dilution. Amid healthy cash flows and a strong balance sheet, management plans to keep buying back shares opportunistically.
Ultimately, while TTD’s revenue growth might be slowing and its margins are facing some pressure, its cash flows do remain healthy, and its balance sheet is a fortress. There is no lack of financial health here.
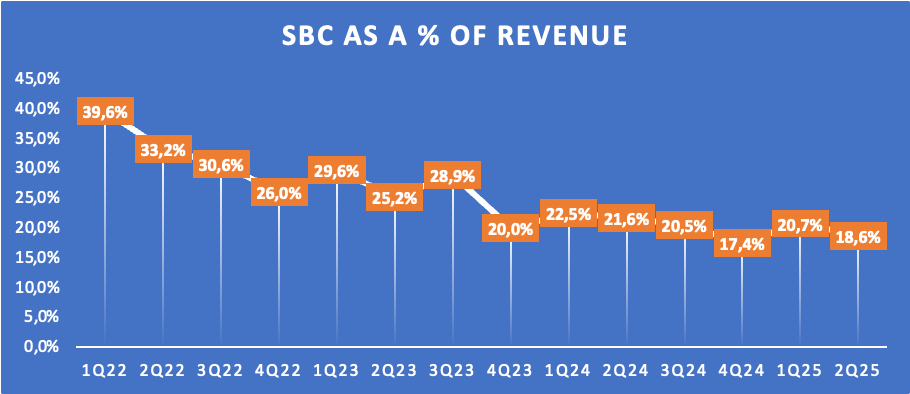
Finally, on a positive note, TTD continues to bring down its SBC as a percentage of revenue, with this falling to 18.6% in Q2, down a very solid 300 bps YoY, which I am very pleased with. Yes, 18.6% is still an elevated number, especially since we’re not seeing explosive growth from TTD anymore, but management is showing good progress in bringing down this number, and it is fully offsetting dilution through buybacks as of Q2, so the impact on investors is now minimal.
Surprising organizational changes
In addition to a slightly disappointing earnings report, some more organizational matters added to the investor concerns.
First of all, there was the sudden announcement of a CFO change, which compounded fears around execution and strategic stability. The Trade Desk announced that long-serving CFO Laura Schenkein will step down, transitioning to a non-executive role through the end of 2025, and will be replaced by Alex Kayyal, formerly a board member and executive at Salesforce.
However, investors are assigning way too much value to this change. Yes, it was very sudden, especially considering how long Laura Schenkein has been in the role, but Alex Kayyal is an experienced successor, and the transition is well-planned, so I do not foresee many issues.
Additionally, TTD proposed an extension of its dual class share structure. In simple terms, the original structure included a 10% dilution trigger: once Class B (super-voting) shares fell below 10% of total equity, they would convert to Class A (one-vote) shares, ending founder Jeff Green’s control.
The proposed and now legally upheld amendment removes that trigger — effectively prolonging Green’s control indefinitely, unless Class B holders decide to convert voluntarily.
So, what does this mean for us investors?
It means the company remains in founder control, which enables bold, consistent decisions without being second-guessed by short-term shareholders. So, it ensures Green maintains complete operational control over the company, which I deem critical at this stage.
Simply put, if you're betting on Jeff Green and The Trade Desk's long-term vision (which I am – its track record speaks for itself), this extension may be reassuring. It lets the company navigate disruption without being derailed by activist investors or quarterly volatility.
So, honestly, I don’t think there are negative takeaways from this.
Want more out of your subscription? Even more content like this weekly?
Consider InvestInsights PRO - $7.50/month ($70/annually)
This gets you:
A guaranteed 6+ stock analyses every month (roughly 2-4 paid-exclusive).
Full insight into my own portfolio (14% return CAGR since 2022).
Instant transaction alerts anytime I make a move (Fully transparent).
A complete overview of all my target prices and ratings (online available).
Exclusive access to the PRO subscribers Discord channel.
Outlook & Valuation
Moving to guidance, TTD now expects to report Q3 revenue of at least $717 million, reflecting YoY growth of just 14% YoY or 18% when correcting for political spend, which signals management doesn’t expect revenue to slow down further (on an adjusted basis), but to remain stable at least. Crucially, this guidance sits in line with the pre-earnings consensus, so this isn’t too bad, especially considering macro headwinds. Furthermore, management guides for an adjusted EBITDA of $277 million, pointing to a stable margin compared to Q1 and down 200 bps YoY.
This guidance is nowhere near as bad as many make it seem, although it is still slightly short of my estimate. However, the key here is that this guidance is based on a stable macro environment. To quote management:
“Assuming the macro environment remains stable and we don't see disruptions from large global brands, which make up a significant portion of our business due to tariff uncertainty, we expect…”
And that is what concerns me. Trump’s tariff policy is incredibly unpredictable, and it’s clear the U.S. economy isn’t in great health, with severe underlying issues. Suppose this pushes the U.S. economy into a prolonged period of economic slowdown or even a mild recession. In such a scenario, these large U.S. multinationals, which comprise a significant portion of TTD’s customer base, may cut back on advertising spend, potentially slowing growth further in 2H25 and into 2026.
Assuming a stable environment seems on the optimistic side to me - more caution is needed, in my opinion.
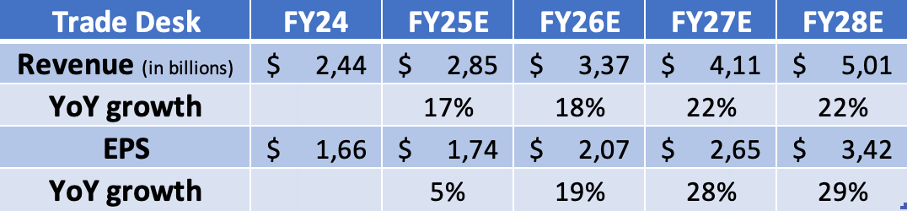
Therefore, I now anticipate weaker growth in the second half of the year, which urges me to cut my FY25 revenue estimate. I now expect revenue to grow by 17% this year, down from 18.4% prior, incorporating some more weakness later in the year amid political spending and macro headwinds. Furthermore, I expect some margin compression to persist, leading to a big EPS cut, now estimated to grow by just 5% in 2025.
Looking ahead to 2026-2028, TTD management is confident that growth will accelerate, and I share this view, as I remain optimistic about TTD’s ability to keep outgrowing peers and benefit from the secular trends driving growth in programmatic advertising. I still view it as the best pick in this up-and-coming industry.
Nevertheless, for FY26, I expect some of this macro weakness to persist, which will hold back growth in the high teens. This will also limit margin growth. Positively, I expect growth to accelerate strongly in 2027 and 2028 as conditions improve and the programmatic advertising market starts growing to a larger share of the entire digital advertising market. Meanwhile, this should also allow for margins to bounce back, leading to high-twenties EPS growth.
Ultimately, I see no real reason to become much more negative on TTD – my long-term thesis remains very much intact, and so I remain bullish.
So, the question remains: is the 39% sell-off justified?
The short answer is “no”. This is a massive overreaction by the market, reacting to seemingly poor guidance and results, combined with organizational changes that are completely misinterpreted, not taking into account underlying factors.
Critically, the TTD thesis is not broken, like at all. While the results are far from perfect, they are not falling massively short of expectations, and there are no signs of any fundamental weakening or competitive disruption. At the same time, we can’t deny that a valuation reset is justified, considering the mild expectations reset and growing competitive risks – the market has just overdone it right now, with shares down 54% YTD!
For reference, TTD shares now trade at just 31x this year’s earnings, down from a pre-earnings multiple of 50x, reflecting a 38% multiple contraction, making shares much more attractively priced. Paying 31x earnings for a company still growing revenue at a high-teens to low-twenties rate and EPS at a mid-twenties CAGR under normalized conditions isn’t too bad at all, especially considering its runway of growth, with open internet advertising still in the very early stages.
Furthermore, if we adjust for forward growth, we end up with a PEG of 1.24x, which is appealing, sitting 55% below TTD’s 5-year average and even 8% below the broader communications sector, in which TTD is still a high-quality standout.
In other words, TTD shares are remarkably cheap right now, after this massive overreaction.
For reference, assuming a conservative 35x FY27 exit multiple (which is easily justified by growth and quality), I calculate an end-of-2027 target price of $93 (down from a prior $107). This suggests potential annualized returns of 24%, which is exceptional indeed.
This makes TTD an attractive buy, with a very favorable risk-reward balance at any price below $66 per share.
Let’s be clear, these 30-40% sell-offs aren’t anything new for TTD shareholders. Expectations are always high due to the business's quality and structural tailwind. Whenever it misses lofty expectations, even slightly, shares get hammered, only to reach new highs months later. This is because these sell-offs are based on short-term numbers, not fundamental issues.
This time is no different. Buy the dip.
Research Conclusion
Long-term thesis remains intact
Near-term slowdown driven by temporary macro + elevated expectations
Competitive pressures are growing, but TTD is unlikely to be disrupted
Strong innovation and market share gains continue
Valuation reset creates compelling buying opportunity
Rating: Buy below $66 – long-term target $93 (end-of-2027)

Great insights. Thank you! What do you think about APP, before the TTD sell off APP was much cheaper and grew faster than TTD. Don't you think it's a more attractive investment?
Even if the valuation remains frothy, the historical chart is very predictable and fairly volatile making a buy on the dip very tempting. Especially if this is a medium to long-term play in a portfolio.