

My Investment Thesis
Healthcare’s long-term appeal as an investment domain rests on a rare combination of inevitability and scale. Unlike most industries, demand for healthcare does not need to be created, stimulated, or reinvented; it emerges naturally from demographics, biology, and rising living standards. As populations age, chronic diseases become more prevalent, and emerging markets converge toward developed-world healthcare spending levels, global demand continues to grow in a way that is both persistent and largely indifferent to economic cycles.
It’s these key characteristics that make healthcare and pharma two of my favorite industries to invest in.
Meanwhile, healthcare spending is increasingly shifting from volume to complexity. Modern medicine is no longer centered around relatively simple, mass-market pharmaceuticals. Instead, the industry is moving toward biologics, precision therapies, and highly specialized treatments that require deeper scientific understanding, tighter quality controls, and far more sophisticated development and manufacturing processes. Each step forward in therapeutic innovation raises the technical and regulatory bar for everyone involved.
This evolution has important implications for where value is created. While pharmaceutical companies still capture the headlines, the economics of drug development have become more challenging. R&D costs continue to rise, timelines are long and uncertain, and outcomes are inherently binary. Patent cliffs, pricing pressure, and political scrutiny further complicate the investment case for pharma giants, and this, combined with the complexity of the matter, has always stopped me from investing.
To me, the infrastructure supporting healthcare innovation looks much more compelling, and the more so as healthcare innovation accelerates and becomes increasingly complex. Every new therapeutic modality, every tighter regulatory requirement, and every increase in scientific rigor deepens the industry’s reliance on advanced tools, consumables, data, and outsourced capabilities.
The more complex medicine becomes, the more indispensable the underlying ecosystem becomes, and the more durable the economics of the companies that enable it.
This structural shift has quietly concentrated power in the hands of a few indispensable enablers. Despite being highly fragmented on the surface, life sciences/pharma tools and services are effectively dominated by a small number of large operators. Thermo Fisher Scientific, together with Danaher, forms a de facto duopoly that captures roughly a third of the global market, an extraordinary position in an industry with thousands of smaller competitors.
Thermo Fisher alone commands roughly 15% of the total life sciences market, a level of share that speaks not just to scale, but to deep institutional trust built over decades.
This is the company to focus on when you want to gain portfolio exposure to healthcare and pharma – it’s the premium pick that is underdiscussed.
What makes its position so valuable is not simply size, but where Thermo Fisher sits in the pharmaceutical value chain. Rather than facing consumer demand cycles, patent cliffs, or binary drug outcomes, Thermo Fisher embeds itself throughout the entire drug development lifecycle, from discovery and analytical validation to clinical trials and commercial manufacturing.
Once its instruments are specified in a drug’s development or production process (and in its technologically leading position, it is often the first and best choice), regulatory requirements effectively lock them in. Switching is not just expensive; it is often impractical and impossible. In this industry, regulatory oversight doesn’t erode moats; it reinforces them.
This embeddedness is further amplified by Thermo Fisher’s closed-system model. While the company sells world-class instruments, the majority of its economic value is generated after the initial sale. Those instruments require a continuous stream of proprietary consumables, including reagents, filters, pipette tips, and chemicals, which are used daily and replaced constantly. As a result, only a small portion of Thermo Fisher’s revenue comes from equipment, while the vast majority is recurring, high-margin, and contract-based.
Each instrument sale effectively secures 5-12 years of predictable follow-on revenue, as instruments are instrument-specific and qualified within validated workflows, meaning customers cannot easily substitute third-party alternatives without revalidation, additional risk, or regulatory scrutiny.
The result is that each piece of installed equipment functions as a long-duration annuity, and a business model that allows investors to benefit from the compounding growth of healthcare and pharmaceutical innovation without taking on the traditional risks of investing in drug developers themselves. Thermo Fisher does not need to guess which therapies will succeed. It simply needs more science, more drugs developed, and more regulation followed; trends that are all moving in one direction.
This is what makes Thermo Fisher such a rare asset in healthcare: a dominant, deeply entrenched platform business with exceptional visibility, structural pricing power, and resilience across economic cycles. And it is precisely this reliability that underpins management’s confidence in sustained high-single-digit revenue growth and mid-teens earnings compounding well into the next decade.
This is one of those unique businesses you can buy today and forget about for the next 10 years, as its dominant market position, impenetrable moat, and strong secular drivers ensure it will continue to compound.
Welcome to InvestInsights — an independent equity research publication rooted in long-term, buy-and-hold investing, publishing actionable stock/equity research reports weekly!
📈 You’re reading my latest exclusive stock analysis. If you like this analysis, make sure to like & subscribe to receive much more like this!
If you’d like full access to this post and all my other exclusive analysis & portfolio access (16% CAGR since 2022), consider becoming a paid subscriber!
Performance & Financial Review
With my overarching thesis reestablished, let’s take a closer look at how this business is performing and its financials.
Thermo Fisher released its latest financial results back in mid-October and delivered excellent results, surpassing consensus estimates on both the top and bottom lines and raising FY25 guidance. Indeed, this was a remarkable beat-and-raise quarter for TMO, driven by improving demand and headwinds proving less severe than anticipated.
First of all, expectations coming into the year were tempered (and remained so through H1) due to poor industry dynamics, including biopharma funding pressure, customer destocking, and post-COVID digestion, which still poses a headwind as TMO laps previous quarters with higher COVID-related revenue that is gradually disappearing.
This caution was reinforced by political uncertainty in the U.S., where early policy actions under the new administration, such as proposed Medicaid cuts and temporary halts to scientific funding, led customers to adopt a more cautious, wait-and-see stance.
Yet, especially in Q3, these headwinds have been easing faster than expected, with demand strong and Trump’s early-2025 actions either overturned or not impacting demand as much as expected. Additionally, expected tariff headwinds related to costs (especially with China) are proving much less impactful than expected, and TMO saw higher contributions from acquisitions and lower FX headwinds, creating a more favorable revenue and margin mix and driving outperformance.
The result was a Q3 comfortably exceeding the midpoint of management’s guidance on top and bottom lines.
TMO reported a total Q3 revenue of $11.12 billion, up 5% YoY and surpassing consensus estimates by a sizeable $210 million and the midpoint of guidance by $300 million, which is a further acceleration in growth compared to prior quarters, as demand momentum continues to improve and the headwind from the runoff in covid-related revenues (which is what pressured growth from 2023 onward) is easing.
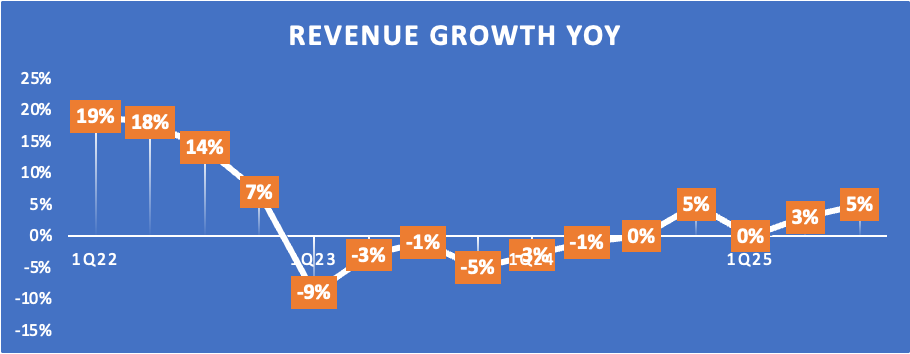
Breaking it down further, this 5% growth includes 3% organic revenue growth (held back by a 1 percentage point COVID-related headwind), a 1% contribution from acquisitions, and a 1% tailwind from foreign exchange. All three were better anticipated.
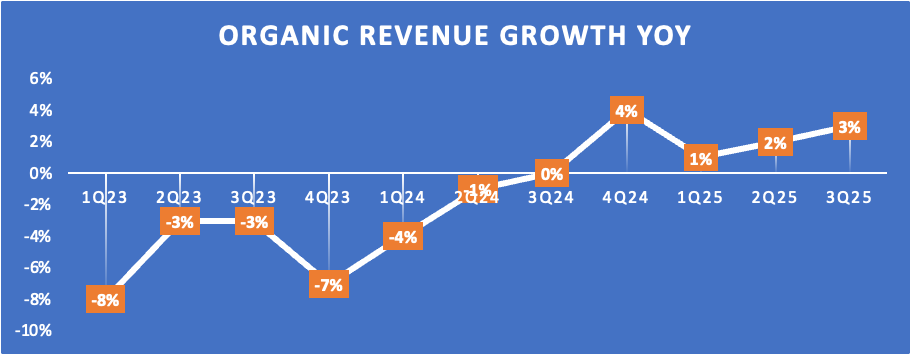
As highlighted above, organic revenue growth has been improving meaningfully in recent quarters and is now firmly positive again, as the COVID-19 headwind has largely faded. COVID-related revenue declined from roughly 25% of total revenue in 2021 to almost zero today, creating a multi-year drag on reported growth. With this now largely behind it, organic growth should normalize toward its historical mid-single-digit range in the coming quarters.
Organic revenue in Q3 was also better-than-expected, thanks to improving demand dynamics. This was driven mainly by strong growth in the pharma and biotech end market, growing mid-single digits. Since this customer base accounts for 60% of revenue, it more than offsets weaker growth in academic and government (which accounts for only 8% of revenue), where revenue fell in the low single digits. This was a modest improvement from the prior quarter, but weakness remained notable, driven by government spending cuts and lower academic budgets due to government funding trims.
Diagnostic and healthcare were also down in the single digits in Q3, but improved notably from Q2. This segment faces higher exposure to China and includes COVID-related headwinds. This was better than I expected, though.
Breaking down revenue by region, it is encouraging to see that momentum in the U.S., Europe, and Asia Pacific remains strong, with all regions growing at low-to-mid single digits. However, China remains a drag, with revenue declining mid-single digits YoY.
This China weakness is largely industry-wide rather than company-specific and reflects a combination of subdued domestic biopharma funding, reduced government-backed research spending, and a more cautious capital allocation environment amid heightened geopolitical and regulatory uncertainty and high tariffs. Importantly, demand in regulated, mission-critical workflows remains relatively resilient, but discretionary research and instrument purchases have been deferred, weighing on overall growth in the region and, therefore, TMO’s performance in the country.
I expect this to remain a headwind in the coming quarters. Positively, China is only a single-digit percentage of revenue, so the impact is very manageable.
Finally, I want to quickly highlight M&A, which remains key to the TMO strategy and thesis. You see, TMO has consistently used acquisitions as a strategic engine to expand capabilities, enter new high-growth adjacencies, and deepen end-to-end coverage across the life sciences and biopharma value chain – a strategy that works extremely well in a highly complex, fragmented market with high barriers to entry. This is why it has completed 25+ acquisitions from 2003–2025, totaling ~$68B in disclosed value, and is committed to continued M&A activity.
In Q3, TMO completed the acquisition of Solventum’s Filtration & Separation business, expanding its bioprocessing offering for pharma and biotech while also strengthening its industrial filtration capabilities. The integration is progressing smoothly, with early customer feedback reported as very positive.
In parallel, the company acquired Sanofi’s sterile fill-finish site in Ridgefield, New Jersey, further reinforcing its U.S. drug product manufacturing footprint. This addition not only expands an already industry-leading sterile fill-finish network but also positions Thermo Fisher to benefit from the ongoing re-shoring of pharmaceutical manufacturing as customers seek greater supply-chain resilience.
These are compelling strategic moves!
Furthermore, TMO announced the acquisition of Clario, underscoring the strategic nature of Thermo Fisher’s M&A agenda. Clario adds a differentiated clinical trial data and digital endpoint platform that spans every phase of drug development and has supported roughly 70% of FDA drug approvals over the past decade. For 2025, the business is expected to generate approximately $1.25 billion in revenue and grow at a high-single-digit rate under Thermo Fisher’s ownership. Importantly, the transaction is expected to be immediately accretive to margins and add roughly $0.45 to adjusted EPS in the first year after close, with management targeting around $175 million of adjusted operating income from synergies by year five.
Taken together, these transactions highlight Thermo Fisher’s disciplined capital deployment approach, balancing strategic M&A with shareholder returns, as evidenced by $3 billion in share repurchases year to date and a newly announced $5 billion authorization.
More importantly, they reinforce why M&A remains such a powerful lever for TMO: acquisitions are not pursued for growth alone, but to deepen customer relationships, extend regulatory and operational moats, and strengthen a platform that becomes more valuable as healthcare and drug development grow more complex.
On that note, let’s jump to the bottom-line performance.
In Q3, TMO delivered an adjusted operating income of $2.59 billion, up 9% YoY and reflecting a 23.3% operating margin, up an impressive 100 bps YoY and comfortably beating expectations.
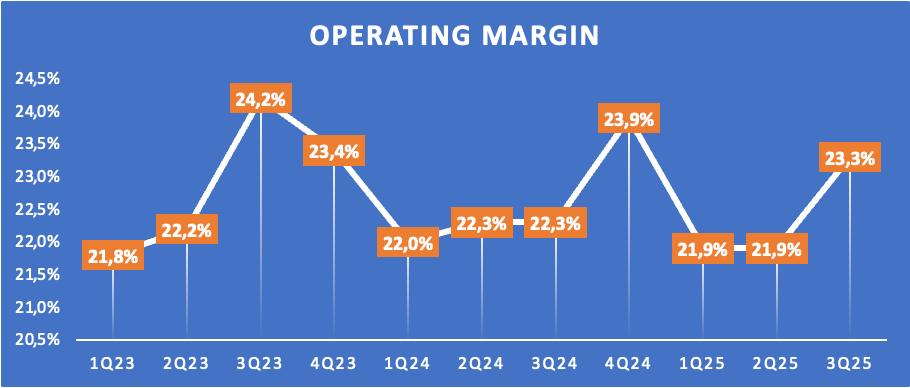
These strong results were driven by tight cost control, a slightly higher gross margin (41.9%, up 10 bps), and decent productivity gains, which combined to offset the headwinds from tariffs, FX, and an unfavorable mix.
Further down the line, this resulted in a quarterly EPS of $5.79, up 10% YoY. This includes $113 million in interest expense, an 11% tax rate as expected, and a 5 million lower share count, driven by repurchases.
Crucially, this surpassed consensus estimates by $0.29 and guidance by $0.30. This upside was driven by the impact of tariffs, which proved less impactful than expected, adding $0.11 to guidance. On top of that, the top-line outperformance fueled another $0.20, partially offset by $0.01 in dilution from acquisitions.
Finally, cash flows were also excellent. TMO has generated a YTD FCF of $3.3 billion after $1 billion in capex. This includes close to $2 billion in FCF in Q3, at a 17% FCF margin.
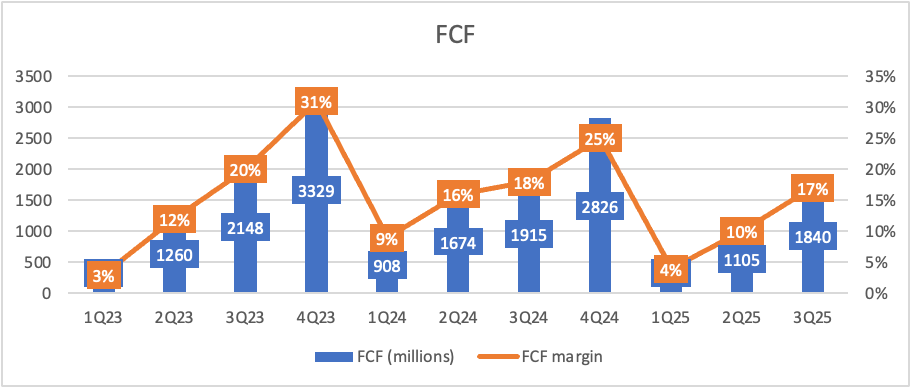
TMO consistently generates substantial FCF annually. Over the last 5 years, FCF has been around or just over $7 billion and has grown each year, even as revenues struggled, driven by the predictable, recurring nature of core, high-margin consumables.
And management is still allocating these cash flows immediately to generate long-term value. In Q3 alone, it deployed $4 billion in capital through the acquisition of our Filtration & Separation business from Solventum, the sterile fill-finish site from Sanofi, and $1 billion in repurchases.
Yes, management often outspends FCF, leading to a leveraged balance sheet, but it has a strong track record of generating strong value from these investments. Its ROIC is consistently in the high single digits (up to 11.3% in Q3), and its ROE has been in the low teens over the last 5 years, which are excellent numbers, especially for a business that deploys most of its capital into M&A, which dilutes both numbers.
So, for once, I don’t mind this too much.
Nevertheless, the balance sheet isn’t ideal. TMO ended the quarter with $3.5 billion in cash and $35.7 billion in total debt, translating to a 2.9x net debt-to-adjusted EBITDA ratio. This is far from ideal, limiting TMO’s financial flexibility and its ability to make opportunistic acquisitions.
On a positive note, FCF is expected to grow strongly over the coming years, driven by improving revenues and margins. As this business generates $8-10 billion in FCF annually, this debt does seem manageable. Simply scaling back on acquisitions for 1-2 years would allow it to meaningfully reduce debt, and expirations shouldn’t be a problem at any time.
Therefore, I am not too concerned.
Want more out of your subscription? Even more content like this weekly? Consider InvestInsights PRO — $7.50/month ($70/annually)
PRO gets you:
A guaranteed minimum of 6-8 stock analyses every month (of which at least 3-4 are paid-exclusive).
Full insight into my own portfolio, including allocation, transactions, watchlist, and performance (16% annualized return since January 2022).
Instant transaction alerts anytime I buy or sell any shares (Fully transparent).
An overview of all my target prices and ratings (available online, updated weekly).
Access to the InvestInsights Hub, containing all of the above in a single online sheet, updated constantly!
Outlook & Valuation
Looking ahead, TMO management is optimistic, as customer demand is solid despite unfavorable government policies. Combine this sentiment with the strong Q3 beat, and the FY25 guidance raise was inevitable.
