

TSM is a key position in my portfolio and one of my highest-conviction picks for the decade ahead.
The reason is simple: TSMC has become the single most important company in the global AI supply chain. As AI infrastructure spending explodes, the limiting factor is no longer capital, software, or demand, but the availability of leading-edge chips. And today, only one company can manufacture those chips at scale.
TSM shares are at an all-time high, and it couldn’t be more deserved. The company has quietly built a near-monopoly in advanced logic manufacturing, controls more than 95% of the market at 3nm and below, and sits two to three years ahead of any meaningful competitor. That dominance is now translating into explosive growth, record profitability, and unprecedented demand visibility as hyperscalers, AI chip designers, and sovereign customers all compete for scarce capacity.
Its Q4 results removed any remaining doubt about the durability of that demand and have significantly bolstered my conviction.
In this analysis, I’ll break down TSM’s Q4 results, discuss what they reveal about the true state of the AI infrastructure boom, why the competitive gap at the leading edge continues to widen, and why, despite a 65% rally over the past year, TSM shares remain attractively priced for long-term investors!
This is my TSM Q4 update – Let’s delve in!
Welcome to InvestInsights — an independent equity research publication rooted in long-term, buy-and-hold investing, publishing actionable stock/equity research reports weekly!
📈 You’re reading my latest [FREE] stock analysis. If you like this analysis, make sure to like & subscribe to receive much more like this!
If you’d like full portfolio access (13% CAGR since 2022) & additional exclusive analyses, consider becoming a paid subscriber!
TSM delivers a remarkably strong Q4
TSM’s Q4 results, released on Thursday, were nothing short of sensational. Revenue growth was exceptional, driven by explosive, leading-edge demand; margins expanded rapidly; and cash flows reached new all-time highs, all while the company continued to take market share in the foundry industry and further strengthened its already formidable competitive position.
TSM decisively beat consensus estimates across every key metric with its Q4 results and significantly outperformed my October forecast, driven by unprecedented customer demand spurred by AI infrastructure investments. Management’s guidance for Q1 was equally upbeat, reinforcing the message that demand remains far stronger than supply, with advanced-node capacity constraints now the primary factor limiting even faster growth, and underlying business momentum only continues to strengthen.
Critically, after conversations with customers and their customers in recent months, management has become more confident in the foundation of this AI boom, enabling it to commit to faster capacity buildout and larger CapEx budgets, thereby further hiking its medium-term guidance. Notably, management now guides for a 25% revenue CAGR through the end of the decade, and it has a history of conservatism.
Really, you won’t find them any better than TSM right now – this is one of the most critical and best-positioned companies globally, and these Q4 results, its Q1 2026 guidance, and management’s additional commentary only further strengthened my conviction in TSM and its supplying partners.
With that context in mind, let’s dive into the results and put the numbers into perspective.
TSM reported a Q4 revenue of $33.7 billion, surpassing consensus estimates by $1 billion and exceeding the high end of its own guidance. This reflects YoY growth of 26%, a deceleration from 40%+ in prior quarters, but given the massive revenue base and the fact that it lapped 37% growth last year, this is still exceptional growth, mostly held back by capacity constraints.
For reference, as the company is bringing a lot of leading-edge capacity online in 2026, per management’s guidance (discussed in detail later), growth will accelerate again in Q1 and should remain over 30% YoY for most of 2026, so momentum remains strong, but quarterly growth can fluctuate. It is important to keep that in mind.
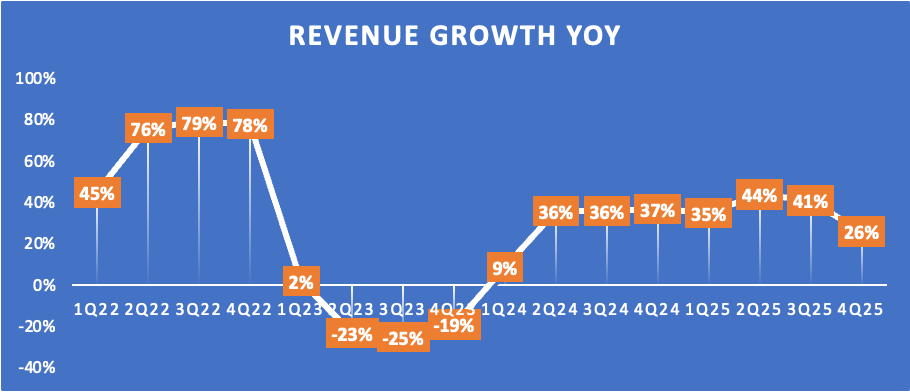
Ultimately, this brought FY25 revenue to $122 billion, up 36% YoY, supported by AI-related demand but also by non-AI markets bottoming and showing a mild recovery so far. For reference, AI-related revenue accounted for high teens percent of revenue in 2025.
More importantly, TSM once again far outpaced the broader foundry industry, which grew by 16% in 2025, suggesting TSM outperformed the market by a staggering 20 percentage points, which is extraordinary given the company’s existing scale, the size of the market, and the fact that it already dominates it.
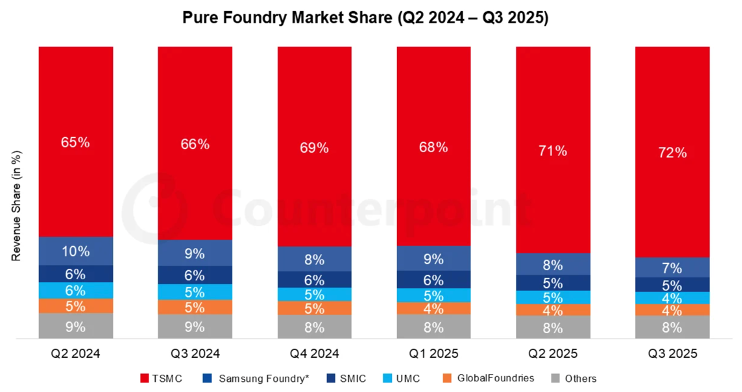
For reference, in early 2024, TSM captured 63% of the foundry market, already making it a dominant force. Yet since then, it has far outperformed the market, leading to impressive market share gains; as of Q3 2025, the company commands a 72% market share. That is a 9-percentage-point gain in market share in an industry worth almost $150 billion.
What is driving this outperformance? That is TSM’s specific dominance in cutting-edge nodes, specifically 3nm and below, where its market share exceeds 95%. In other words, TSM practically operates a monopoly in advanced node manufacturing.
No other foundry (not Samsung, not Intel) comes close in terms of manufacturing precision, yield, or scalability. You see, manufacturing complexity shouldn’t be underestimated, and TSM has built a structural lead that data increasingly suggests amounts to nearly two full process generations (or roughly two to three years) ahead of the competition. This advantage is not theoretical: it shows up in consistently higher yields, faster volume ramps, and the ability to support the largest, most demanding customers at scale, something rivals continue to struggle with.
When it comes to nodes 3nm and below, there is simply no competitor that can match TSM in terms of node performance or output. And these are the nodes used for the most advanced AI/datacenter GPUs and CPUs, which are in incredibly high demand.
As a result, TSM is capturing a disproportionate share of the fastest-growing segment of semiconductor demand, with advanced-node volumes expanding far more rapidly than the broader market. This structural positioning, being effectively the sole scalable supplier at the leading edge, underpins TSM’s sustained growth outperformance and explains why its revenue trajectory continues to diverge from that of the rest of the foundry industry.
Importantly, given the depth of TSM’s manufacturing moat, its multi-year technology lead, and the sheer capital and execution required to compete at the leading edge, this dynamic is unlikely to change in any meaningful way over the coming years. As a result, I expect TSM to remain in a league of its own for years to come, and its monopoly position in leading-edge nodes to allow it to keep far outperforming the industry and fully benefit from AI infrastructure investments.
So, TSM is practically the sole supplier of the computing chips needed for AI infrastructure, whether they’re Nvidia, AMD, or Broadcom chips. This fuels exceptional growth today, held back by capacity constraints, and as you can imagine, this fuels a brilliant outlook, especially as infrastructure investments continue to be revised upward and seem sustainable for years to come.
On that note, let’s first move to the P&L, where TSM’s results are similarly impressive.
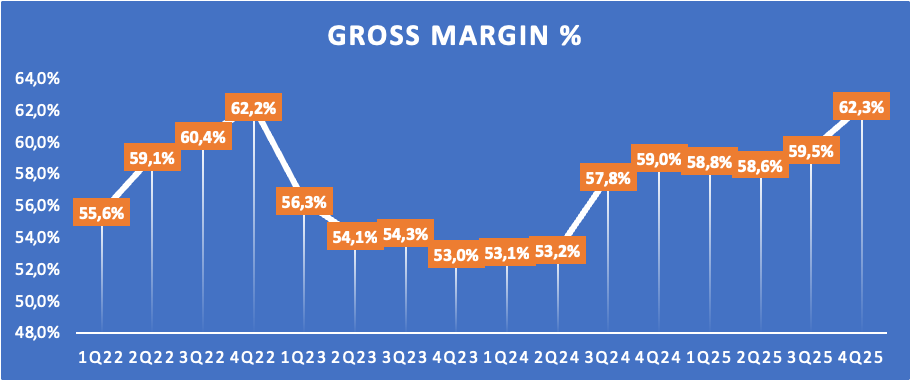
TSM reported a Q4 gross margin of 62.3%, a quarterly all-time high and exceeding the high end of management’s guidance by 130 bps. This expanded by 280 bps sequentially and 330 bps YoY, fueled by cost improvement efforts, a favorable FX, and improved capacity utilization, especially in mature nodes.
In practice, recent growth is leading to much-improved operating leverage, with the cost per node dropping, helped by a shift toward higher-end, higher-priced nodes. For reference, advanced nodes accounted for 74% of revenue in 2025, up from 69% in 2024.
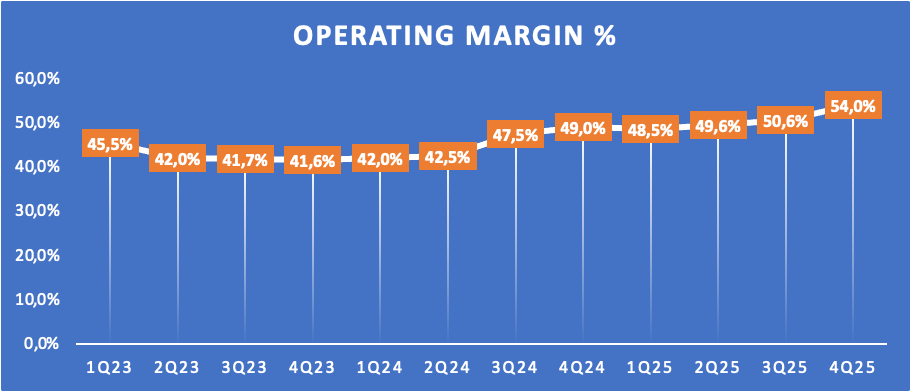
Moving further down the line, operating expenses grew much more slowly than revenue, despite considerable R&D investments. This resulted in strong operating leverage improvements, with operating expenses accounting for just 8.4% of revenue, down 50 bps sequentially.
This, combined with the healthy gross margin improvement, fueled a 340 bps sequential operating margin gain and a 500 bps YoY improvement to an all-time high of 54%. While TSM’s gross margin is held down by high physical costs of revenue, TSM has no marketing costs and operates highly efficiently, which allows for an exceptionally strong operating margin.
This led to a Q4 EPS of $3.14, beating consensus estimates by $0.16.
That then brings us to cash flows, and this is where TSM really shines.
You see, one of the factors that impresses me the most and fuels confidence when it comes to TSM is actually not defined by numbers but by behavior.
One of the most underappreciated strengths of TSM is just how relentlessly mission-focused its management team is. TSM is not run like a typical technology company chasing optionality or near-term optics; it is run like critical infrastructure, with an almost singular focus on execution, reliability, and long-term return on capital.
Headcount growth is tightly controlled, layers of management are limited, and decision-making remains highly centralized around manufacturing excellence. There is little evidence of empire-building, excessive overhead, or strategic drift. Every part of the organization is oriented around one objective: advancing process technology at scale, on time, and with high yields.
This discipline is most visible in how TSM approaches capital spending. While headline CapEx numbers can look enormous, the underlying philosophy is notably conservative. Capacity is added in response to clear, long-duration demand signals from customers, often backed by multi-year commitments, rather than speculative forecasts. Management has repeatedly emphasized utilization, learning curves, and return thresholds when discussing new fabs, and history shows a willingness to slow or defer spending when demand visibility weakens. In other words, CapEx is treated as a strategic weapon, not a growth-at-any-cost lever.
Take last year. At multiple points, analysts were surprised by TSM’s capex discipline amid explosive demand and capacity shortage. Even customers like Nvidia and Apple are starting to push for capacity investments, but TSM kept Capex under control in 2025.
Why? Because management isn’t in the business of chasing hype. TSM only starts ramping up investments once it is convinced demand will remain, to avoid overcapacity. That is remarkable to me – the sheer thoughtfulness and mission focus on delivering the best returns.
TSM does not chase market share for its own sake. It prioritizes technological leadership and manufacturability over volume expansion in less profitable or less defensible segments. This restraint has allowed the company to compound its advantages over time, as competitors stretched themselves thin trying to keep up across too many nodes or business models simultaneously.
TSM’s dominance isn’t an accident; it’s driven by brilliant execution.
In an industry where execution mistakes are brutally expensive, and technology gaps can persist for years, TSM’s operational focus, capital discipline, and cultural consistency form a moat that is extremely difficult to replicate, and one that continues to widen as complexity at the leading edge increases.
While we investors tend to focus on numbers, I view this as one of the most important factors in the TSM investment thesis.
Anyway, back to the cash flows themselves, TSM reported $23 billion in cash from operations, and spend $11.5 billion on Capex in Q4.
This is a big part of its moat. TSM has spent $167 billion on capex and $30 billion on R&D in the last 5 years alone, a level of sustained investment that no competitor can realistically match without a comparable customer base, utilization, and balance sheet. Even the largest rivals lack the volume, learning curve, and demand visibility required to deploy capital at this scale efficiently, making catch-up not just expensive but structurally uneconomic.
And despite these significant Capex investments, TSM is a FCF machine. It generated $12.5 billion in FCF in Q4, and 2025 FCF totaled roughly $31 billion at a 25% FCF margin.
That is just impossible to compete with.
As a result of these excellent cash flows, TSM maintains a pristine balance sheet. Roughly $9 billion of these Q4 cash flows flowed directly to the balance sheet, leaving TSM with a whopping $98 billion in cash and just $34 billion in debt.
This allowed TSM to raise its 2025 dividend by 29% and increase it by another 20% in Q4. As a result, shares now yield 1%, and this is still based on a FCF payout ratio well below 50%.
Finally, TSM reported a Q4 ROE of 38.8% and a 2025 ROE of 35.4%, up 510 bps YoY, which are sublime reinvestment numbers.
As I said, you don’t find them much better out there.
A manufacturing footprint update
Before we jump to the outlook, which I will discuss in detail, let’s first take a look at TSM’s manufacturing footprint and technology updates.
Most importantly, TSM remains strongly committed to overseas expansion to diversify its geographical footprint away from its historical focus on Taiwan and to better meet customer needs. Increasingly, customers such as Nvidia, AMD, Apple, and Broadcom are de-risking their supply chains, leading to a preference for U.S. manufacturing. That is exactly why TSM is heavily investing in U.S. capacity, in addition to investments in Japan and Europe.
Starting with the U.S., TSM has stated a commitment to accelerating capacity expansion in Arizona, where it is building a gigafab that should eventually account for 30% of global advanced-node capacity.
Execution here is progressing well, with the first facility entering high-volume production back in Q4 2024 and the second facility nearly complete and on pace to start high-volume production in the second half of 2027, earlier than expected, as TSM sees very strong customer demand.
Construction on the third facility has also started, and it is applying for permits for the construction of a fourth and a fifth. Finally, TSM is hinting at further growth following its previous commitment to invest $165 billion in Arizona, amid extreme leading-edge demand.
Ultimately, I wouldn’t be surprised if the Arizona gigafab accounted for over 50% of advanced node capacity over time, which isn’t a bad thing, given the decrease in geopolitical risk and stronger customer relations. At the same time, long-term margins in these fabs remain a question mark, though TSM believes it will be able to operate at margins similar to those of its Taiwan facilities over time.
In Japan, the company is also receiving significant government support. Its first fab has been operational since late 2024, and construction on a second one has started. Additionally, in Europe, the construction of a specialty fab in Dresden, Germany, is progressing well. The ramp in both Japan and Europe will depend on customer needs and market conditions.
Finally, the company remains very much committed to Taiwan. While it is diversifying, TSM is not planning to move away from Taiwan, which will remain its manufacturing center, accounting for the vast majority of capacity. It is currently preparing to build 2nm fabs at both the Hsinchu and Kaohsiung Science Parks, and it will continue to invest in leading-edge and advanced packaging facilities in Taiwan over the next few years.
Moving to a quick note on technology, 2nm nodes successfully entered high-volume manufacturing in 4Q 2025, with good yields. Management expects this to ramp rapidly in 2026, driven by strong demand for smartphones and AI. Meanwhile, the next-generation N2P node is on track for volume production in the second half of 2026.
For reference, N2 or 2nm delivers a power benefit of 10-15% at the same power or a 20% to 30% power improvement at the same speed, and a more than 15% chip density increase over the latest and most advanced 3nm node. This makes it perfect for AI and high-end smartphones.
Meanwhile, TSM is the first to enter high-volume 2nm production. Samsung has also started integrating in-house 2nm nodes into its devices, but its yield is nowhere near TSM's. Reports last week cited that Samsung has now achieved a 60% yield on 2nm, while TSM is already at 90%. Intel isn’t ready for high-volume manufacturing either, and it sees much lower node performance.
For reference, yield refers to the percentage of usable, fully functional chips produced on a wafer. At advanced nodes, even tiny defects can render a chip unusable, so higher yield directly translates into more output, faster volume ramps, and the ability to manufacture large, complex designs reliably. A jump from 60% to 90% yield is not incremental; it represents a massive difference in effective capacity, cost efficiency, and scalability.
Just as importantly, node size alone does not define real-world performance. While “2nm” or “3nm” are useful shorthand labels, actual performance depends on a combination of transistor architecture, design rules, power delivery, interconnect quality, and manufacturing maturity. A smaller node with poor yields or immature process tuning can underperform a larger, more stable node in terms of speed, power efficiency, and usable chip area. This is why TSM’s advanced nodes consistently outperform competitors in practice: its process technology is not only more advanced on paper, but also far more refined in high-volume production.
When looking at actual performance, TSM’s 3nm node outperforms both Intel’s and Samsung’s 2nm node, according to reports. This is why, while they all work on 2nm, in reality TSM is still years ahead, which is why it captures over 95% of this market.
Finally, TSM is also on track to start volume production for its A16 node in the second half of 2026, ahead of schedule. This node will provide an additional 8% to 10% speed improvement at the same power, or 15% to 20% power improvement at the same speed, along with an additional 7% to 10% chip density gain over N2. This makes it even better suited to specific HPC products with complex signal routing and a dense power-delivery network.
This commentary suggests that TSM continues to strengthen its technological leadership, with no risk of competitors catching up.
Want more out of your subscription? Even more content like this weekly? Consider InvestInsights PRO — $9.50/month ($95/annually)
PRO gets you:
A guaranteed minimum of 6-8 stock analyses every month (of which at least 3-4 are paid-exclusive).
Full insight into my own portfolio, including allocation, transactions, watchlist, and performance (13% annualized return since January 2022).
Instant transaction alerts anytime I buy or sell any shares (Fully transparent).
An overview of all my target prices and ratings (available online, updated weekly).
Access to the InvestInsights Hub, containing all of the above in a single online sheet, updated constantly!
Outlook & Valuation
As always, let’s start with guidance.
Management remains very optimistic. It expects growth to be supported by continued demand for leading-edge nodes and to remain constrained by capacity. Based on current demand indications, TSM now guides Q1 revenue to be between $34.6 billion and $35.8 billion, up 38% at the midpoint, a considerable acceleration from Q4 and much more in line with prior quarters amid very strong momentum.
Furthermore, it expects gross margin of between 63% and 65%, up another 170 bps sequentially at the midpoint, driven by continued cost improvement efforts, including productivity gains and a higher overall capacity utilization rate, partially offset by continued dilution from overseas expansion. Meanwhile, this gross margin improvement should allow an operating margin of 54% to 56%.
Looking ahead to the full year, management expects the foundry industry to deliver another strong year, likely growing by roughly 14%, supported by robust AI-related demand. However, TSM expects it will continue to far outpace the industry.
It now guides FY26 revenue growth of close to 30%, which is sensational given its size. Additionally, that is miles ahead of the 22% growth I forecasted for 2026 back in October, when I was already more bullish than most Wall Street analysts. And yet far too cautious, with AI-related demand far stronger than anticipated.
And management tends to be cautious, generally raising guidance throughout the year, so assuming growth to exceed 30% seems realistic.
As for margins, the picture is more mixed, mainly due to overseas expansion and the ramping of new technologies. While management expects overall utilization to moderately increase in 2026, the 3nm margins are expected to exceed the corporate average, and it will continue to improve its cost profile, overseas expansion will likely offset these tailwinds.
You see, overseas fab costs are much higher in the initial stages. As this capacity grows, it will dilute the gross margin. Management expects this to be a 2-3 percentage point headwind in the early stages, widening to 3-4% later on. On top of this, the ramp of 2nm technology will be an additional headwind of between 2 and 3 percentage points, so I expect the gross margin to weaken in H2 and possibly in the following years.
Nevertheless, in the long term, management is confident it can maintain a gross margin of 56% through the cycles, driven by pricing, cost improvements, manufacturing excellence, and capacity optimization. And management continues to aim for a high-20% ROE through the cycles.
TSM is also significantly raising its Capex budget for 2026, following a greater confidence in the viability and duration of this AI-driven demand explosion, which management sees as structural and multi-year. TSM now expects its capital budget to be between $52 billion and $56 billion in 2026, up significantly from $41 billion in 2025 and $30 billion in 2024. About 70% to 80% of the 2026 budget will be allocated to advanced process technologies.
Over the coming years, we should likely count on Capex to keep growing fairly strongly, as Capex per wafer increases with each technology due to the advanced equipment required. While Capex totaled $101 billion over the last 3 years, management indicates it will be “significantly higher” over the next 3 years.
Even being conservative, Capex approaching $200 billion over the next three years seems likely. However, the positive today is that TSM’s engagement lead time with customers is now at least 2 to 3 years in advance. In other words, customer capacity commitments stretch much further than they did previously, so TSM knows exactly what demand will look like three years in advance, allowing it to plan capacity investments much more effectively without the risk of over-capacity.
So the foundation for these investments is reliable.
Regarding longer-term revenue growth, management said recent developments in the AI market remain very positive. Model adoption is strong, driving a need for greater computational power and robust demand for leading-edge silicon.
There is no longer any doubt that the AI revolution and the accompanying demand boom are real. Hyperscalers are committing hundreds of billions of dollars per year to expand computing capacity, Big Tech is planning AI infrastructure measured in tens (and increasingly hundreds) of gigawatts, and multi-year, multi-billion-dollar contracts are being signed across the entire AI supply chain. From sovereign compute initiatives to enterprise inference moving into production, demand is no longer experimental or cyclical, but structural and here to stay, and increasingly constrained by the availability of leading-edge silicon.
Thus, TSM’s conviction in the multi-year AI megatrend remains strong, growing even stronger. Based on its current framework, it is even raising its forecast. It now expects AI-related revenue to grow at a mid-50% CAGR over the next 5 years, leading to a total revenue CAGR of 25% through 2029. Management suggested that this is still fairly conservative.
That is a mighty outlook, up from a previous mid-40s and 20%.
And let’s not forget that this is likely the best indicator of true AI momentum. This is the company with the broadest and clearest view on demand, in contact with all semiconductor giants and their hyperscalers customers. This guidance means AI momentum is real and here to stay.
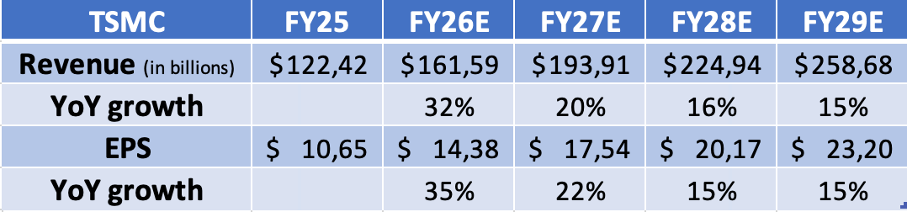
Finally, let me jump to my updated forecasts. Clearly, I was far too conservative previously, so I am raising my medium-term forecast materially for both revenue and earnings.
For starters, I have raised my 2026 revenue estimate by over $10 billion, following a strong end of 2025 and brilliant momentum entering 2026. Management is likely slightly conservative with its guidance, so a low-thirties growth rate seems most likely, especially with 3nm and 2nm capacity coming online in 2026. Meanwhile, I have also raised my EPS estimate, still pointing to mild margin expansion in 2026 despite gross margin headwinds. The primary reason is that I expect cost improvements, operating leverage, and a favorable mix to offset headwinds from overseas expansion and the 2nm ramp. This should allow EPS growth to outpace revenue at a mid-30s rate.
Looking ahead, expectations are for AI momentum to persist, and management is likely to experience rapid capacity growth through higher capex, leaving room for continued strong growth. I do expect growth to slow materially in 2027 and beyond due to the rule of large numbers, but this still reflects very strong AI-related demand and is considerably better than I previously expected.
Meanwhile, margin pressure should intensify in the 2027-2029 period, and as growth slows, I expect margins to moderate a bit from 2028 onward, especially as overseas headwinds intensify.
All things considered, I have updated my financial forecasts, as visualized in the graph below.
That then brings me to valuation, and while TSM shares are up 65% over the last 12 months, the fact that financial projections have grown similarly strongly means shares still appear fairly cheap. In other words, the run-up in share price is entirely justified. At a current share price of $345, TSM shares now trade at:
24x this year’s earnings, a 7% discount to the sector median.
A PEG of 1.4x, an 18% discount to the sector median.
TSM trading at a discount to the sector median is difficult to justify. This is one of the most critical, fastest-growing, and most strategically dominant companies in the semiconductor industry, with an unparalleled moat and unmatched visibility into long-term demand. It is, quite simply, one of the highest-quality and most reliable businesses in the entire sector, yet it trades at a discount to lower-quality, more cyclical, and structurally weaker peers.
The most common explanation for this valuation gap is geopolitical risk, and while it should not be dismissed outright, I believe it is increasingly overstated. First, a Chinese invasion of Taiwan would represent an economic catastrophe not just for Taiwan, but for China itself and the global economy, making it highly unlikely. Second, TSM is no longer a Taiwan-only manufacturing story. Its accelerating expansion in the U.S., Japan, and Europe materially reduces single-geography risk and should, over time, justify a narrowing of the geopolitical discount.
At roughly 24x earnings, investors are effectively paying a market-level multiple for a company guiding to a 25% revenue CAGR through 2029, operating at the technological frontier of the AI infrastructure build-out, and compounding its competitive advantages with every new node. That valuation simply does not align with the quality, growth profile, and durability of the business.
What this tells me is that the market continues to underappreciate the strength of TSM’s moat and the sustainability of its growth, or, at the very least, that the magnitude of the recent earnings beat and the raised medium-term guidance are not yet fully reflected in the share price. As those realities become harder to ignore, I believe the current valuation gap is far more likely to close than persist.
At this price, TSM remains compelling for long-term investors.
For reference, even assuming a still highly discounted 2028 exit (earnings) multiple of 25x, I calculate an end-of-2028 target price of $504. At a current share price of $345, this suggests an annualized return of 15% (including dividends).
Even being conservative, today’s potential returns are excellent, enough to beat global benchmarks. And there is a lot of room for shares to reprice higher as the market acknowledges the quality of this business, the geopolitical discount lessens, and TSM continues to beat my conservative forecasts.
In other words, TSM shares still represent good value. I would say fair value is right around the $350 mark today, and at any price below that, accumulating makes sense.
Rating: Buy - Accumulate below $350
FY27 Target Price: $504
Implied CAGR from the current price: 15%
Please leave a like if you enjoyed this post and found it valuable!

Thanks for yet another excellent, well grounded report! Here’s my question: the AI advances have not changed human nature so at some point - I don’t believe we are there yet - we are likely to overbuild, overinvest in AI. TSMC will be one company people look to for a signal that we are in bubble territory. What will you be watching at TSMC for that signal?
Thank you. Excellent work as always.