

Let me just start this quarterly update on TSMC by saying that the company last week delivered another whopper of an earnings report, even as Wall Street showed it little love post-earnings, which can be attributed solely to the fact that a lot of optimism had already been priced in in recent weeks.
For reference, TSM shares have gained 30% since the start of September, yet its earnings multiple has only expanded by 14%. Why? Well, the big price jump hasn’t come out of nowhere; recent developments have led to a significant outlook hike for TSMC, which has a lot going in its favor right now. And I believe there is much more upside still to come.
In recent weeks, we have seen many announcements of massive multi-year cloud and custom silicon deals from hyperscalers and AI leaders such as OpenAI, Microsoft, Google, Amazon, Broadcom, and Oracle, some worth tens or even hundreds of billions of dollars. These reinforced that the AI investment boom is not a short-lived trend but a durable, long-term growth driver for TSMC, justifying outlook raises by Wall Street analysts.
Add to that an improving and resilient U.S. economy that continues to fuel enterprise and infrastructure spending, Intel’s renewed reliance on TSMC for its most advanced chips, ongoing signs of robust AI-driven semiconductor demand, and clearer visibility into a multi-year expansion cycle, and it’s easy to see why investors have turned increasingly bullish.
As a result, shares have gained roughly 30% since the start of September, reflecting a broader re-rating of the company as the most critical enabler of the global AI and advanced computing ecosystem.
You see, TSMC is unrivaled in leading-edge chip manufacturing. The company doesn’t just participate in the semiconductor supply chain, but it defines it.
TSMC produces more than half of all chips globally, claiming a 71% foundry market share as of Q2 2025. Even more impressively, the company is growing its market share at a rapid clip. In just 1.5 years, TSMC has grown its foundry market share from 63% in Q1 2024 to 71% today — an absolutely insane feat given the size of this industry.
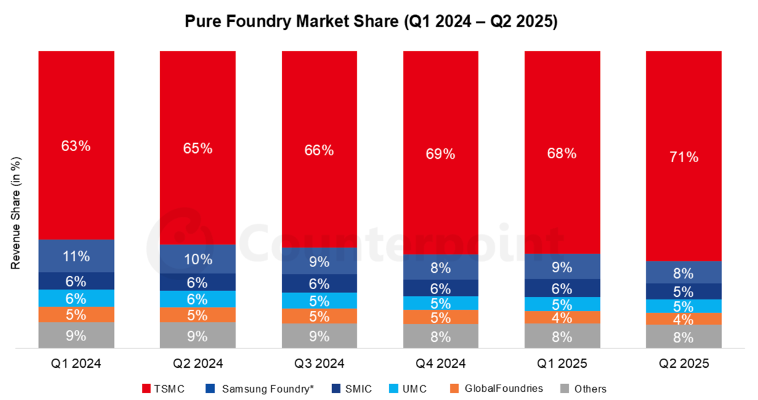
TSMC is an absolute force in global foundry and simply unequaled, with no company even coming close to it. These market share gains reflect its unmatched execution, technological leadership, and customer trust, where it continues to pull ahead.
This is best reflected in advanced nodes, where its market share soars above 95%. No other foundry (not Samsung, not Intel) comes close in terms of manufacturing precision, yield, or scalability. As a result, TSMC is practically the sole manufacturer of nodes 3nm and below, the nodes used for the most advanced AI/datacenter GPUs and CPUs.
This near-monopoly on leading-edge production effectively makes TSMC the indispensable partner for every major chip designer worldwide, including Nvidia, AMD, Broadcom, and Apple.
This position is reinforced by staggering scale and relentless execution. TSMC spends roughly $30–40 billion annually on capital expenditures to maintain its technological lead, while its R&D intensity ensures that each successive node delivers material gains in power efficiency and performance.
Rivals face an insurmountable barrier to catch up: even if they spend tens of billions, they lack TSMC’s process discipline, customer trust, and ecosystem maturity. The result is a structural advantage that compounds over time, allowing TSMC to operate as the de facto manufacturing backbone of the high-performance computing world, from AI accelerators and data-center processors to smartphones and automotive systems.
Each generation of technology reinforces this leadership, creating a powerful flywheel effect that allows TSMC to compound its leadership and keep growing its market share, especially now that almost every technology shift is toward these advanced nodes.
Ultimately, this dynamic has turned TSMC into the platform on which the entire AI economy is being built — the company’s strategic importance has never been more evident.
It’s hard to overstate it: TSMC has become one of the world's most essential, highest-quality businesses and one of the best positioned for sustained growth in the decade ahead.
This company has an unmatched, deeply entrenched moat; it is one of the most strategically essential companies for the next generation of computing, sitting in one of the best positions to benefit from the AI revolution. Management has already guided for a five-year revenue CAGR near 20%, underpinned by AI revenue growing at a mid-40s pace and a long-term gross margin floor around 53%. Yet management now states demand dynamics appear much better than expected, suggesting even more upside.
And yet, despite the run-up so far, I don’t think investors are too late to the party. I still see room for upside, and TSMC’s latest Q3 results reaffirmed my confidence – I still believe Wall Street is underestimating TSMC’s prospects and the investment community continues to unreasonably discount shares on hollow fears. This gives us a prime opportunity.
However, before we jump to any conclusions in this extensive intro, let’s look closely at the Q3 results to see how TSMC is performing and put its numbers into perspective, before updating my financial projections and target price.
Let’s jump right in!
Welcome to InvestInsights — an independent equity research publication rooted in long-term, buy-and-hold investing, publishing actionable stock/equity research reports weekly!
📈 You’re reading my latest exclusive stock analysis. If you like this analysis, make sure to like & subscribe to receive much more like this!
If you’d like full access to this post and all my exclusive analysis & portfolio access (14% CAGR since 2022), consider becoming a paid subscriber!
TSMC is firing on all cylinders, driven by AI-related demand.
TSMC released its Q3 2025 financial results last Thursday, October 17, and blew away both consensus estimates and my own expectations. Revenue, margins, and earnings all came in meaningfully ahead of forecasts, driven by relentless strength in high-performance computing and AI-related demand, which remains underestimated. Additionally, the company once again demonstrated its ability to convert industry-wide momentum into exceptional financial execution, delivering record profitability and underscoring its dominance at the leading edge of semiconductor manufacturing.
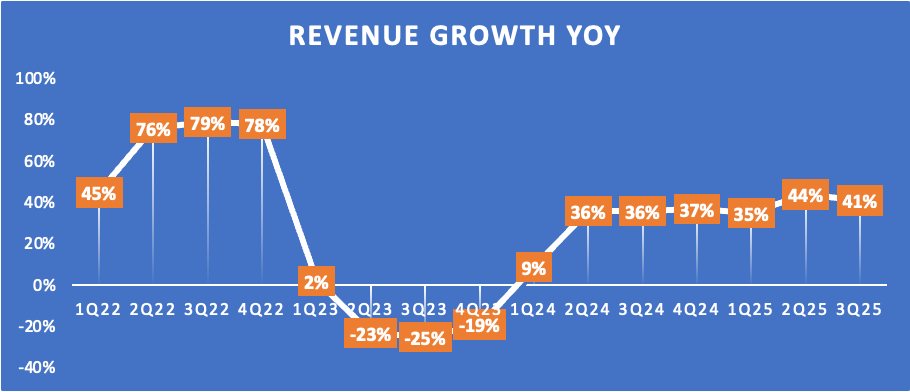
TSMC reported Q3 revenue of $33.1 billion, up 6% sequentially in local currency (which I refer to in times to better reflect organic growth, taking out currency fluctuations) and up 30% YoY. In USD, this reflected YoY growth of 41% and 10% sequentially, which is exceptional and came in ahead of management’s guidance and beat consensus estimates by $1.54 billion.
As visible below, revenue growth momentum remains strong, showing no signs of any weakness, even as TSMC lapped 36% growth in the same quarter last year, making this 41% revenue jump even more impressive.
This exceptional revenue growth and beat continue to be driven by leading-edge technologies and sublime AI-driven momentum, while we are also finally seeing a steady recovery in other end-markets. Breaking down revenue by technology, we can see that 3nm now accounts for 23% of revenue, up from 20% last year, while advanced tech, defined as 7nm and below, now accounts for 74% of revenue, up from 69% last year.
This shift highlights how TSMC’s growth is increasingly concentrated in its most advanced nodes, where pricing, margins, and strategic importance are highest. These technologies power the AI accelerators, data center CPUs, and flagship smartphone chips that drive global semiconductor innovation. The continued mix shift toward advanced nodes boosts profitability and strengthens TSMC’s long-term competitive position: it deepens customer reliance, extends the company’s technological lead, and widens the gap with peers struggling to scale similar capabilities.
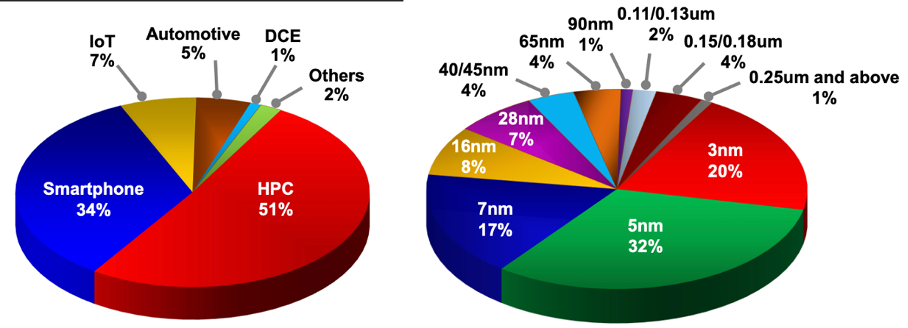
When we break down revenue by end-market, we see similar trends. HPC (high-performance computing) now accounts for 57% of revenue, up from 50% last year.
However, I am also pleased that more cyclical markets are steadily bouncing back. Smartphone revenue grew 19% sequentially in Q3 (accounting for 30% of revenue), IoT grew 20% sequentially, and automotive grew by 18% (both accounting for 5% of revenue). This shows that TSMC’s growth isn’t solely driven by AI or HPC any longer, but these markets are now also contributing after cyclical weakness in most of the last two years.
Finally, when we break down revenue by region, what stands out is that China exposure continues to drop, driven by a growing number of U.S. export restrictions for China. In Q3, China sales only accounted for 8% of revenue, down from 11% a year ago, which is a positive development. This means geopolitical risk falls.
Meanwhile, North America-based customers continue to account for the far majority of revenue at 76%, up from 71% one year earlier and 75% in Q2.
All things considered, I am really pleased with the revenue momentum TSMC has delivered. The company continues to fully benefit from excellent AI-related demand that shows no signs of slowing. Notably, the company remains constrained by 3nm capacity, as AI-driven advanced node demand remains generational. As a result, TSMC still has plenty of room to keep growing at this current rate as more capacity comes online, so I expect this momentum to persist through 2026.
TSMC is simply executing brilliantly and optimizing this AI opportunity, allowing it to keep delivering 40%+ revenue growth, which is nothing short of exceptional at this size.
On that note, let’s move to the bottom line, where its performance was similarly impressive.
TSMC reported a gross margin of 59.5%, up 90 bps sequentially and up a very solid 170 bps YoY. Notably, this exceeded the high end of management’s gross margin guidance by 200 bps, mainly due to a much more favorable exchange rate and the impact of overseas expansion proving less impactful.
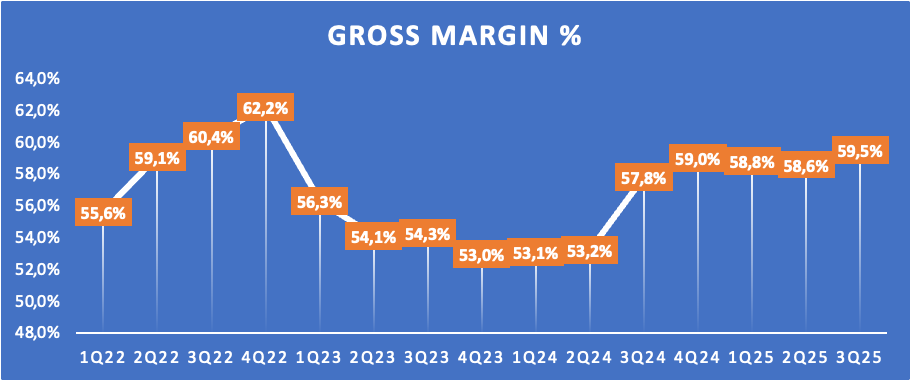
The gross margin improvement was primarily driven by cost improvement efforts and a higher capacity utilization rate. In particular, these cost improvements proved incremental, which should continue to benefit its gross margin in the coming quarters as well. These are structural cost improvements.
Now, these cost improvements were partially offset by unfavorable exchange rates and continued dilution from overseas expansion. Particularly, the latter is essential, as this headwind will persist and worsen in the coming years as TSMC ramps up foreign production. However, the upside is that the overseas expansion cost headwind proved much less significant in Q3 than previously feared, in large part due to overall scale advantages. As a result, this headwind is now expected to be “only” 2 percentage points in H2 and 100-200 bps for FY25, down from a previous 200-300 bps guide, so that is a material improvement.
In the coming years, this headwind will still grow as expansion ramps up. For the next several years, the impact is still expected to be 200-300 bps, and this should widen to 300-400 bps in the latter stages, so we should still expect quite a bit of margin delusion from these efforts. Still, TSMC management remains fairly confident in its ability to drive upside to these current expectations, which is a much more positive tone than before.
Moving further down the line, Q3 operating expenses were up 11% YoY, primarily driven by 21% growth in R&D expenses, offset by lower SG&A expenses, which were down 9% YoY, reflecting a further improvement in its cost profile. TSMC benefits from size-driven operating leverage.
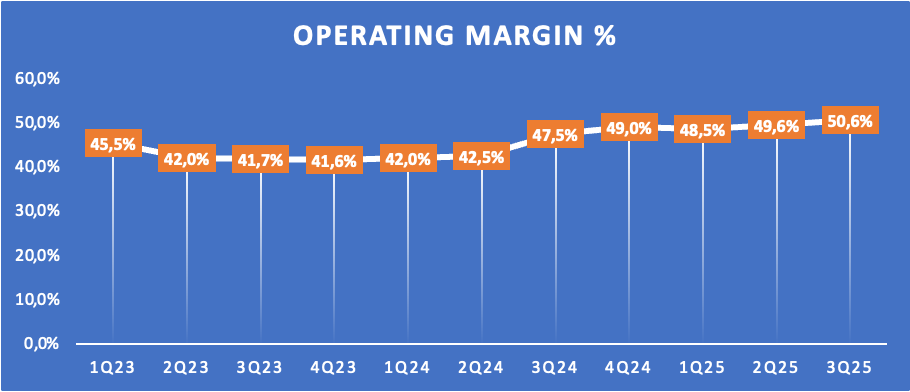
This controlled cost growth led to 39% YoY operating income growth, driven by strong revenue growth and 310 bps of margin expansion to 50.6%. This also led to a 290 bps net income margin expansion, translating into EPS of $2.92, beating the consensus by $0.32. In local currency, EPS was up 39% YoY, and TSMC delivered an ROE of 38%.
Finally, subtracting CapEx expenses of $9.7 billion, Q3 FCF was approximately $4.55 billion. This brings TTM FCF to roughly $29.1 billion, reflecting a 25% FCF margin.
TSMC remains a FCF machine, even amid significant CapEx investments. I mean, pumping out almost $30 billion in FCF in an elevated investment cycle is nothing short of sublime. This is, in large part, what makes it so hard to compete with, considering that the foundry industry is massively capital-intensive – good luck competing with this kind of financial power.
Unsurprisingly, this also allows TSMC to maintain a pristine balance sheet. The company ended the quarter with $90 billion in cash against a total debt of just $31 billion. This leaves it with $60 billion in net cash. That is some pristine financial health.
Ultimately, TSMC is an absolute powerhouse, and it is executing sublimely. These robust third-quarter results prove it once again.
I think Nvidia CEO Jensen Huang puts it perfectly:
“Well, first of all, I think TSMC is one of the greatest companies in the history of humanity, and anybody who wants to buy TSMC stock is a very smart person.”
Some quick notes on overseas expansion & technology
TSMC’s overseas expansion efforts remain well on track, boosting its geographic flexibility to meet customer needs and reducing investor concerns about geopolitical tensions.
In the U.S., the company’s Arizona fabs remain well on track. Last week, the first U.S.-manufactured Nvidia Blackwell chip was completed, and TSMC is speeding up its capacity expansion in Arizona. Notably, the company now indicates it plans to speed up its upgrade cycle in Arizona, preparing for more advanced node production than previously communicated, which is likely to meet U.S.-based customer demand. For reference, all advanced node capacity in Arizona is already under commitment from customers like Apple and Nvidia, so it makes sense to speed things up here, especially with AI momentum proving resilient.
Upon completion, the Arizona GigaFab will account for approximately 30% of TSMC’s advanced node capacity. In other words, 30% of its most crucial capacity will be outside of Taiwan, significantly reducing geopolitical risk.
On a final U.S.-related note, there were reports during the quarter that TSMC had committed to moving 50% of its production to the U.S., but these have been confirmed to be false. TSMC does remain fully committed to maintaining Taiwan as its main production center.
Apart from the U.S., expansion in Japan and Europe is also on track. Its first specialty fab in Kumamoto has already started volume production in late 2024, with an industry-leading yield. “The construction of our second fab has begun, and the ramp schedule will be based on our customers’ needs and market conditions,” to quote management.
Furthermore, in Europe, its specialty fab in Dresden, Germany, has also started production and is well on track. The production ramp will remain based on customers’ needs and market conditions.
On technology, management indicated that N2 is well on track for volume production in Q4 and a strong ramp in 2026, which is an excellent effort by TSMC. Furthermore, the next-generation N2 (N2P) is also on track for volume production in the second half of 2026, demonstrating rapid technological progress.
As I explained last time out, “management already indicates that 2nm is shaping up to be its most successful technology ramp yet, with a far better tape-out than 3nm and 5nm, fueled by both smartphone and HPC applications. For reference, N2 will deliver a power benefit of 10-15% at the same power or a 20% to 30% power improvement at the same speed, and a more than 15% chip density increase over the latest and most advanced 3nm node.
This is a very strong jump. No surprise that demand is high – this is precisely what the likes of Nvidia and AMD are looking for, for their most advanced data center chip designs.
Additionally, the company has its A16 technology in the pipeline, which is expected to provide an additional 8% to 10% speed improvement at the same power, or 15% to 20% power improvement at the same speed, along with an additional 7% to 10% chip density gain over N2. This makes it even better suited for specific HPC products with complex signal routes and a dense power delivery network.
This technology is expected to reach volume production in the second half of 2026, indicating rapid technological development by TSMC.
And that’s not all. During the earnings call, management also provided commentary on A14, which represents another technological advancement over A16. Compared to N2, A14 will provide a 10% to 15% speed improvement at the same power or a 20% to 30% power improvement at the same speed, and approximately a 20% chip density gain. This technology is on track for volume production in 2028.”
Technologically, TSMC remains at least 2-4 years ahead of any of its peers, and this gap is only widening thanks to its exceptional speed of innovation.
With that, let’s move on to outlook and valuation next!
Want more out of your subscription? Even more content like this weekly?
Consider InvestInsights PRO - $7.50/month ($70/annually)
This gets you:
A guaranteed 6+ stock analyses every month (roughly 2-4 paid-exclusive).
Full insight into my own portfolio (14% return CAGR since 2022).
Instant transaction alerts anytime I make a move (Fully transparent).
A complete overview of all my target prices and ratings (online available).
Want to keep reading? You will get full access to this TSMC analysis!
Outlook & Valuation
While the quarterly results were brilliant, I would argue the real highlight of the report was management’s guidance and medium-term commentary, which expressed strong confidence in the years ahead, with current dynamics much stronger than previously expected.
