

Today, I am not going to bother with an introduction and just delve straight into today’s subject, since we have plenty to go over, including Uber’s Q2 results, updating my view of the AV threat/opportunity, and ultimately updating the financial framework and view of the stock. Let’s go!
Last Wednesday, Uber released its second-quarter results, and while the headline numbers didn’t quite impress and came in a little lighter than expected on certain metrics, I will argue that Uber did deliver a very solid report that didn’t justify the 6% sell-off in the following trading session, especially considering shares already traded near a 12-month low.
Ultimately, Uber still beat the consensus on most metrics and delivered record highs across MAPCs, frequency, trips, gross bookings, margins, and cash flows, and showed very healthy momentum across the business. Really, I continue to struggle understanding why sentiment towards Uber remains this poor while the business continues to fire on all cylinders, defying the rule of large numbers, and improving its competitive position. As a shareholder, I don’t think we can ask for much more.
Anyway, delving into the Q2 numbers, let’s start at the very top – trips, which is still the cleanest indicator of platform health and growth. Positively, trip growth remained solid, although it did show a further deceleration from Q2 and fell a bit short of my expectation.
Uber reported Q2 trip growth of 18% YoY to 3.8 billion, a 2-point deceleration from 20% growth in Q1. Don’t get me wrong: that absolutely isn’t a bad performance. I mean, a business of this size growing trips by 18% YoY from a huge base is still a mighty performance, but the slowdown from recent quarters isn’t ideal and a bit unexpected.
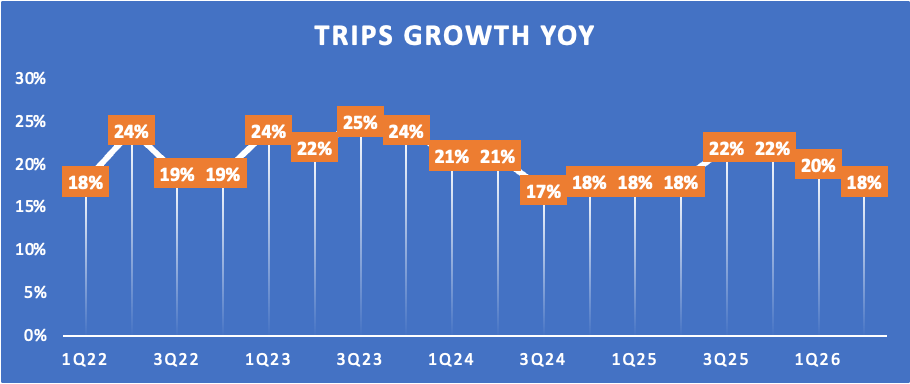
Positively, management indicated that this was mainly the result of weakness in Brazil, where Uber faced some supply softness, particularly in the very popular lower-cost products such as 2-wheelers. In other words, Uber faced a shortage of drivers in these popular categories in Brazil, resulting from a tighter labor market and elevated competition for two-wheel drivers from delivery platforms. And given this is its highest-volume market globally, the local headwind had a disproportionate impact on trip growth in Q2.
So, really, this 18% growth and the 2-point deceleration sequentially doesn’t tell the whole story, not quite reflecting a business-wide slowdown but just some local headwinds. Moreover, this is a very low-margin business for Uber, so the local weakness didn’t impact profitability and had only a modest impact on gross bookings. Really, weakness in this low-margin, low-revenue business just dragged down Trip growth.
And management indicated it is already seeing early signs of improving supply, allocating more investments in this direction to attract drivers to the platform in Brazil. Meanwhile, Uber did hold share, with mostly competition outside Uber’s mobility and delivery business impacting its driver base weakness.
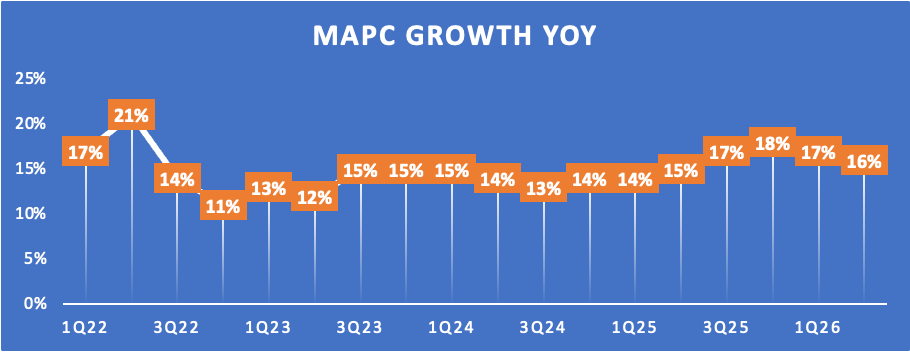
Meanwhile, under the hood, Uber’s trip growth continues to be driven by strong audience growth and record engagement. Especially Uber’s ability to keep growing its audience is quite incredible. MAPCs (monthly active users) grew 16% YoY in Q2 to a record 208 million.
That is a further slowdown from recent quarters, in part due to the headwinds in Brazil, but that is still hugely impressive growth from such a large base. And, according to management, it added more first-time users in the past twelve months than in any period over the past five years, showing brilliant momentum and highlighting that it still has ample room to grow.
Driving this strong growth in MAPCs and specifically the large inflow of new users in the last 12 months are mainly two factors. For one, Uber continues to roll out new lower-cost products globally, such as 2-wheeler and 3-wheeler options as well as Wait & Save in the U.S., which allows consumers to trade off time against price. And these low-cost options introduce a whole new sector of consumers onto the platform.
Second, there is Uber’s rapid expansion into sparse, more rural markets in the U.S., which were historically underserved. Uber has been investing heavily into growing its presence here, once again adding an entirely new customer base. And the runway here remains huge, with still less than 10% of eligible consumers in these rural regions using Uber over the last 12 months compared to over 50% in dense markets, large cities. Growing supply, reliability, and marketing to drive awareness should continue to be a strong contributor to MAPC growth in these sparser regions.
As the supply issue in Brazil gets resolved over the next couple of quarters, I honestly think Uber can continue to maintain MAPC growth in the 15-18% range over the next few years, given the underlying drivers and long expansion runway still available, be it through rural expansion, new price categories, or international expansion.
Then, on top of very healthy growth in monthly users, Uber also reported record engagement, with the number of monthly trips per MAPC up a solid 2% YoY. That is a slight slowdown from 3-4% in recent quarters, likely also due to the Brazil headwinds, so this should tick up again over the next few quarters. Nonetheless, not only is the number of users growing, but each of these also uses Uber more regularly, together driving the 18% growth in trips.
Overall, these healthy trip, MAPC, and engagement numbers show that actual demand momentum remains really strong for Uber, with no real weakness outside of supply issues in Brazil. Honestly, that is exactly what investors should want to see – a platform firing on all cylinders, showing no weakening demand and generally a good ability to capture this.
Let me say this again: these are the most important numbers to monitor to assess platform health, and we have little to complain about.
Moving on, this healthy growth in trips translated to Q2 gross bookings of $58 billion, exceeding the high end of guidance and up 22% YoY (constant currency), accelerating 1 point from Q1 and reflecting nearly the strongest growth in three years, despite the minor trip growth drag.
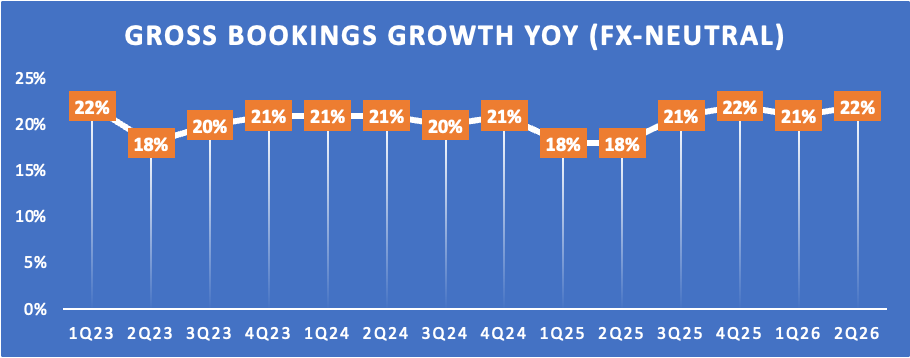
Trip growth is still the primary driver of gross bookings, but, as highlighted by gross bookings growth 4 points ahead of trip growth, pricing also contributed positively. However, this more so reflects a shift in mix than it does active pricing measures. If anything, Uber is actively working to reduce platform pricing to remain attractive to consumers as these face cost pressures.
Regarding the mix shift in Q2, there was an acceleration in the delivery business, which carries higher average transaction values (so higher prices per trip); the U.S. business accelerated, which also carries significantly higher average prices relative to international markets; and Uber saw strong growth in higher-value Mobility products (Reserve, Black, and U4B) against slowing growth in the low value moto business due to the Brazil headwind. For perspective, an average Uber Black trip costs a rider over 15x more than an average Moto trip globally, so a shifting mix here has an outsized impact.
Ultimately, actual underlying pricing was stable YoY, but these three factors drove a higher average price per trip, offsetting the lower trip growth.
Finally, the strong 22% growth in gross bookings translated to 11% revenue growth in Q2 to $14.2 billion, including an 8-percentage point headwind to the growth rate due to a business model change in the UK, moving some revenue from cost of revenue to contra-revenue, with no impact on the underlying economics (purely an optical, accounting-driven headwind). So, on a comparable basis, revenue was up about 19% YoY, which is a solid performance.
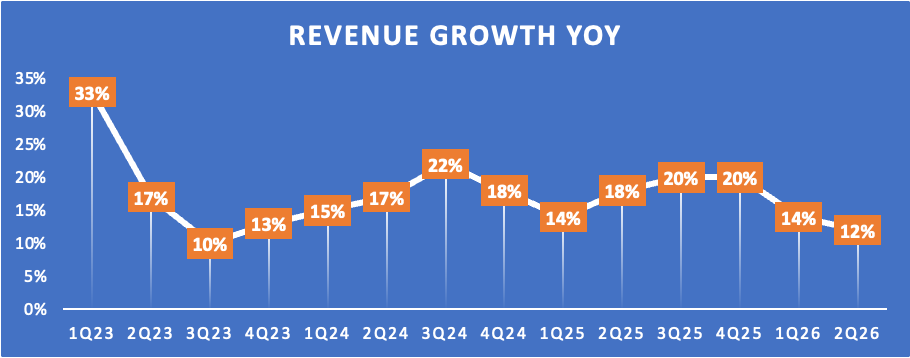
Making up the balance so far, I can only say I am really pleased with Uber’s top-line performance. Demand remains healthy, and Uber is executing well, as proven by very strong 22% gross bookings growth. Yes, trip and revenue growth look weaker, but these are dealing with specific headwinds that say little about the underlying business.
On that note, let’s break down the performance by segment, starting with Mobility.
Mobility gross bookings in Q2 remained strong, hitting $29 billion, up 20% YoY. That is nicely in line with Q1 and a step up from high-teens growth in 2025. And just for perspective, Lyft, Uber’s closest ride-hailing peer in the U.S., on Thursday reported Q2 gross bookings growth of 23% on a $5.5 billion gross bookings base. So, Uber is growing at nearly the same rate but on a 5x larger base.
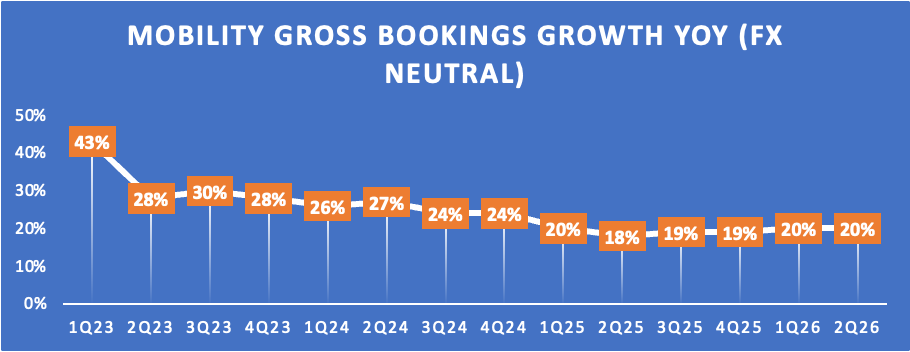
As expected, the main driver here was accelerating growth in the U.S., with trips and gross bookings accelerating YoY, driven primarily by strong consumer adoption of its newer premium and lower-cost products, with a broader offering making the platform more compelling to a larger user base. Higher-value products in particular, such as Reserve, Black and Uber for Business (U4B), continue to outgrow the core business. Take U4B, which delivered Q2 gross bookings growth of 40%+ YoY, highlighting the levers Uber can pull to drive growth.
Geographical expansion is another important growth driver for mobility. Uber plans to enter 100+ new cities, primarily in suburban and sparser areas, which are currently growing 1.5x faster than denser markets, while generating higher margins.
Overall, I am very happy with this growth Uber is able to deliver in mobility, despite its size, perfectly leveraging expansion opportunities. And I believe Uber still has a good runway ahead, with penetration still relatively low, keeping me confident Uber can maintain a high-teens to low-twenties mobility growth rate in the next couple of years at least.
Ultimately, the healthy performance in trips and gross bookings translated to mobility revenue of $7.4 billion, flat YoY due to a 400 bps impact to the revenue margin, reflecting the move of driver payment costs from cost of revenue to contra-revenue in the UK. The impact was consistent with the prior quarter and should remain similar for the remainder of 2026. For now, gross bookings growth is simply the best measure of performance.
Moving to the delivery segment, Uber’s performance here remains really impressive. Delivery gross bookings hit $27.5 billion, with growth reaccelerating to 25% YoY, the second strongest growth since the COVID peak and a nice 2-point uptick from 23% in Q1.
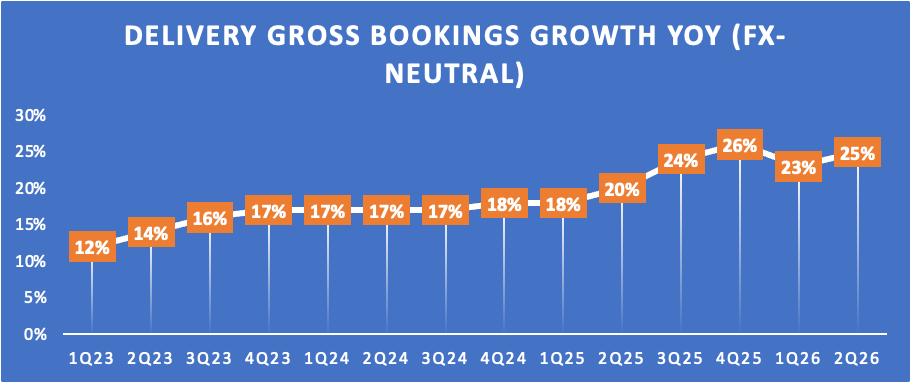
Growth in delivery was broad-based, with restaurant deliveries (the core business) accelerating, while Grocery and Retail (G&R) grew significantly faster. Also, consumer retention hit a multi-year high, so really strong execution overall. Internationally, Uber’s delivery momentum is strong, with the company once again improving its category position or market share in all of its top 10 international markets, including the UK, France, and Germany, which continues to drive a very strong outperformance against the broader delivery market. And Uber has still loads of room to enter new markets, with a launch in Finland in Q2, as well as expansion beyond Copenhagen in Denmark.
Meanwhile, G&R continues to be an important growth driver in the delivery operation as restaurant delivery matures. Simply, consumers increasingly want everything delivered at their doorstep, and that creates a large opportunity for Uber, sitting on one of the most extensive consumer and driver networks. G&R already hit $15 billion in annualized gross bookings in Q2, growing 40%+ for multiple quarters in a row. Growing selection is probably the most important driver of growth, with new partnerships with Decathlon, GameStop, Kiehl’s, Tesco, Toys’R’Us, and Ulta Beauty in Q2 simply expanding the range of products people can order through Uber.
Ultimately, the accelerating gross bookings growth drove Delivery revenue up 26% YoY to $5.3 billion, reflecting a slightly improved take rate.
Finally, worth noting here is the recently announced agreement to acquire European food delivery company Delivery Hero in an all-cash transaction valued at $14.8 billion. The acquisition creates a delivery behemoth in Europe, together operating in 100 markets globally.
There is no denying the deal makes sense for Uber, although I am not entirely convinced of the value, considering Uber’s strong organic expansion efforts, which are now halted, shelving five of the seven countries it had targeted for 2026. Positively, the price tag of Delivery Hero is quite attractive, and it does significantly expand Uber’s delivery business in one go, while also being EPS accretive from the start.
The deal is expected to close by the second half of 2027 due to plenty of antitrust bumps to overcome.
On that note, let’s move to the bottom line results.
Uber reported a gross margin of 39.3%, up 500 bps from the same quarter last year, but a large part of that expansion is driven by the same business model change that affected revenue. Practically, Uber moved UK driver payment costs out of cost of revenue and nets them directly against revenue (contra-revenue) instead. The net impact is practically zero – lower revenue gets offset by a similar reduction in cost. On top of that, Uber does continue to deliver genuine margin expansion. Insurance costs in particular were a tailwind.
Moving further down the line, SG&A costs were up about 23% and R&D up 24% YoY, so growing fairly strongly. Positively, Uber indicates it plans to moderate hiring for the remainder of the year and relative to its original plan, driven in part by stronger organizational effectiveness efforts and by AI-related productivity gains. This will likely allow for cost growth to ease.
Nonetheless, Uber was able to deliver healthy margin expansion, as it has been doing for years. It reported an operating income of $2.1 billion, up 40% YoY thanks to solid margin expansion.
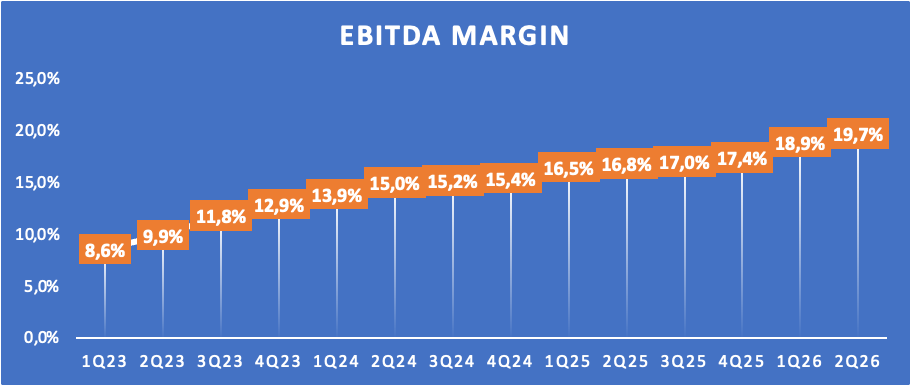
Furthermore, the adjusted EBITDA came in at $2.8 billion, up 33% YoY, with the EBITDA margin growing to 19.7%, up another 290 bps YoY and 80 bps sequentially to a new high. Uber has delivered sequential EBITDA margin expansion in every single quarter since Q1 2023, which is really exceptional, realizing an 11-point improvement.
Ultimately, this translated to a non-GAAP net income of $1.7 billion, up 29% YoY, and an EPS of $0.81, beating the consensus by $0.01 and up 35% YoY thanks to a lower share count. Meanwhile, GAAP net income was $2.4 billion, including a $1.6 billion net pre-tax tailwind from revaluations of equity investments.
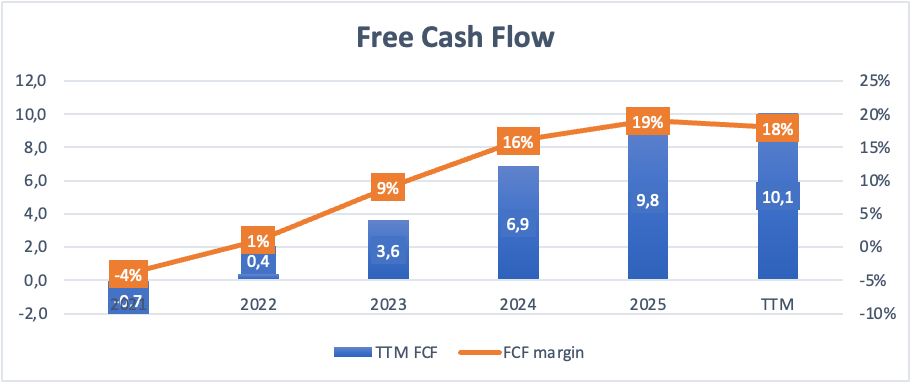
Finally, Uber reported a Q2 FCF of an excellent $2.8 billion, up 13% YoY and reflecting a 22% FCF margin. This brings the TTM total to $10.1 billion at an 18% FCF margin. When it comes to cash-generating abilities, Uber looks really good today.
In terms of financial health, Uber ended Q2 with total cash of $5.4 billion and $12.5 billion in equity investments, the majority of which are publicly listed. Uber’s available cash pile is down quite a bit compared to levels of over $9 billion in 2025, while its debt has also increased to nearly $15 billion at the end of Q2.
The reason for this is aggressive cash deployments in recent quarters to fund its AV ambitions, buy back its own stock, and build a position in Delivery Hero, which have outweighed its excellent cash flows. For reference, Uber deployed $4 billion in Q2 alone to build a 37% stake in Delivery Hero, while also still repurchasing $510 million of Uber stock (retiring 4% of shares over the past year).
Obviously, this is something to monitor closely. We know Uber will fund the Delivery Hero acquisition through a combination of existing liquidity and debt financing, which means it will probably add about an additional $5-7 billion in debt, and it still has optimistic ambitions in AVs.
Uber has now committed to $10 billion of investments over the coming years to bring AVs to market at scale. This includes investments with its partners, mostly through equity investments with clear milestones. Additionally, it will use cash to bootstrap the AV infrastructure on the ground, including support for fleet ops, real estate, or OEMs.
So, I expect this aggressive spending to last, but as cash flows continue to grow strongly, I see no financing issues for Uber.
All in all, the balance sheet looks healthy enough for now.
Then, on a final note, it is absolutely worth highlighting Uber’s excellent reinvestment metrics, which show that management knows how to deploy cash. Its TTM ROIC sits at a healthy 16%, well above the cost of capital, and its ROE is sublime at 37%.
Overall, I will argue Uber delivered an excellent quarter. Simple as that.
Uber One, Advertising, and AVs
Before we progress to the outlook, I want to briefly discuss three interesting subjects – Uber One subscriptions, advertising, and AVs.
Starting by briefly discussing Uber One, this continues to grow very nicely. The subscription format already counts over 50 million members globally, up more than 50% YoY and hitting a new record in Q2. Why is this important? Well, these are far more valuable platform users for Uber, using Uber much more intensively and therefore generating significantly more value. For reference, Uber One members now account for 70% of gross bookings, up 20 points YoY, while accounting for only roughly 25% of MAPCs.
The strong engagement and retention numbers continue to generate strong Uber One ROI for Uber, allowing it to keep expanding benefits, which in turn attracts new subscribers. Benefits include Travel Pass, Uber Cash back on hotels, and merchant-funded offers.
Next up, Uber’s advertising engine, while often underappreciated, is delivering strong growth and slowly becoming a more meaningful contributor. Advertising now exceeds $2.5 billion in annualized revenue, still growing 50% YoY quarter after quarter. It isn’t a game changer today, but it is an incremental revenue stream Uber is now actively monetizing within its existing platform, and as user engagement continues to grow, the appeal to advertisers does the same!
Finally, let’s address AVs. I broke down the AV threat/opportunity in depth back in my February 2026 analysis of Uber, which can be found here. Since then, my view of AVs hasn’t changed, so I am not going to delve into the subject in too much detail again, other than updating my stance following last quarter’s developments.
Basically, while the fear of AV disruption continues to hang over Uber shares, I still view Uber as greatly positioned to be a major beneficiary of AV commercialization and likely one of the largest platforms for future robotaxi deployments. This is driven by Uber’s huge head start in demand aggregation, marketplace orchestration, pricing, payments, trust, and, above all, global liquidity built across 200+ million users, which I believe makes it by far the best platform to commercialize AVs at scale in the future.
Let’s not underestimate the effort and time it takes to build the customer acquisition abilities, local operations, regulatory compliance, and safety infrastructure Uber has over decades. This means Uber is simply able to deliver better utilization and lower cost-to-market.
Above all, let’s not forget about the consumer’s POV. Beyond the excitement of the first few times trying an autonomous taxi, consumers care about availability, price, wait time, and reliability, not who owns the vehicle or wrote the software. If Uber consistently delivers an autonomous ride within minutes, a human driver to fill up the gaps in demand peaks, and does so with competitive pricing (currently unmatched due to size) and a familiar, trusted interface, switching to a separate AV-only app that offers longer ETAs, patchier coverage, or worse reliability simply doesn’t make sense, period.
That is absolutely the leading argument, and very hard to argue against.
Especially amid problems for AVs in bad weather and issues with variable demand, Uber’s hybrid network is perfect for consumers, by far the most reliable. This creates a reinforcing loop: consumers stay on Uber because it offers the best experience; AV operators stay on Uber because it delivers the highest utilization.
And Uber doesn’t need to win in every geography, every single city, and every single market. This absolutely isn’t going to be a winner-takes-it-all market. Some providers like Waymo or Tesla will run their own first-party platforms in some places, and leverage a combination of first- and third-party supply in others. This will coexist, so there is no need to freak out about some of those parties going their own way. Walmart isn’t a less good business because it faces competition in retail – the market is big enough. Uber is still formidable in food delivery despite a range of competitors in different parts of the world.
My point is that some competitors going with first-party solutions doesn’t eliminate Uber entirely, but the market acts as it does. Even amid these developments, I still believe Uber will be the leader in robotaxis in 10 or 20 years’ time due to the aforementioned arguments.
Looking at the last quarter, Uber continues to report good progress on its AV ambitions. Uber now has AV deployments in 7 cities globally, and remains on track for at least 15 by the end of the year. Last quarter, we saw the following announcements:
New deployments in Europe with Autobrains and WeRide. WeRide will launch in Madrid, exclusively on Uber.
Uber, Nuro, and Lucid have selected Houston as a second AV market to deploy following San Francisco earlier this year. Deployment should start mid 2027. Uber has already secured a 50K square-foot depot facility and dedicated charging pitstop in Houston to serve as the operational hub.
Uber and Wayve have received a Private Hire Vehicle license in London, paving the way for AV deployments over the next few weeks.
Across the ecosystem, Uber’s partners have now committed to 120,000 AVs over the coming years.
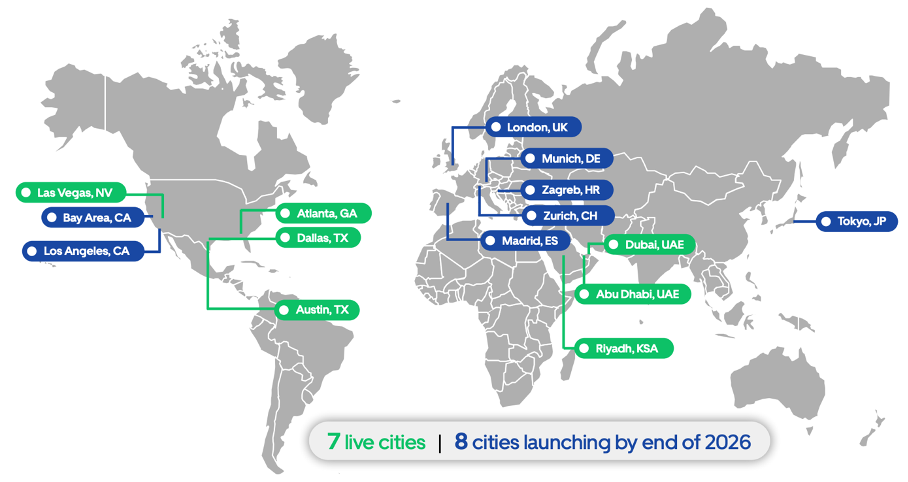
Of course, there was also the news of Waymo exploring options to end its partnership with Uber. The two currently operate AVs in Austin and Atlanta under a deal running through 2028. In fact, Waymo has informed Uber that it plans to enter those markets independently from January 2028. However, this does not mean Waymo vehicles will leave Uber immediately as of 2028, but Waymo is likely to offer rides through its own app and Uber in the initial stages, similar to its agreement with Lyft in Nashville.
Of course, I understand the news sounds bad to those already fearing AV disruption, but I don’t expect the expiration of the agreement will impact Uber in any way. As just explained, this isn’t a winner-takes-it-all market and Waymo focusing on its own platform doesn’t break the Uber thesis, even if it can gain serious traction in a handful of U.S. cities.
In fact, Uber indicates that in the most mature AV markets, including Los Angeles, San Francisco, and Phoenix, where multiple AV providers operate their own platforms, Uber actually gained market share over the past year, both citywide and in AV operating zones. What more confirmation that disruption fears are overblown do we need?
Again, my AV thesis remains unchanged.
More content like this? Consider InvestInsights Premium
InvestInsights Premium is designed to help you find best-in-class compounders, identify deep-value opportunities, avoid costly mistakes, and stay focused on fundamentals when markets get noisy, with full transparency into how I make decisions over time.
In practice, this gets you:
6–8 Research Reports per month, 2x more than free subs do, which includes 3-4 Deep Dives!
Full visibility into my personal portfolio, including allocations, transactions, and conviction levels
An overview of target prices and ratings, updated weekly, all available in a web-based Hub.
Price tag? Only $95 per year or $9.50 a month. That comes to just $1 per analysis, with the rest provided at no cost.
Sound useful? You can upgrade to Premium today using the button below!
Outlook & Valuation
As always, let’s start with management’s guidance. Management now forecasts Q3 gross bookings to come in at $58.25-60.25 billion, up 18-22% YoY in constant currency, suggesting a mild slowdown from Q2. Additionally, management expects Q3 Non-GAAP EPS of $0.84-0.88, representing growth of 28% to 35% YoY, which was a bit light compared to consensus expectations.
I have to admit, this isn’t the strongest guidance, coming in a bit light at the midpoint and below my initial expectations. But let’s not forget management tends to guide conservatively.
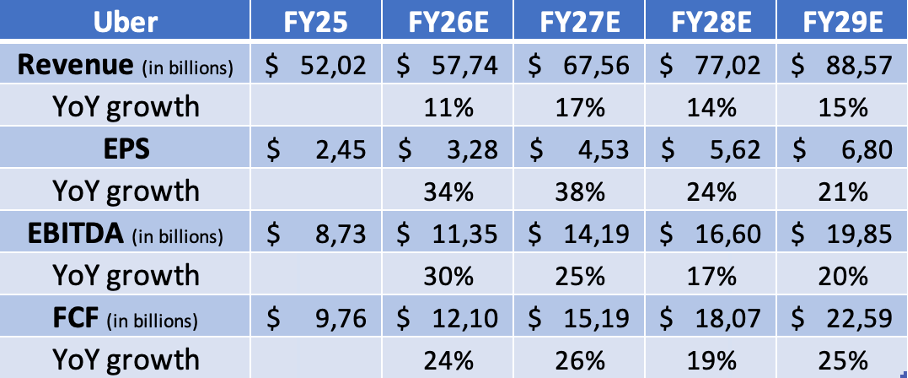
Moving to my own expectations, I have slightly trimmed my revenue estimate for 2026 to account for the lasting reporting headwind for revenue, which is now expected to remain similar in the second half of the year. At the same time, I have raised my expected EBITDA margin to 19.7% following better-than-expected margin expansion in the first half of the year, which means my EBITDA and FCF estimates remain unchanged.
Looking further ahead, Q2 did little to change my medium-term expectations. I have fine-tuned the numbers a bit, marginally lowering my revenue forecast, while lifting margins through 2029. As a result, I still expect Uber to maintain a healthy mid-teens growth rate between 2027 and 2029, driven by Uber’s room to expand into new markets within the U.S. and internationally, and subsequently grow MAPCs and engagement, fueling trip growth. I simply see no reason for growth to slow dramatically in the coming years when looking at current business momentum, growth drivers, and underlying trends.
On the bottom line, I still expect the rate of margin expansion to slow after 2026 to about 100 bps annually, with FCF slightly outgrowing EBITDA due to a better expected conversion rate linked to the business model. Also, EPS should grow even stronger thanks to Uber’s $16 billion remaining buyback authorization, allowing it to keep lowering the share count at a good rate.
Ultimately, this translates to a pretty strong outlook. As for AVs, I don’t anticipate this will have a real impact on Uber’s numbers in any of these years due to the ramp being slow. So, no positive or negative impact is assumed within these forecasts.
All these assumptions are reflected in my updated financial model below.
That brings me to valuation, and that is where the Uber thesis gets even more compelling today. Uber shares have been out of favor with investors for the better part of the last two years, with a current share price of roughly $75, practically flat since February 2024 despite strong growth and huge improvement in margins and cash flows, purely reflecting significant multiple contraction.
What justified that contraction? It certainly isn’t the financial results, which have been pretty sublime in recent years, with Uber maintaining gross bookings growth above 20% (similar to its closest peers, which is 5x smaller) and comparable revenue growth in the high-teens, all while rapidly expanding margins faster than anyone anticipated, with Uber now generating over $10 billion in annual FCF. Uber simply continues to defy the rule of large numbers and expectations.
The real reason for the lower multiples seems to be fears or at least uncertainty around AVs, which I just can’t wrap my head around. Don’t get me wrong, I get where it comes from, but every datapoint so far and simple business logic point to AVs not being any sort of disruption for Uber, as explained clearly. On top of that, the number of AV trips today isn’t even a fraction, sub-1%, of total rides, and not expected to become meaningful within this decade, simply due to the fact that this is a physical product still facing serious regulatory and infrastructure challenges.
In other words, discounting Uber on a potential headwind that might appear in the next decade is absolutely ridiculous + I deem it a potential opportunity more than a disruption in the first place.
As a result, Uber increasingly looks like a terrific business but a terrible stock, purely due to lasting negative sentiment, as proven once more by shares initially selling off by 6% on a genuinely strong report. At a price of $75 today, shares trade at:
23x 2026 earnings
A PEG of 0.8
13x 2026 EBITDA
12x 2026 FCF
Make of these numbers what you want, but in my opinion these multiples simply don’t rhyme with a platform this globally dominant, this high quality, in good financial health, incredibly FCF generative, and still forecasted to grow revenue at a mid-teens CAGR and EBITDA and FCF at a low-twenties CAGR through 2030.
These multiples reflect incredibly poor sentiment toward a business that is performing very well, purely the result of a misplaced disruption narrative. I deem it a matter of time before shares reprice toward their fair value, although I will acknowledge that this might take time due to a lack of near-term catalysts to uplift sentiment and relieve disruption fears – this is one for the patient investor.
But I am not an active trader, and I am not in a rush. Some high-conviction picks simply take time to play out. As famous investor Peter Lynch once said, “The typical big winner in the Lynch portfolio... generally takes three to ten years or more to play out.” He noted that where the fundamentals were promising, patience was often rewarded. Uber could turn out as a school example.
Anyway, when it comes to fair value, let’s be cautious and apply the same 18x EBITDA and 14x FCF multiple I used back in May, which I will argue is easily justified for this business, still leaving plenty of caution baked in and assuming a minimal rerating. Using those multiples and my updated financial forecast, I calculate an end-of-2028 target price of $136, which implies annualized returns of 27% from a current price of $75, nearly double my 15% threshold.
As is probably clear by now, I believe Uber shares reflect brilliant value at current prices. Anywhere under $86, Uber is a no-brainer, and I will happily continue to add to my position.
Rating + fair value: Strong Buy — Accumulate below $86
2028 Target Price: $136
Implied CAGR from current price: ~27%
Please leave a like if you enjoyed this post and found it valuable!

Hey Daan,
Great analysis, I have written an article about Uber recently as well and I think the current price is quite cheap, and it's a game of patience mostly and sentiment reversal as you mentioned!
I have no idea why people are so wind up about AV. AV can't threaten Uber due to many factors such as the expensive AV cars, the supply chain surrounding the LiDars etc, and the fact that AV will only work for a tiny segment of the market. I honestly can't see AV running around in Africa, Latin America, the Middle East, and most parts of Europe anytime soon. Even the economics of AV cost vs ride price in many of these countries will never work out. Finally, worst case scenario if a game changing technology gets introduced in the next 5-10 years, a safe bet would be Uber just acquiring one of these AV companies with their massive amounts of cash that they're going to pile up. That's my take!
Field notes on a recent Waymo trip for you. https://substack.com/@marketsaysno/note/c-310713648?r=3ep3fn&utm_medium=ios&utm_source=notes-share-action