

The best businesses in the world share one defining characteristic: they are impossible to replicate. Not difficult, not expensive, impossible.
A competitor can outspend you in marketing, undercut you on price, or poach your engineers. What they cannot do is build a 10,000-mile pipeline from scratch through the northeastern United States in 2025. Land rights do not exist, regulatory approvals would take decades, and the capital required would exceed the market value of the company you are trying to compete with. That is not a competitive advantage. It is a permanent monopoly, and permanent monopolies are among the rarest and most valuable things in investing.
Physical infrastructure businesses have always offered this kind of structural protection, but the current moment makes them particularly compelling. We are living through a genuine inflection point in global energy demand, one driven not by cyclical forces but by structural shifts that are likely to define the next two decades.
AI is consuming electricity at a pace the grid was never designed to handle. Europe is permanently rebuilding its energy supply chains after the rupture with Russian gas. Asia is industrializing faster than renewables can scale. In this environment, the companies that own the critical arteries of the energy system are not merely infrastructure businesses; they are essential national assets, and the market is only beginning to price them as such.
Williams Companies is the clearest expression of that thesis in the public markets today. One third of the nation’s natural gas moves through its network. Thirty percent of all US LNG exports flow through Transco. Its pipelines run directly through the data center corridors of Northern Virginia, the LNG export clusters of the Gulf Coast, and the most productive gas basins in the country.
This is not a bet on commodity prices or drilling cycles; it is a bet on the physical reality that the world needs more energy, that the US is uniquely positioned to supply it, and that Williams owns the infrastructure that makes it possible.
Let’s delve in – this is my Deep Dive into The Williams Companies, Inc.
Welcome to InvestInsights — an independent equity research publication rooted in long-term, buy-and-hold investing, publishing actionable stock/equity research reports weekly!
📈 You’re reading my latest [FREE] stock analysis. If you like this analysis, make sure to like & subscribe to receive much more like this, weekly!
This is Williams Companies!
Business fundamentals
As always, let’s start with getting a thorough understanding of the business.
Founded in 1908 and headquartered in Tulsa, Oklahoma, The Williams Companies (which I will refer to as Williams) has grown into one of the most consequential energy infrastructure companies in the United States today. Through its ownership of roughly 33,000 miles of pipeline across 24 states, Williams moves approximately one-third of the nation’s natural gas to homes, power plants, and industrial facilities, making it the undisputed natural gas leader in the U.S.
And no, this isn’t another commodity-exposed energy producer. Williams functions as an indispensable toll road in the natural gas supply chain. For investors seeking exposure to the structural growth in natural gas demand without the volatility of commodity price swings, Williams represents one of the clearest expressions of that thesis in the public markets.
Let me lay out why! But first, it might be helpful to briefly break down how the natural gas market is structured for those unfamiliar with it.
The natural gas market is best understood as a three-stage pipeline, both literally and figuratively. You see, every gas molecule follows the same physical journey before it reaches an end user, and each stage of that journey is where a different set of companies earns money.
The first stage is upstream, where producers drill wells and bring gas to the surface. Companies like EQT, Coterra, and Chesapeake operate here. They are price-takers and their economics rise and fall directly with whatever the market pays for gas that day.
The second stage is midstream, and this is where Williams comes into the picture. The midstream sector has five main components: gathering, processing, storing, transporting, and marketing natural gas. Gathering comes first, as small-diameter, low-pressure pipelines move raw natural gas from the wellhead to a processing plant or to an interconnection with a larger mainline pipeline.
At the processing plant, the raw gas is cleaned up: water, carbon dioxide, hydrogen sulfide, and heavier hydrocarbons are removed to produce pipeline-quality gas. Those heavier hydrocarbons, such as ethane, propane, and butane, are classified as natural gas liquids (NGLs), which are valuable in their own right as petrochemical feedstocks and fuels. Once processed, the gas enters the transmission system: wide-diameter, high-pressure interstate pipelines that cross state boundaries transport natural gas from producing and processing areas to storage facilities and distribution centers. From there, local distribution companies take over and deliver gas through smaller networks to homes and businesses.
Keep that in mind!
The third stage is downstream, including utilities, power plants, industrial facilities, and LNG export terminals that consume the gas or convert it for export.
That pretty much covers the natural gas supply chain.
Back to the business structure, Williams is organized across four reportable segments.
First of all, there is the Transmission & Gulf of America segment, which is by far the most important and the largest. This segment includes Transco, NWP, and MountainWest, three major interstate natural gas pipelines, alongside related storage facilities and crude oil handling assets in the Gulf Coast region.
Geographically, this segment covers the Gulf Coast to the Northeast corridor, the Pacific Northwest, and the Rocky Mountains. Think of it as the highway network in Williams’ portfolio – these are some of the most important pipelines in the U.S.
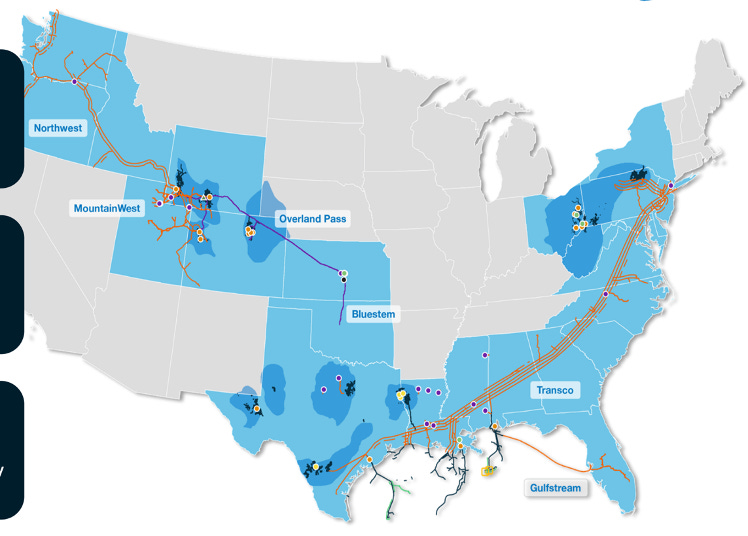
Transco, in particular, is the crown jewel: the largest-volume natural gas pipeline in the country, running from the Gulf Coast to the northeast. Transco alone transports roughly 16% of all natural gas consumed in the United States and 30% of total US LNG export capacity through its nearly 10,000-mile system connecting South Texas to New York, making it the single largest-volume interstate natural gas pipeline in the country, and the one that runs through the most supply-constrained, demand-dense corridor.
This is exactly what makes it such a valuable asset and a growth engine. This positioning means that every expansion project on Transco is essentially pre-sold before a single pipe is in the ground. That is sensational.
Meanwhile, the Northwest Pipeline (NWP) serves the Pacific Northwest (Washington and Oregon) and provides an important link between Rocky Mountain supply and West Coast demand markets. MountainWest, acquired in 2023, adds another regulated pipeline system serving Utah, Wyoming, and Colorado, and Williams has been expanding it with the Overthrust Westbound Expansion project.
The Gulf side of this segment covers deepwater gathering infrastructure in the Gulf of America (Gulf of Mexico), where Williams has described itself as holding an unmatched competitive position. Williams has been systematically expanding here, placing the Shenandoah, Salamanca, Whale, and Ballymore deepwater projects into service through 2025, each connecting new offshore production to its onshore pipeline network. The January 2024 acquisition of Gulf Coast Storage also added 115 Bcf of strategically located storage capacity, designed to serve the growing demand for LNG exports and power generation.
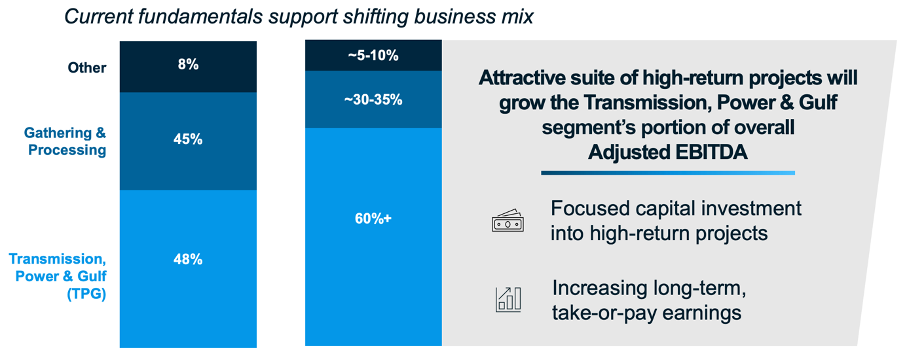
This segment alone accounted for approximately 48% of Williams’ 2024 adjusted EBITDA, and its share has been growing as Transco expansion projects continue to layer new contracted, fee-based revenues onto the system.
Second up is the Northeast G&P segment, which handles midstream gathering, processing, and fractionation in the prolific Marcellus Shale of Pennsylvania and New York, as well as the Utica Shale of eastern Ohio, covering the Appalachian region, the most productive and cheapest natural gas basin in the United States.
You can think of this segment as the feeder roads connecting to the highway (Transco) in the Northeast. This is a pure gathering and processing business focused on a single basin. The sheer scale of reserves here is almost incomprehensible, and it is where Williams has its largest gathering-and-processing footprint.
The challenge for Appalachian gas is not production economics; it is getting the gas out. Over the past decade, interstate pipeline development out of the Appalachian Basin has faced permitting challenges, opposition, and rising costs. As a result, some of the nation’s cheapest gas struggles to reach high-demand regions, amplifying regional volatility. This is precisely why Transco, running directly from the Gulf Coast through the Southeast and up to New York, is so valuable: it is one of the few high-capacity channels that can move Appalachian gas to where it commands the best prices.
So this is an absolutely lucrative segment for Williams.
Third up, the West segment also covers gathering, processing, and treating operations across a wide geographic footprint that includes the Haynesville Shale in Louisiana, the Barnett and Eagle Ford Shales in Texas, the Rocky Mountain region, the Anadarko and Permian basins, and the DJ Basin of Colorado.
You can think of this as the feeder roads in the western half of the country.
Finally, there is the Gas & NGL Marketing Services segment. This is a very different segment from the other three. This is Sequent Energy Management, Williams’ wholesale gas trading and marketing business. Sequent buys and sells gas, optimizes storage and transportation capacity, and increasingly supplies to LNG terminals. It has no major fixed infrastructure assets, but is a commercial intelligence and optimization platform sitting on top of the rest of the business.
It is the logistics and dispatch operation that maximizes the value of every molecule moving through the physical network. Its real strategic value lies in its role as an intelligence layer: Sequent’s market presence gives Williams real-time visibility into gas flows, pricing, and supply-and-demand dynamics across the country, which informs commercial decisions throughout the broader business.
Finally, the critical thing to understand about this segment is that it introduces commodity price sensitivity, specifically, unrealized gains and losses on commodity derivatives, which can cause significant swings in reported Modified EBITDA, which are almost entirely non-cash and excluded from adjusted EBITDA.
That covers its reporting segments.
Then, onto the most important question: how does Williams generate revenue?
At its core, Williams makes money in three simple ways.
The first and most valuable are the transmission fees, the fees for moving the gas. You see, what makes midstream fundamentally different from upstream is the fee-based business model. Approximately 95% of most midstream operators’ natural gas contracts are fee-based.
This means customers, such as power plants, utilities, LNG exporters, pay Williams a fixed fee to reserve capacity on its pipelines, particularly Transco. Think of it like a highway toll, except the customer pays whether they use the road or not. These are called take-or-pay contracts, meaning the customer owes the fee regardless of how much gas actually flows. Williams gets paid for making the capacity available, not just for moving molecules, which means it isn’t tied to commodity prices at all. If Transco’s customers reserve 34 Bcf/d of capacity at the start of the year, Williams earns the reservation fee all year, regardless of gas prices or drilling activity.
The fee-based structure is further reinforced by the long duration of the contracts underpinning it. Transco reservation contracts typically run 10-20 years, and these are FERC-regulated interstate pipelines, meaning their rates and terms of service are set through a formal regulatory process rather than negotiated freely in the market.
New projects like the Woodside Line 200 partnership are fully supported by 20-year take-or-pay contracts with fixed fee structures, which is now the template Williams applies to every major new project it sanctions.
So, Williams earns the same revenue whether Transco is 60% utilized or 100% utilized on any given day. This is why Williams can report record EBITDA in years when gas prices are near historic lows.
These transmission fees account for approximately half the business, generated by Transco, NWP, MountainWest, Deepwater Gulf, and Gulf Coast Storage. This is the most protected, most contracted, and most slowly variable part of the earnings base.
These are revenues of unequaled quality and predictability. These are anti-cyclical and inflation-adjusted. Revenues honestly don’t come any more reliable than this.
Second up, there are the gathering and processing fees. When a producer drills a well, the raw gas that comes out of the ground cannot go directly into a pipeline; it must first be collected, compressed, cleaned, and processed. Williams charges producers a per-unit fee for every step of that process: gathering the gas through its network of smaller pipes near the wellhead, compressing it, processing out impurities, and separating the valuable NGLs.
Again, this is largely fee-based. Williams earns by handling the molecule, not by owning it. The commodity price does not matter.
Yet, it is more sensitive. If producers cut drilling because gas prices are low, volumes soften over time. The MVC (minimum volume commitments) contracts provide a floor, but not an unlimited one. These MCVs are contractual floors that require producers to pay a fee even if they drill fewer wells and send less gas through the system than expected. If a customer fails to meet its MVC, it is obligated to pay a contractually determined fee based on the shortfall between actual volumes and the minimum commitment.
Nonetheless, this is where you see more quarter-to-quarter variability. This is why Williams has been deliberately rotating capital from mature basins toward growth areas such as the Haynesville and the deepwater Gulf.
These fees generate roughly 44% of EBITDA
Finally, there are the Sequent revenues. This is the smallest and most variable piece. Unlike the first two revenue streams, this one does have commodity price exposure, which is why it can swing significantly quarter to quarter. This brings in just 8% of EBITDA, and creates largely noise at the GAAP level, which is why adjusted. EBITDA is the preferred metric.
Overall, the key takeaway is that Williams is much more like a toll road operator than an energy company. The price of gas barely matters to its earnings — what matters is volume. As long as demand for natural gas keeps growing (and the structural drivers of power generation, LNG exports, and industrial demand suggest it will), more molecules flow through Williams’ pipes, and Williams earns more fees. That is the simplicity at the heart of a business that looks complicated on the surface.
And it sees very little of the industry’s cyclicality. The proof is in the track record. Williams reported its 13th consecutive year of adjusted EBITDA growth in 2025, an impressive level of consistency.
A pretty neat business, no? A brilliant way to gain exposure to energy/infrastructure without any of the industry’s risk!
But what about the growth outlook? Let’s break that down next.
Growth drivers
As laid out, Williams is entirely dependent on the U.S. natural gas market. The more volumes consumed and exported, the more revenues it will generate through its unequaled pipeline network.
And the natural gas market outlook is strong!
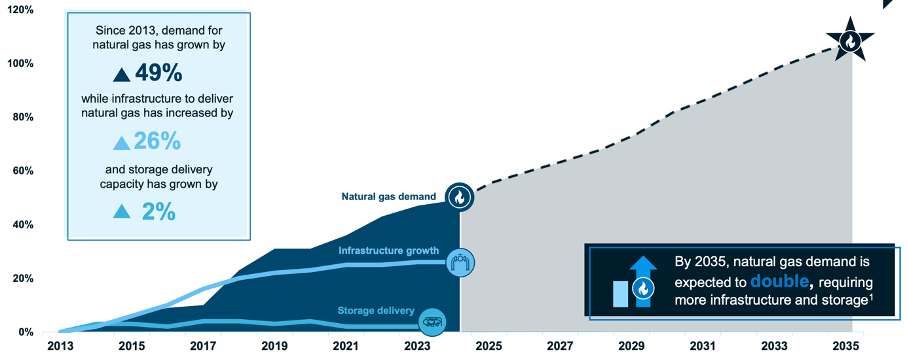
Natural gas is rapidly growing in importance as an energy source, driven by the phase-out of coal and the slow ramp-up of renewable energy. The IEA forecasts that US electricity demand will rise at a 1.9% compound annual growth rate through 2030, and that natural gas will be the dominant generation source, accounting for around 40% of the mix.
As a result, natural gas demand is expected to grow at a 3.2% CAGR through 2030, with production forecast to grow at 1-2% annually, which will immediately benefit Williams’ gathering and processing fees.
Furthermore, global natural gas demand is expected to double by 2035 and expected to account for 25% of global energy demand, according to current projections. And while bioenergy, oil, and coal use are projected to contract, natural gas will grow at least through 2040. It is the best transition energy.
This puts the U.S. in a very strong position. Apart from growing demand within the country, it will also fully benefit from export growth. You see, the U.S. has become the largest producer of natural gas over the last decade, doubling production since 2000 and now producing more than Russia (#2) and Iran (#3) combined. It holds 25% of the global market and is expected to grow significantly over the next 10 years, likely exceeding 50% by 2040.
In other words, production and volumes won’t be driven solely by U.S. demand but increasingly by global demand, significantly improving the long-term outlook.
And Williams remains a dominant force here, especially with key infrastructure near some of the biggest natural gas sources and with the ability to connect these to LNG export facilities.
Furthermore, Transco keeps getting bigger. Every few years, Williams announces a new tranche of Transco expansion projects — capacity additions that layer new, long-term, take-or-pay fee income onto the existing system at attractive returns. Williams currently has 13 transmission projects underway, representing 7.1 Bcf/d of capacity, and is on track to grow its delivery capacity by just over 20% from 2025 to 2030.
It keeps gaining volume share, which, combined with its favorable positioning (which drives outsized Gathering and Processing Volume Growth), puts it in the perfect position to well outpace the market.
Clearly, the outlook for Williams through 2030 is strong, and, by current forecasts, this already seems to extend through 2040. That is a compelling growth set-up.
This growth story increasingly runs through two mega-themes: power generation and LNG exports. These are big outlook deciders, so let me break these down to get a better sense of its outlook.
Let’s start with LNG exports.
The global LNG market is entering one of the most consequential expansion phases in its history, and Williams sits precisely at the center of it. Global LNG supply is projected to grow 59% by 2035, while US market share is set to expand from 24% to 37% of global supply over the same period, meaning the US is not merely participating in this growth wave; it is leading it. For Williams, this is not a passive tailwind. It is a structural, multi-decade demand driver that flows directly through infrastructure Williams already owns, is currently building, and has contractually locked in for generations.
US LNG exports have already undergone a remarkable transformation, surging from 0.5 Bcf/d in 2016 to 15.0 Bcf/d in 2025, making the US the world’s largest LNG exporter ahead of both Australia and Qatar. The next phase is equally dramatic. US LNG export capacity is on track to add an estimated 13.9 Bcf/d between 2025 and 2029, nearly doubling from 15.4 Bcf/d to almost 30 Bcf/d.
Between 2025 and 2030, around 345 bcm per year of new LNG export capacity is set to come online globally from projects already at FID and under construction, the largest wave of capacity additions in the history of LNG markets, with the US accounting for more than 55% of all FID capacity sanctioned since 2019.
The geopolitical backdrop is what makes this growth durable rather than cyclical. Europe’s structural decoupling from Russian pipeline gas has created long-term, binding demand for US LNG that will persist regardless of how the Ukraine conflict ultimately resolves.
And Williams is in one of the best possible positions to benefit from this growth in LNG export. It has systematically built direct revenue exposure across five distinct points in the LNG value chain, each generating a different type of fee income.
The most immediate and largest is Transco feedgas transmission. Every LNG terminal along the Gulf Coast requires a continuous, firm, uninterruptible supply of feedgas, the natural gas that gets liquefied and loaded onto ships.
Transco is the dominant artery serving that function, and Williams currently delivers approximately 30% of all US LNG feedgas. LNG terminal operators cannot afford idle liquefaction units due to supply interruptions, which creates natural demand for the highest-quality, longest-tenured take-or-pay transmission contracts, precisely what Transco offers. As US LNG exports continue expanding through 2030, so does the feedgas flowing through Transco, and so does the contracted fee income associated with it.
Williams has made clear that LNG export volumes along the Transco corridor are expected to more than double through the next decade.
The second mechanism is the Louisiana Energy Gateway. Williams built this 1.8 Bcf/d gathering and transportation system specifically to connect Haynesville Shale production, the lowest-cost, geographically closest major gas basin to Gulf Coast LNG terminals, directly to export demand centers. LEG came into service in July 2025 and is already contributing to West segment EBITDA as it ramps toward full capacity in tandem with Venture Global’s Plaquemines LNG facility.
The third mechanism is Gulf Coast storage. Williams integrated 115 Bcf of strategically located Gulf Coast storage capacity in January 2024, making it the largest storage owner on the Gulf Coast. LNG terminals require smooth, predictable feedgas delivery, but shale production and competing domestic demand are not perfectly smooth.
Williams’ storage assets sit between the producing basins and the LNG terminals, acting as shock absorbers that enable terminal operators to maintain continuous liquefaction despite short-term supply or demand fluctuations. Every LNG terminal in the Gulf Coast region has a commercial incentive to contract with Williams not only for transmission capacity but also for storage, creating a third, complementary revenue stream tied to the same underlying export growth trend.
The fourth and fifth mechanisms flow directly from the Woodside partnership.
In October 2025, Williams announced a strategic partnership with Woodside Energy. The partnership has two components. The first is Williams's acquisition of 80% ownership and operatorship of Driftwood Pipeline LLC, which includes Line 200, a fully permitted, 37-mile greenfield pipeline stretching from Ragley in Beauregard Parish to Carlyss in Calcasieu Parish, Louisiana, creating eight vital connections to systems, including Transco and the Louisiana Energy Gateway.
Williams will build and operate this pipeline as a fee-based infrastructure asset under 20-year take-or-pay contracts. The terminal cannot function without Line 200. The take-or-pay obligation is therefore as durable as the $17.5 billion terminal itself, which carries a projected 40-year asset life. This is as close to a guaranteed annuity as exists in the private sector.
The second component is a 10% equity interest in Louisiana LNG LLC and a 1.5 Mtpa LNG offtake obligation, giving Williams a direct participation in the global LNG market for the first time. Williams’ total annual share of LNG production will be 1.6 Mtpa. The total financial consideration paid was $378 million at signing, with approximately $1.9 billion in additional capital contributions over the project’s build period. Louisiana LNG is targeting its first LNG production in 2029.
This creates revenue viability for Williams well into the 2040s. And it capitalizes on a once-in-a-generation permitting advantage. Louisiana LNG holds all FERC certificates, environmental approvals, and export authorizations, an extraordinarily scarce asset in an environment where new LNG terminals face 5-10 year permitting timelines. Williams has effectively secured a contracted position in the most consequential new US LNG export facility of this decade at a moment when no competing infrastructure could be permitted and built in time to capture the same opportunity.
Can you see how Williams is optimized to benefit?
And on top of that, the Appalachian basin remains the largest and most economically competitive natural gas basin in the United States. Williams is the dominant gatherer in that basin, and a significant portion of Appalachian gas ultimately flows through Transco toward Gulf Coast LNG markets. Simultaneously, the Haynesville, the closest major dry gas basin to Gulf Coast export terminals, is Williams’ fastest-growing gathering market.
No other midstream company has assembled a comparable integrated position across the full LNG value chain. Therefore, I expect this to be a crucial driver of Williams's outperformance over the next decade or two.
And then there is the second huge driver of growth for natural gas demand – power generation.
Natural gas is already the largest domestic consumer of electricity in the United States, with its share of the power generation mix rising to an all-time high of 43% in 2024, and growing due to the closure of coal operations. But what has transformed the outlook from steady to explosive is artificial intelligence.
US data centers consumed 183 terawatt-hours of electricity in 2024, more than 4% of the country’s total consumption, roughly equivalent to the annual demand of the entire nation of Pakistan. By 2030, that figure is projected to grow 133% to 426 TWh. Until recently, the industry was adding roughly 500 MW of new capacity annually over the prior decade. That rate tripled in 2022, doubled again since then, and the capacity added in 2025 alone (likely over 10 GW) is comparable to New York City’s peak daily electricity demand.
US data center capacity is projected to grow from 25 GW in 2024 to more than 80 GW by 2030, with electricity demand increasing by approximately 400 terawatt-hours at a CAGR of around 23%. This drives the expectation for summer peak demand to grow at an annualized rate of 3.6% over the next decade, compared with just 0.3% per year a decade ago, a tenfold acceleration.
Natural gas is the most logical energy source to meet this demand.
Data centers operate 24 hours a day with essentially zero tolerance for outages. This creates a demand profile that renewables and nuclear simply cannot currently satisfy on their own.
Solar generation capacity factors run 10-25%, meaning the sun is not always shining when the servers need cooling. Wind is intermittent by nature. Battery storage at the four-hour duration currently available cannot backstop a 500 MW data center through multiple cloudy, windless days, and building enough storage to do so would be prohibitively expensive and physically impractical at hyperscale. Nuclear, though ultimately the cleanest baseload solution, cannot be deployed on timelines that match the urgency of demand, with even the most optimistic SMR deployment forecasts pointing to meaningful capacity only after 2031.
The grid itself compounds the problem. Interconnection delays are pushing the delivery of grid-connected power projects out by 5-7 years across all major ISOs, while data center developers must be operational within 18-36 months to meet market commitments.
Can you see the issue? Meanwhile, natural gas combined-cycle plants run at capacity factors exceeding 80%, can be ramped up within minutes, and a behind-the-meter gas plant can be built and operational in 12-18 months.
Natural gas is the indispensable bridge fuel for the AI buildout, and Williams sits at the center of that bridge.
The forecasts for incremental US natural gas demand from data centers by 2030 span a wide but consistently significant range. Goldman Sachs estimates 3.3 Bcf/d of new demand from data center power. S&P Global’s range is 3-6 Bcf/d. Moody’s puts it at 2-4 Bcf/d, with an upside scenario exceeding 10 Bcf/d. East Daley Analytics, monitoring over 400 active data center projects, estimates 6.5 Bcf/d.
The honest central estimate sits around 4-6 Bcf/d of incremental gas demand by 2030. Even the conservative end of that range is transformational for pipeline operators with the right positioning. Williams itself forecasts 10 Bcf/d of incremental power demand within the US through 2035.
And Williams is very actively attacking this market, with dedicated power projects.
The financial profile of these projects is exceptional. They target 5x EBITDA build multiples and secure 10-year fixed-price contracts with investment-grade hyperscalers. The 18-month build-and-in-service timeline dramatically compresses the capital deployment-to-earnings cycle compared to traditional pipeline projects, which typically require 36 months from FID to revenue. These are high-return, fast-cash projects that add discrete, contracted EBITDA increments to Williams’ compounding base at returns that justify aggressive capital deployment.
Williams has now committed $7.3 billion to fully contracted Power Innovation projects, which are expected to generate approximately $1.4 billion in annual EBITDA by 2029. The flagship project, Socrates, a 500 MW facility in New Albany, Ohio, serving a Meta-affiliated data center campus under a 10-year fixed-price power purchase agreement, is expected to enter service in the second half of 2026 and will be the first major EBITDA contributor from this new business line.
Beyond the $7 billion currently in execution, Williams has secured orders that ensure power project equipment supply into the early 2030s. Wells Fargo estimates Williams has approximately 10 gigawatts on order with equipment manufacturers, implying a shadow backlog of approximately $14 billion in additional opportunity beyond what has been formally announced. The company has announced approximately $5 billion of new Power Innovation projects in 2025 alone and now maintains a 6 GW commercialized power backlog.
So, a huge, high-margin opportunity to execute.
What makes Williams uniquely advantaged within the broader power and data center theme is the physical coincidence of its most critical infrastructure with the highest-density data center markets in the country. Transco commands approximately a 50% market share in the power generation market across its corridor, which runs directly through Northern Virginia, which hosts the largest concentration of data centers on earth. Northern Virginia alone could see data center power demand rise from approximately 4 GW today to 15 GW by 2030, potentially accounting for half of Virginia’s total electricity load.
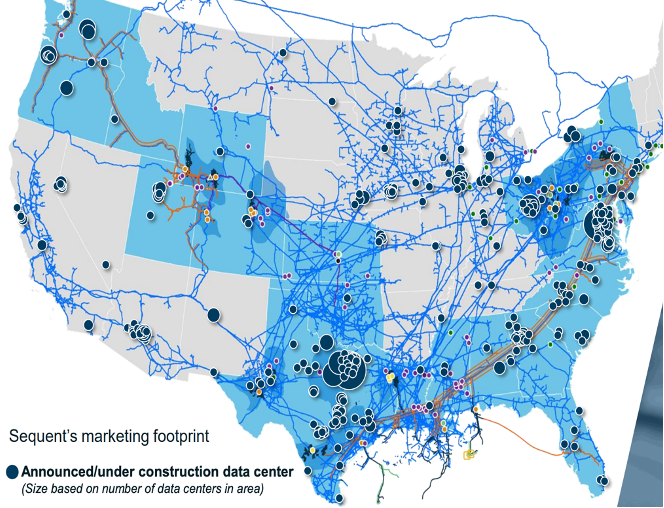
That is brilliant geographical positioning.
Now, this tailwind will probably ease beyond 2035, as nuclear SMRs begin entering service in meaningful volumes and the renewable-plus-storage cost equation continues to improve, so it is not as durable as LNG exports. However, the opportunity for the next decade is huge and a meaningful driver of growth.
Ultimately, it is safe to say the outlook for Williams is strong.
Yes, the natural gas market itself is expected to grow only 1-2%, but that only means it isn’t shrinking, which is perfect for Williams. But it means little for its outlook. The growth it can deliver depends far more on its capital deployment into new contracted projects, especially in the aforementioned high-growth areas.
Think of it like a toll road operator. The toll road earns $1 billion per year. It then builds a new interchange, which adds $100 million in contracted annual toll revenue. The toll road’s earnings just grew by 10%, even though total car traffic grew by only 2%. Williams is doing the same thing, at scale, across pipelines, gathering systems, storage facilities, and now power plants.
Williams’ growth comes from the capital it deploys apart from maintenance costs, which exceed $6 billion per year. And that is deployed into projects that convert into contracted EBITDA at 5–8x build multiples.
At a $7.75 billion EBITDA base, deploying $6 billion of capital at a 6x average build multiple generates roughly $1 billion in new annual EBITDA. And Williams is currently executing on $12 billion of contracted projects under construction and sees a potential total backlog of $37 billion, consisting of $15.5 billion in pipeline projects and the broader Power Innovation opportunity, with Wells Fargo estimating an additional shadow backlog of approximately $14 billion from equipment orders already placed.
This includes 13 transmission expansions that add ~14.3 Bcf/d, or ~21% growth in total delivered transmission capacity through 2030, driving incremental growth ahead of market rates. And as I said before, each of these expansion projects sees fully locked-in demand under 10-20-year contracts.
The company has a visible, contracted reinvestment runway of at least a decade, which is extraordinary.
This fuels management’s target of delivering 10%+ EBITDA growth, and, given management’s visibility, that is as reliable an outlook as it gets. In fact, 8% growth is already locked into its backlog today, with the remainder coming from contracts yet to be signed. Wells Fargo estimates its growth rate will exceed 12%, and based on current demand dynamics, that still seems cautious.
Moreover, management expects revenue to increasingly shift toward transmission, which is expected to outgrow all other revenue sources. While roughly 48% of EBITDA comes from transmission revenues today, which are the highest quality, take-or-pay revenues, this is poised to account for 60% of EBITDA by 2030, reducing commodity exposure and strengthening earnings visibility even further.
In other words, growth is not just getting larger; it is also getting higher quality at the same time.
That is a stunning outlook.
Longer-term, so 2030-2040, the picture is more nuanced. LNG growth continues, data center power demand extends, but the pace of renewable penetration is likely to matter more for domestic gas consumption. Its strategic moves into the LNG value chain are partly a hedge against this, extending its exposure to international demand that has a much longer growth runway than domestic power generation, but some easing of growth is likely.
Nonetheless, it is safe to say the outlook for Williams is mega, reliable, and largely locked in through 2035.
A mega moat
In addition to a strong outlook, Williams has a huge moat, but not one built on brand moat, network effects, or switching costs. It is built on even more fundamental factors: a physical and regulatory monopoly embedded in geography, combined with the near-impossibility of replication.
One of the most important dynamics to understand is that the constraint on the US natural gas market is not supply but infrastructure.
Building a new interstate pipeline in the US has become extraordinarily difficult. Environmental permitting, litigation, and community opposition have killed or delayed numerous projects over the past decade. The practical effect is that existing infrastructure, Transco above all, has become even more valuable over time, because the barriers to building competitive alternatives are prohibitively high. A new entrant cannot simply decide to build a competing pipeline along Transco’s corridor and expect to get it permitted and constructed in any reasonable timeframe.
For starters, the regulatory environment makes it functionally impossible. And even if a competitor were to get regulatory approval to build a new pipeline to compete with Transco, at today’s prices, that is estimated to cost between $85-100 billion, and that is before accounting for the decades it would take to obtain permits and build.
In other words, the replacement cost of just one of Williams’ three interstate transmission systems likely exceeds the company’s entire market value. Go figure.
And then we haven’t even addressed the land rights beneath it yet, which are arguably worth more and are entirely unavailable to any competitor. Transco’s right-of-way runs through some of the most densely populated, environmentally sensitive, and legally complex real estate in the United States.
Even if a competitor could somehow afford to build a parallel system and survive the regulatory gauntlet, they would face the near-impossibility of acquiring contiguous rights-of-way through those communities. Landowners in Virginia and New Jersey are not going to grant easements for a second major gas pipeline through their property, and environmental groups would litigate any attempt for decades.
That is the definition of a hard physical moat: no rational competitor would ever attempt to build an equivalent system from scratch. This is the irreplaceability argument for Williams in its most concrete form, and it is what transforms the business from an infrastructure operator into a toll-road monopoly on the most important natural gas corridor in the United States.
This is its primary competitive advantage. And because Williams has the only large-scale pipeline running from the Gulf Coast production to Northeast demand, it earns monopoly-like economics on the most important natural gas transportation route in the US.
In many parts of the Northeast, there is simply no alternative pipeline for gas to travel along. A utility in New England or a power plant in Virginia cannot route around Transco if they want gas from Gulf Coast or Appalachian supply basins delivered at scale.
That is as strong as a moat gets.
Financial & Performance Review
Williams released its latest financial results – FY25 – mid-February, combined with its 2026 investor day, and delivered stunning 2025 results that show excellent business momentum and a strong financial setup heading into the next 5 years, as it comfortably outperformed its set targets.
Let’s delve into the numbers!
Notably, this financial review is a little different than usual due to the nature of the business. Usually, I would start by breaking down its revenue performance, but there isn’t much point in doing so here, as revenue is a deeply misleading number at Williams.
The primary reason is the Gas & NGL Marketing Services segment. Sequent, Williams’ gas marketing subsidiary, buys and sells enormous volumes of gas in wholesale markets. When Sequent buys gas at $3/MMBtu and sells it at $3.10/MMBtu, it books the full $3.10 as revenue and $3.00 as cost. The result is that a relatively modest marketing margin generates massive gross revenue numbers that are economically meaningless for understanding the underlying business.
In a high-price-commodity environment, Sequent’s reported revenue can balloon by billions of dollars even though its margin contribution to Williams barely changes. In a low-price environment, revenue shrinks dramatically without any real deterioration in the business. This makes total revenue an extraordinarily noisy headline metric.
For these reasons, Williams’ management has deliberately built its entire investor communication framework around segment Modified EBITDA and Adjusted EBITDA rather than revenue. The EBITDA metrics strip out commodity derivative movements, one-time items, and marketing noise, leaving behind the underlying fee-based earnings power of the infrastructure itself.
That is the number that actually tells you how the business is doing.
So, let’s immediately get to the Adj. EBITDA.
And, impressively, Williams’ performance here has been sublime in recent years, highlighting the quality of the business and management’s ability to execute. In the first half of the decade, the company has consistently outperformed, even as the environment for natural gas was less favorable.
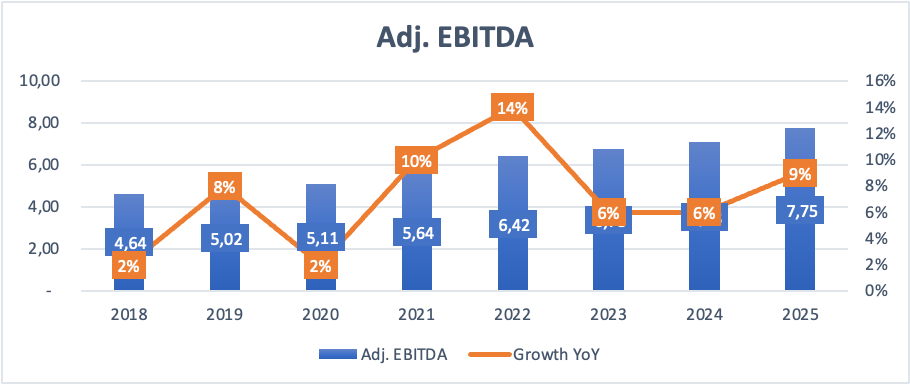
Nonetheless, the company has met or exceeded consensus estimates for 40 straight quarters and has delivered 13 straight years of positive EBITDA, highlighting its ability to deliver in any environment, whether it’s COVID lockdowns or record interest rates and sky-high inflation.
In 2025, Williams delivered another outstanding result, growing EBITDA by 9% to a record high of $7.75 billion, a notable acceleration from 6% growth in the two prior years and well exceeding the $7.4 billion target set two years ago.
Moreover, this means Williams has delivered a 9% EBITDA CAGR over the last 5 years, which fueled a 14% EPS CAGR. This is excellent, especially in a somewhat tough environment. You see, while Williams doesn’t care about the absolute gas price, the basis differential matters a great deal.
The national benchmark is the Henry Hub spot price, set at a physical hub in Louisiana. The average Henry Hub natural gas spot price in 2025 was $3.52/MMBtu, a 56% increase from the 2024 annual average, which, when adjusted for inflation, was the lowest on record.
The basis differential, the spread between prices at different geographic hubs, is what Williams captures as a value creator. When supply is trapped in a basin with insufficient takeaway capacity, gas prices in that basin crater relative to Henry Hub. The producer is stuck. When Williams builds a new pipe connecting that stranded supply to demand markets, it unlocks value for the producer, who is willing to sign a long-term, take-or-pay contract to guarantee access. This is the fundamental commercial logic behind every Transco expansion.
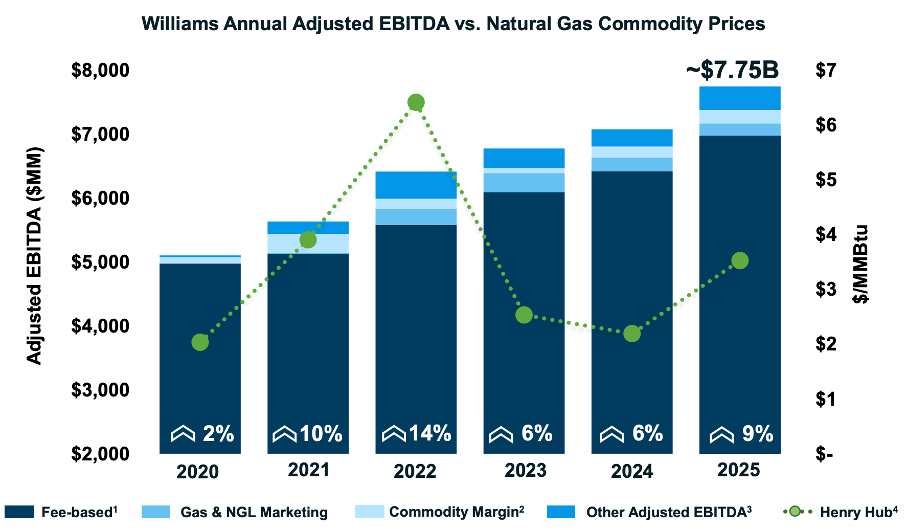
Need creates value, and the need wasn’t that great in the last 5 years, as demand was soft. Natural gas demand still drives Williams’ business, and we can clearly see that the business performs best in years when that demand increases, such as ‘21 and ‘22. So, again, Williams has seen steady growth amid low natural gas prices, but retains significant upside from higher natural gas demand.
The fact that management delivered a 9% CAGR in this low-demand environment, well exceeding its 5-7% guidance, is impressive.
Back to 2025, EBITDA growth was, unsurprisingly, primarily driven by the Transmission & Gulf business, which delivered 12% EBITDA growth, helped by 10 new pipeline Transmission and Gulf projects coming online and healthy growth in the natural gas storage businesses.
This segment continues to be the primary growth engine while delivering the highest-quality pay-for-fee revenue.
Meanwhile, the Northeast G&P business grew EBITDA by 3% in 2025, overcoming the EBITDA loss from the 2024 divestiture of our Aux Sable interest, which created a tough comparison. The West business grew 10% YoY in 2025, driven by investments in Haynesville and the DJ Basin, partially offset by a significant step-down in the Eagle Ford minimum volume commitments, as volumes from this mature basin continue to fall.
Nonetheless, the gathering business performance across both regions was solid, with investments showing clear payoff.
Finally, Gas & NGL Marketing EBITDA was down 28% YoY after adjusting for the benefit of the Cogentrix investment, so this was a small drag on group performance.
Further down the line, a key metric for investors to watch is AFFO (Available funds from operations). This is Williams’ primary measure of distributable cash flow, the metric that answers the question: how much real cash is the business generating that could be paid out to shareholders?
The starting point is net income, but AFFO makes several important adjustments to arrive at a figure that better reflects the recurring, cash-based earnings capacity of the infrastructure business.
The key adjustments are as follows:
Depreciation and amortization are added back because they are non-cash charges that reduce net income but do not represent cash leaving the business. This is particularly important at Williams, where the asset base is enormous, and D&A is correspondingly large, representing billions of dollars per year in accounting charges on pipelines that are still physically operating and generating real cash.
Unrealized gains and losses on commodity derivatives are removed. Sequent holds large derivative positions as part of its marketing and optimization activities, and the mark-to-market movements on those positions swing GAAP net income by hundreds of millions of dollars each quarter in ways that have no cash impact. Removing this noise is essential for understanding underlying cash generation.
Maintenance capital expenditure is subtracted. Unlike depreciation, which is an accounting estimate of asset wear, maintenance capex is the actual cash spent to keep existing assets operational. AFFO deducts this real cash outflow, which is why it is a more conservative and meaningful measure of distributable cash than simple EBITDA.
Distributions to non-controlling interests are also subtracted because Williams consolidates certain equity-method investments in which it does not own 100%, and the cash flowing to minority partners is not available to Williams shareholders.
The result is a figure representing cash, which is what the business actually generates that could, in principle, be distributed to common shareholders. Obviously, we prefer to see healthy growth here.
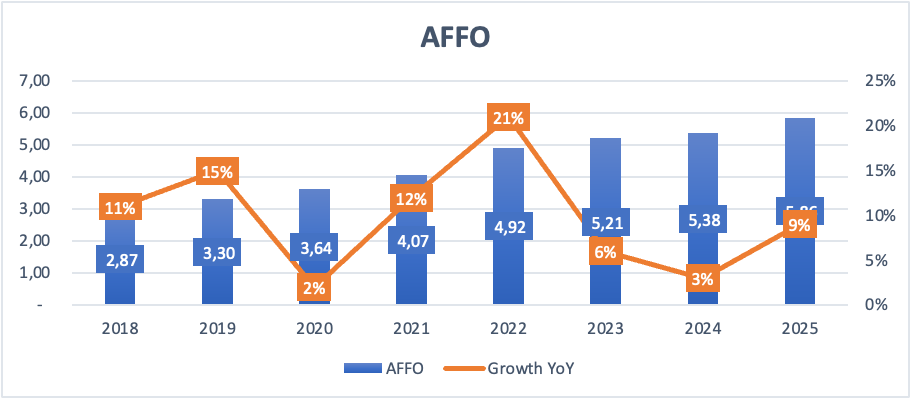
And Williams has delivered over the last few years, delivering a 10% AFFO CAGR and positive growth in every year since 2018, gradually growing cash flows to a record $5.86 billion in 2025, up 9% YoY. These excellent, growing cash flows fuel future investments, and allow Williams to maintain a healthy balance sheet and support lucrative dividends.
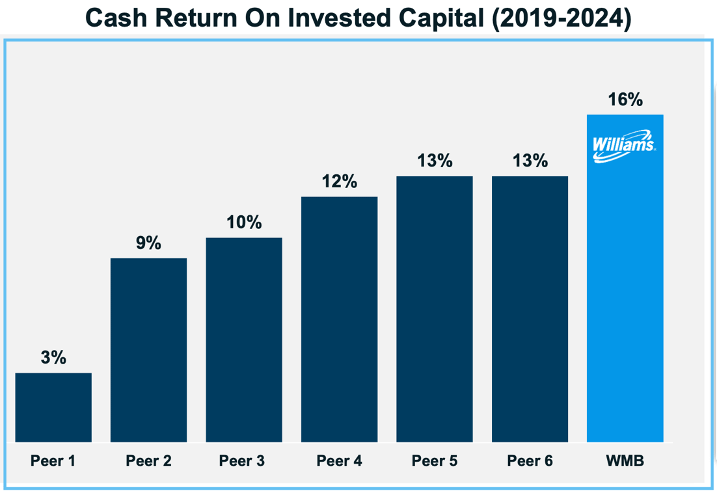
Finally, I want to highlight one of the most critical metrics for Williams, measuring its ability to execute: its CROIC, or Cash Return on Invested Capital. We now know Williams generates healthy cash flows, but whether it can deploy this cash at attractive rates of return is just as important, if not more so.
You see, Williams is fundamentally a capital deployment machine. The entire growth model ultimately rests on a single underlying question: when Williams spends a billion dollars building a new pipeline or power plant, how much cash does that billion dollars generate in return?
CROIC answers that question more precisely than almost any other metric, and for an infrastructure business like Williams, it is arguably the most important indicator of whether the compounding engine is working as intended.
CROIC is calculated simply: free cash flow divided by total invested capital. Where it differs from the more commonly cited ROIC is in the numerator; it uses actual cash generation rather than accounting earnings, which matters enormously at Williams.
Because Williams carries enormous depreciation charges on decades-old infrastructure, its accounting earnings consistently understate its true cash-generating power. The pipes that Transco laid in the 1950s and 1960s are largely depreciated on the books but are still physically operating and generating full fee income today. Using cash rather than net income corrects for this distortion and gives a truer picture of how productively the capital base is being deployed.
Why does this matter so much for Williams specifically? Because the entire investment thesis depends on a virtuous cycle that only works if the returns on new capital are genuinely attractive.
The cycle goes like this: Williams raises capital and deploys it into new contracted infrastructure at targeted 5-8x EBITDA build multiples. Those projects enter service, generate new fee-based EBITDA, expand the cash flow base, and create additional debt capacity. That expanded capacity then funds the next wave of projects, and the cycle repeats. Each iteration of the cycle lifts AFFO, lifts the dividend, and lifts the intrinsic value of the business.
But this cycle only compounds if the return on each incremental dollar of capital genuinely exceeds the cost of that capital. Positively, the strong AFFO growth already reveals that this balance is consistently positive for Williams.
In fact, this is where Williams is best in class. It currently delivers a peer-leading 16% CROIC, reflecting a history of high-margin investments. And management expects this to keep improving to over 20% before 2030, signaling that, in an environment of accelerating capital deployment, the pipeline of high-return opportunities is genuinely expanding.
That is a brilliant signal for long-term growth – this is a company delivering excellent returns on investment, generating strong cash flows, which it can then invest in even greater ROI opportunities.
In the meantime, its balance sheet looks alright and is within the targeted range. Management wants to maintain a net debt-to-EBITDA ratio between 3.5x and 4x, and it currently sits comfortably within this range at 3.71x, actually down 15% from 5 years ago. Yes, the balance sheet is leveraged, but this is well under control, as contractually predictable, take-or-pay cash flows can reliably service debt across economic cycles.
Finally, there is the dividend to address. Williams shares currently yield 2.92%, which is 5% below the energy sector median, but more importantly, 39% below its own 5-year average. The reason for the lower yield is the strong run-up in share price over recent years, which the dividend hasn’t kept pace with. The result is a significantly lower yield than peers, which is a trade-off investors have to make.
This makes Williams currently less interesting to dividend-income investors, but as a quality/growth investor myself, I am not spooked by the lower yield, since it comes with a higher-quality, faster-growing business.
A business with this kind of reliability and visibility, projected to grow by double digits, I quite like the nearly 3% yield that comes on top. And even more important, the dividend is sustainable and consistently growing.
The dividend coverage ratio currently sits at 2.41x, which means the dividend is covered 2.41x by AFFO, which is excellent. That leaves substantial room for growth and no risk of cuts. Management has grown at a 5% CAGR in recent years, with a 5.3% hike in 2025 and a likely 5% in 2026.
In the near term, dividend growth will likely remain in the mid-single digits as the focus is on heightened investments, but I expect it to accelerate toward the end of the decade to keep pace with EBITDA and AFFO in the double digits.
All in all, Williams is in excellent financial health, and its growth engine is firing on all cylinders, with all numbers pointing in the right direction.
More content like this? Consider InvestInsights Premium
InvestInsights Premium is designed to help you find best-in-class compounders, identify deep-value opportunities, avoid costly mistakes, and stay focused on fundamentals when markets get noisy, with full transparency into how I make decisions over time.
In practice, this gets you:
6–8 Research Reports per month, 2x more than free subs do, which includes 3-4 Deep Dives like this one!
Full visibility into my personal portfolio, including allocations, transactions, and conviction levels
An overview of target prices and ratings, updated weekly
Price tag? Only $95 per year or $9.50 a month. That comes to just $1 per analysis, with the rest provided at no cost.
Sound useful? You can upgrade to Premium today using the button below!
Outlook & Valuation
As always, let’s start with management’s near-term guidance. For 2026, management now guides for an Adj. EBITDA between $8.05 billion and $8.35 billion, with a midpoint of $8.2 billion, up 6% YoY, which is really strong, lapping the 2025 outperformance. Also, if you would adjust growth for asset sales YoY, growth would actually be closer to 7%.
Furthermore, management guides for:
EPS of $2.20-2.38, up 9% YoY
AFFO of $6.09-6.32 billion, up 6% YoY.
AFFO per share of $4.95-5.14, up 6% YoY.
Dividend coverage ratio of 2.41x.
That is healthy guidance overall.
However, capital allocation was probably the most significant guidance management gave in February, with 2026 growth CapEx guidance of $6.1-6.7 billion, up nearly 100% YoY. So, a huge step up there. The reason is the investment in 7 foundational projects, including 4 power innovation projects, totaling nearly $4 billion in CapEx, with a total investment of $7.3 billion at an average build multiple of 5x.
So, the primary reason for the hike in CapEx is investment in power projects at very lucrative return rates, which are pretty much entirely locked in. So, while the headline CapEx might raise concerns, the nearly-guaranteed payoff is huge.
Additionally, this CapEx also includes significant spending on Transco’s southeast supply enhancement project and some initial spending on Line 200 and the Northeast supply enhancement project. Crucially, all seven of these projects are 100% take-or-pay revenue streams with great credit profiles, so the risk associated with these investments is extremely small. And crucially, these investments are the foundation of earnings growth over the next decade.
However, these heightened investments will still put near-term pressure on the balance sheet, with leverage now expected to tick up to about 4x in 2026, at the upper end of the targeted range. This also includes a $100 million tax headwind from tax deferral effects on power projects and a maintenance CapEx of $900 million, flat YoY.
Looking further ahead, the outlook for Williams is very strong, as discussed. Whereas the company targeted 5-7% EBITDA growth in the prior 5 years and delivered a 9% CAGR, this is expected to meaningfully accelerate further through 2030, with management targeting a 10%+ Adj. EBITDA and EPS CAGR, in large part fueled by its huge investments, which are expected to deliver a strong CROIC.
And given management’s brilliant visibility, that is as reliable an outlook as it gets. In fact, the current backlog already accounts for an 8% EBITDA CAGR through 2030, so that is already fully locked in. The remainder will come from visibility on upcoming contracts, and that is very likely to drive way more than 2% additional growth, as discussed.
Based on its estimated shadow backlog, we should expect about $18 billion in cumulative CapEx over the next 5 years. Investing this at a 5x targeted multiple, the low-end of management’s target, we would get nearly $4 billion of new EBITDA on top of its current run rate, which isn’t yet included in the 8% guidance, and that is power alone. Sure, some of that EBITDA upside will be realized beyond 2030, but that leaves two important takeaways.
For one, the EBITDA upside relative to the locked-in 8% is huge through 2030, likely well exceeding the 10% guidance. I see room for this to come in anywhere between 12-14% through 2030.
On top of that, this kind of growth can likely be maintained well beyond 2030, given natural gas demand, potential transmission capacity, the power project backlog, and estimated in-service timing. For reference, power backlog already stretches into the early 2030s, with loads of additional upside as energy shortage grows.
According to management, growth might be more muted in 2026 and 2027, as reflected in the 6% guidance, but we will see a significant step-up in growth in 2028 as more projects come online.
Similarly, yes, balance sheet leverage will tick up in 2026, but as earnings growth accelerates in 2028, this should decline strongly. Based on the current balance sheet and timing, leverage will tick down to below 3x by 2030, leaving Williams with ample balance sheet room for new orders, additional CapEx, and strategic bolt-on acquisitions, supporting a strong outlook ahead of guidance.
In other words, excellent returns on invested capital drive growing balance sheet capacity to fuel additional growth. That is the way to look at this.
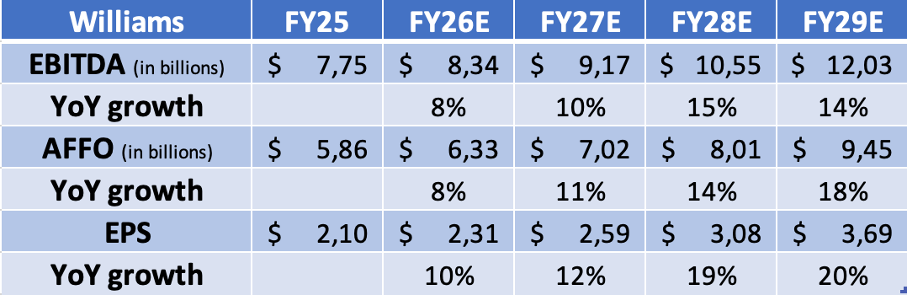
That then brings me to my forward projections. For 2026, I deem management’s guidance quite cautious, looking at current market dynamics, which can be quite favorable for Williams. So, I see room for EBITDA growth of 7.6% to $8.34 billion. I expect AFFO growth to be slightly ahead of that at 8.4%, driven by flat maintenance costs. Finally, EPS should grow slightly faster given historical trends, and slightly ahead of guidance, thanks to higher EBITDA.
In the following years, I am really optimistic. As discussed, demand for Williams’ infrastructure is booming, and I expect its favorable positioning in high-growth areas – LNG export and power – as well as its extremely favorable geographic positioning to fuel continued outperformance. Given the sheer room for investment ahead for Williams and its proven ability to execute, especially with fee-for-pay now the standard and revenue shifting more toward transmission and clear ROIC investments (with CROIC likely creeping toward 20%), I believe a 12-14% EBITDA and AFFO CAGR through the mid-2030s is very much achievable, while EPS will likely grow several percentage points ahead of this.
I do expect 2027 to still be a more muted year, as power investments in particular are yet to ramp and come online, offset by strong LNG export, but we should see a strong earnings pick up in 2028 as more investments come online, and we start to see high CapEx in 2026 and 2027 materialize. Growth should accelerate into the mid-teens by then.
These assumptions are reflected in the financial model below!
That then brings me to valuation, and it likely won’t come as a surprise that Williams is currently trading at quite hefty multiples compared to its history and peers, but arguably for very good reason. I mean, not many peers have a revenue stream this reliable and an outlook pointing to mid-teens earnings growth over the next decade, nor has Williams seen tailwinds this strong in its history.
Following a 23% share price run-up YTD and a 35% gain over the last twelve months, Williams shares now trade at:
14.5x 2026 EV/EBITDA, a 28% premium to the 5-year average.
Roughly 14x 2026 AFFO
31x 2026 earnings, a 35% premium to the 5-year average.
Those are not cheap multiples in isolation. But valuation is always relative, and the relevant question is not whether Williams looks expensive relative to its own history (it clearly does), but whether the business it is today justifies a higher multiple than it was five years ago. I would argue it does.
Revenue quality is much higher, with a larger share generated by transmission and locked up in guaranteed 10-20-year contracts. The moat is only getting stronger by the day, and the natural gas outlook has never looked better. But most importantly, the growth engine is firing on all cylinders (strong, improving CROIC, and strong cash flows), and the investment opportunities over the next decade are better than ever (more opportunities to deploy and put the growth engine to work), fueling an impressive 10-year outlook.
This company truly has the best years still ahead of it, so a good premium to historical averages seems a given.
Compared with its peers, Williams is clearly the most expensive. The four closest peers trade at 8-12.4x forward EV/EBITDA: Kinder Morgan at 12.4x, Enbridge at 12.4x, Enterprise Products at 11.3x, and Energy Transfer at 8x. However, KMI is expected to grow at half the rate. EPD’s projected growth is even slower, as it is more diversified. ET is more complex, has higher leverage, and is far more commodity-sensitive. And ENB is a closer comp, but still doesn’t come close in terms of growth rate.
In other words, the premium is more than justified, with Williams simply the highest-quality pick with a far stronger outlook and largely contracted, leaving little room for disappointment.
And that is what really makes it deserve a huge premium. Williams is an extremely reliable investment.
Nonetheless, I do think shares have run a little too high in 2026, with a lot of optimism being priced in. I think 14x EBITDA and AFFO is about fair, given the outlook and reliability, but I prefer a bit more margin of safety. Say we apply a 13x EV/EBITDA multiple to my current 2029 EBITDA estimate, which seems absolutely fair given the expectation of continued double-digit growth through 2035, the fact that most of this growth is already under contract, and the sheer room for upside.
Taking those numbers, I calculate an end-of-2029 EV of $156 billion. I assume a normalized leverage of 3.5x by 2029, giving me a 2029 market cap of $115 billion. Assuming a steady share count, that translates to potential annualized returns of 10-11% from a current share price of $72, including dividends, which isn’t a bad return at all for a highly defensive business.
However, it does fall short of my 12% threshold. I think fair value currently sits at roughly $83 billion, or a share price of $68, at which point the risk-reward balance becomes significantly more attractive. Currently, I deem shares 6% overpriced.
This is one of the finest infrastructure businesses in the world, but your entry point matters, and we should be cautious about overpaying, as it could destroy long-term returns. I don’t think current levels are a bad point to start DCA-ing, but I believe that anywhere below $68 per share, Williams becomes a really compelling long-term investment, giving high-quality exposure to the energy market.
This one is high up my watchlist right now, but I am watching from the sidelines for now!
Rating: Hold - Accumulate below $68
2029 Target Price: $115 billion
Implied CAGR from current price: ~10.5%
Please leave a like if you enjoyed this post and found it valuable!

Great analysis. Wondering where you have ET compared to WMB? ET arguably bringing better value and metrics